Taking Money Out of a Limited Company: Salary, Dividends and Director’s Loans Explained (2026/27)

Taking money out of a limited company is not as simple as transferring cash from the business account. As a director and shareholder, you have four main routes: salary through PAYE, dividends, expenses and benefits, and a director’s loan. Most owner-managers use a combination, usually a small salary plus dividends, because it keeps both personal and company tax down. The money you extract must follow formal rules, and getting the paperwork wrong can turn a tax-free withdrawal into a taxable benefit or a penalty.

Key takeaways:

  •  The four extraction routes are salary (via PAYE), dividends, expenses and benefits, and director’s loans.
  • The 2026/27 tax-free dividend allowance is £500; dividend tax rates are 10.75% (basic), 35.75% (higher) and 39.35% (additional rate).
  • Dividends can only be paid out of retained profits and must be formally declared and minuted.
  •  A director’s loan repaid within nine months and one day of the company year-end usually avoids the section 455 charge.
  •  As at September 2026, HMRC has not announced any changes to the tax treatment of money taken out of a limited company.

What Are the Four Routes for Taking Money Out of a Limited Company?

A limited company is a separate legal entity, so its money is not automatically yours. Every withdrawal needs a legal basis, and the rules for taking money out of a limited company differ depending on the route used. The four practical routes are :paying yourself a salary through PAYE as an employee of your company; paying dividends as a shareholder; reimbursing genuine business expenses and providing benefits; and borrowing money from the company through a director’s loan account. The right mix depends on your profits, other income and cash-flow needs. If you have money stuck in limited company reserves, Apex Accountants can help assess the available extraction routes and the tax impact of each before you take funds from the business. 

Salary, Expenses and Benefits

Run salary through PAYE: the company deducts income tax and employee National Insurance at source and pays employer National Insurance on pay above the secondary threshold. Salary is deductible for corporation tax, which is why even a modest salary usually beats dividends on the first slice of extraction. You can reimburse the business expenses you pay personally (travel to a client, professional subscriptions, equipment) tax-free, as long as they serve the business wholly and exclusively. Benefits such as a company phone follow their own tax and National Insurance rules, so check each one individually.

Our payroll services can manage director salaries, PAYE submissions and ongoing payroll compliance. 

Dividends: The 2026/27 Rules and Rates

Dividends are payments to shareholders out of the company’s retained profits. Before paying one, check if the company has sufficient distributable reserves, then the directors formally declare the dividend and keep minutes, even in a single-director company. Every shareholder receives a dividend voucher showing the date, amount and company.

The tax treatment of dividends depends on your total income and the tax band into which your dividend income falls. The 2026/27 dividend tax rates are: 

Dividend income after the allowance2026/27 tax rate
Within the basic rate band 10.75% 
Higher rate band 35.75%
Additional rate band 39.35%

The dividend allowance covers the first £500 of dividend income each year. These rates rose in April 2026, so older guidance showing 8.75% or 7.5% is out of date. Dividends do not reduce the company’s taxable profit: they come out of profit that has already suffered corporation tax (19% for small profits, 25% above the £250,000 main-rate threshold, with marginal relief between £50,000 and £250,000).

Director’s Loans: The Nine-Month Rule

A director’s loan is any money a director (or their close family) takes from the company that is not a salary, dividend, or reimbursed expense. It sits in the director’s loan account until repaid. Repay it within nine months and one day of the end of the company accounting period, and the company generally avoids the section 455 corporation tax charge on the outstanding balance. Repay later, and the company pays the charge, then reclaims it once the loan clears.

Two further rules matter. First, a loan of more than £10,000 at no or low interest creates a taxable benefit for the director unless the company charges HMRC’s official rate of interest. Second, if the company writes the loan off, the director pays income tax on the released amount as income. Used properly, a loan is a short-term cash-flow tool, not an extraction strategy.If you need to withdraw money from limited company funds before declaring a dividend or running salary, Apex Accountants can review whether a director’s loan is appropriate and explain the potential tax and repayment implications. 

Salary and Dividend Extraction: Worked Example

Take a one-person company with £60,000 of profit before any director remuneration in 2026/27. 

A common structure is:

  1. Salary of £12,570, covered entirely by the personal allowance (£12,570 in 2026/27, tapered above £100,000 of income), so no income tax is due personally. Employer National Insurance applies above the secondary threshold (£9,100 for 2026/27). Many small companies can offset some or all of this using the Employment Allowance (up to £5,000), subject to eligibility conditions. 
  2. Dividends of £37,430 from post-corporation-tax profit. The first £500 is covered by the dividend allowance; the remaining £36,930 falls in the basic rate band and is taxed at 10.75%, which is about £3,970.

Total personal tax on £50,000 of extraction: roughly £3,970, under 8% of the amount taken out. Compare that with taking the entire £50,000 as a salary, where income tax and National Insurance would take a much larger share. The exact optimum shifts with your circumstances, other income and the company’s profit level, which is why tax planning should be reviewed each year to make sure your extraction strategy remains appropriate as rates, allowances and profits change. If you have money stuck in limited company reserves, reviewing the available extraction options can also help you decide when and how to take profits while managing the tax impact.

Are the Rules on Extracting Money Changing?

HMRC ran a consultation on modernising the taxation of distributions that closed on 14 September 2026. It could eventually change how dividends, share buybacks and certain capital repayments are taxed and how the director’s loan rules interact with them. No law has changed. For what the consultation proposes and the timeline, see our dedicated guide to the 2026 distributions consultation, helping directors understand the possible changes before reviewing future extraction decisions.

Frequently Asked Questions

How much can I take out of my limited company tax-free?

In 2026/27, salary up to your available £12,570 Personal Allowance will normally be free of personal Income Tax, provided you have no other income using that allowance and your adjusted net income is not above £100,000. Employer National Insurance may still be payable by the company. 

Can I pay dividends if my company has no profit?

No. Dividends must come out of retained profits. Paying one without sufficient distributable reserves is an illegal distribution: HMRC can reclaim it from shareholders, and it creates a tax mess for both sides.

Do I need paperwork for every dividend?

Yes. The directors declare each dividend, minute it, and record it on a dividend voucher for each shareholder. Even a one-director company needs the minutes. HMRC can ask for them.

What happens if I don’t repay a director’s loan?

The company owes the section 455 charge on the balance, and if the company writes the loan off, you pay income tax on it. Interest-free loans over £10,000 also create a taxable benefit.

Is a salary or dividends better in 2026/27?

Usually both. A modest salary uses your personal allowance and employer National Insurance rules efficiently; dividends on top attract lower rates than salary. The exact split depends on your total income, so review the mix with your accountant each year.

How Apex Accountants Can Help

Choosing how to take money out of your limited company is one of the most valuable things an accountant does for you. Our corporation tax planning covers the salary-versus-dividend mix for your profit level; our payroll and auto-enrolment service runs your director salary through PAYE correctly; and our year-end tax planning declares dividends with proper paperwork and times them against your personal tax position, including Self Assessment registration deadlines. 

If you use director’s loans for cash flow, we review your loan account before every year-end so nothing lands as a surprise Section 455 charge. We help directors who want to withdraw money from limited company profits compare salary, dividends and director’s loans, model the tax cost and choose an appropriate extraction strategy for 2026/27. Book a free consultation, and we will model your optimum extraction mix for 2026/27.

If you are looking to know, feel free to contact us.
 

Business Rates Relief 2026: Could the Threshold Increase?

The current relief thresholds have not changed. Business rates relief 2026 has not adopted a £17,096 exemption threshold. A newspaper report on 18 September says the Treasury is considering raising the Small Business Rate Relief threshold ahead of the autumn budget. 

Its £17,096 figure illustrates an increase in line with inflation, not a precise government plan. GOV.UK still gives the current £12,000 and £15,000 limits. For now, a qualifying business using one property pays no business rates when its property’s rateable value is £12,000 or less; relief tapers to zero by £15,000. Check your current bill under today’s rules rather than budget for an unconfirmed cut. 

Key takeaways

  • In England, the current full-relief threshold is £12,000 of rateable value for a qualifying single-property business.
  • Relief reduces gradually between £12,001 and £15,000; owning or using more than one property can change eligibility.
  • The £17,096 figure is a newspaper illustration of possible changes to business rates relief, not an announced threshold or a promised saving.
  • If the 2026 revaluation increased your bill, ask your council whether other existing relief protects you.

What Is the Reported £17,096 Business Rates Proposal?

The Telegraph reported on 18 September that officials were considering raising the £12,000 full-relief threshold. It calculated that an increase in line with inflation would put that limit at £17,096 and discussed relief tapering to about £20,000. Those figures illustrate possibilities in one original report, not a Treasury commitment to either amount. The report does not establish whether, when or in what form any change might arrive.

There is no £17,096 threshold in the current published England rules. The practical question for a shop, cafe or small office is whether its current rateable value and property holdings qualify for relief today. Do not assume a budget announcement, start date or backdated refund.

Business rates are an important cost for hotels and other accommodation businesses to monitor. Our guide explains the impact of business rates hikes on UK hotels and accommodation providers. 

What Does Business Rates Relief 2026 Cover Now?

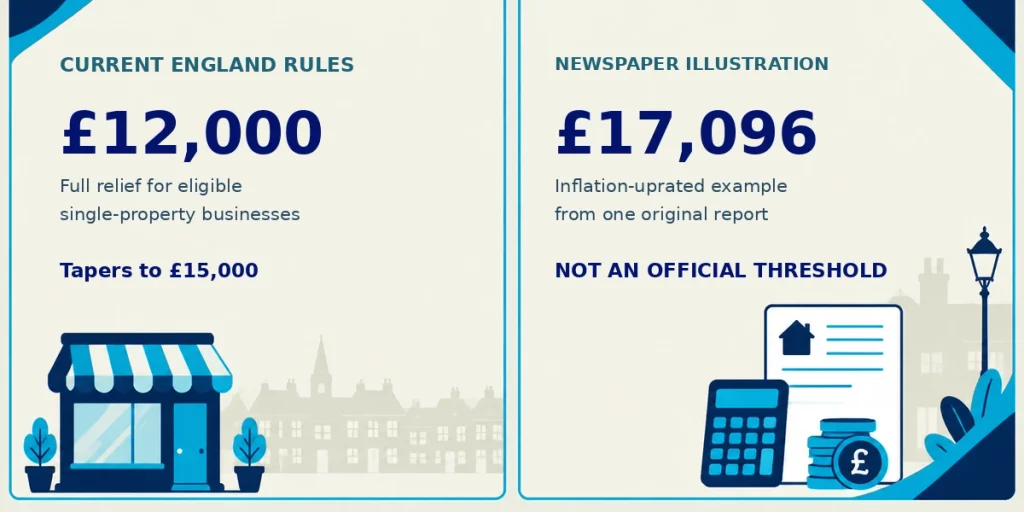
Current England small business rate relief threshold of £12,000 and taper to £15,000 compared with a £17,096 newspaper illustration that is not an official threshold.

Current small business rate relief can cut the bill for an eligible property with a rateable value below £15,000. If it is the only property your business uses, a value of £12,000 or less normally attracts 100% relief; from £12,001 to £15,000 the percentage falls to zero. For example, GOV.UK gives a property valued at £13,500 a 50% discount. Local businesses can check their eligibility before relying on the current relief thresholds.

Using more than one property does not always rule you out. If you took a second property on or after 27 November 2025, you can keep relief on your main property for 36 months; an earlier second property has a 12-month grace period. 

After that, each other property must have a rateable value no higher than £2,899, and the total across your properties must be below £20,000 (£28,000 in London). That existing multi-property limit is not the reported possible £20,000 taper. Your council decides eligibility. England’s rules are the focus here; Scotland, Wales and Northern Ireland operate different schemes.

England rateable valueCurrent Small Business Rate Relief positionIf the reported illustration became policy
£12,000 or lessNormally 100% if this is your only business propertyNo enacted change
£12,001 to £15,000Tapers from 100% to 0%An inflation-uprated full-relief limit could change the discount, but no figure has official status
£15,001 to £17,096No Small Business Rate Relief under the current thresholdSome eligible properties might qualify if a higher limit were enacted

A lower retail, hospitality and leisure multiplier can also lead to affecting a qualifying property’s bill. It is not the same thing as changing the Small Business Rate Relief threshold. Hence, keep those two measures separate when comparing bills. 

How Could the Proposal Change a Small Shop’s Bill?

Consider a qualifying single-property retail shop in England with a £13,500 rateable value and no other adjustment. Using the 2026/27 small retail, hospitality and leisure multiplier of 38.2p, its starting calculation is £13,500 × 0.382 = £5,157. The current 50% Small Business Rate Relief would reduce that illustrative annual bill to £2,578.50.

If a future change, such as raising the small business rate relief threshold, were made, the same property would be eligible for full relief under the increased threshold, assuming every other input remained the same. The illustrative reduction would be £2,578.50. This is a scenario, not a forecast or an entitlement. 

The final rules, timing, property valuation, multiplier and any other relief would determine a real bill. A non-retail office would use a different multiplier, while some premises have further adjustments, so this example is not a universal saving. 

For independent high-street shops, our expert accounting support can also help with reviewing business costs and planning around changes to these expenses. 

What Should You Check Before the Budget?

First, read your council’s latest business rates bill and check the property’s 2026 rateable value. Then confirm whether the bill already includes Small Business Rate Relief and whether your other premises affect eligibility. If your relief fell after the 1 April 2026 revaluation, ask the council about existing supporting relief rather than waiting for an unannounced reform.

Keep the current bill in your cash-flow forecast. If the government announces a threshold change, compare the published legislation and implementation date with your property’s circumstances before adjusting your expected savings.

To review the impact of Autumn Budget 2025, read: Key Takeaways From Autumn Budget 2025 For UK Business Owners

FAQs About Raising Small Business Rate Relief Threshold Proposal

How Can I Calculate My Business Rates for 2026?

Find the property’s rateable value and the applicable England multiplier, then account for reliefs shown on your council bill. The 2026/27 small-business multiplier is 43.2p; a qualifying retail, hospitality or leisure property below £51,000 uses a 38.2p multiplier. The City of London may use different multipliers. Your council can confirm the final calculation.

What Is the Threshold for Not Paying Business Rates?

For a qualifying business using only one property in England, the current 100% Small Business Rate Relief threshold is a rateable value of £12,000 or less. The £17,096 figure is a newspaper illustration, not an announced threshold. Other reliefs or exemptions have their own conditions.

What Qualifies for Business Relief?

For Small Business Rate Relief, start with the property’s rateable value, how many properties your business uses and the applicable multi-property rules. Other schemes have different tests, so ask your local council to check the specific relief on your bill. A business cannot claim relief under a £17,096 threshold today because no such rule has taken effect.

How Apex Accountants Can Help

Apex can review your rateable value and council bill with you, model your current business-rates cost and update your cash-flow forecast if there are changes to business rates relief. We can also help a shop or hospitality business separate the effect of its multiplier from the relief it receives. Contact Apex Accountants to review your present bill before making a budget-based spending decision.

What the HMRC Distributions Consultation 2026 Means for Company Owners

Company directors considering a share buyback, capital reduction or restructuring now have another factor to consider. HMRC’s consultation, “Modernising the taxation of distributions and repayments of capital from companies”, examines whether several long-standing rules governing value extracted from companies should be changed. The HMRC Distributions Consultation 2026 opened on 23 June 2026 and closed on 14 September 2026. None of the consultation proposals has, by itself, changed the current law.

The review matters because the tax consequences of extracting value from a company can differ materially depending on whether legislation treats the payment as an income tax distribution or a capital receipt subject to capital gains tax rules.

For 2026/27, dividend rates are 10.75%, 35.75% and 39.35%, depending on the shareholder’s tax band, with a £500 dividend allowance. The main CGT rates for individuals are 18% and 24%. Qualifying gains eligible for Business Asset Disposal Relief are charged at the separate BADR rate of 18% for disposals from 6 April 2026. 

Quick Answer

  • HMRC published the consultation on 23 June 2026, and it closed on 14 September 2026.
  • The consultation has not itself changed the law.
  • It examines seven areas of the distributions framework.
  • The main focus is shareholders within the income tax charge, principally individuals and trusts rather than corporate shareholders.
  • Areas under review include capital repayments, demergers, overseas taxation of company distributions, shareholder loans, share buybacks and transactions in securities.
  • Businesses should continue applying current law while distinguishing carefully between existing rules and consultation proposals.

What Is the HMRC Distributions Consultation 2026?

The consultation is a government review of how distributions and certain repayments of capital from companies should be taxed when the shareholder is within the income tax regime. HMRC says much of the underlying distribution framework has remained substantially unchanged since Corporation Tax was introduced in 1965.

HMRC is examining whether the existing rules remain appropriate where economically similar extractions can receive different tax treatment depending on their legal structure.

The consultation covers seven areas

  1. Reductions and repayments of share capital
  2. Corporate demergers
  3. Distributions from non-UK resident companies
  4. The interaction between distributions and loans to participators
  5. Loans and other temporary extractions from certain non-UK resident companies
  6. Purchase of Own Shares Relief
  7. Transactions in securities rules

The consultation is mainly concerned with shareholders subject to income tax. HMRC states that the proposals are not intended to affect corporate shareholders directly.

Have the Company Distribution Rules UK Changed Yet?

No. The consultation itself has not changed the company distribution rules UK that companies and shareholders currently apply.

HMRC says the government will analyse consultation responses and publish a summary following the consultation. It may also conduct further consultation on specific reforms before legislation is introduced.

The distinction between current law and proposed reform is therefore critical.

AreaCurrent PositionWhat the Consultation Considers
Ordinary dividendsExisting Income Tax rules continueNo general replacement of dividend taxation is proposed
Capital reductionsExisting distribution and CGT rules continueRevisiting how new consideration and capital repayments are calculated in certain restructurings
Share buybacksExisting Purchase of Own Shares rules continueReplacing some subjective conditions with more mechanical tests
Loans to participatorsExisting Section 455 rules continuePossible priority rules where distributions and shareholder loans overlap
Overseas taxation of company distributionsExisting foreign distribution rules continueCloser alignment with UK company distribution rules
Overseas shareholder loansNo equivalent general Section 455 charge on every overseas company loanPossible new rules for certain closely controlled non-UK companies
Transactions in SecuritiesExisting ITA 2007 provisions continueAmending or replacing the current regime

These remain consultation proposals unless and until legislation is enacted. If you want to know how much tax you could pay on your dividends? Use our free UK Dividend Tax Calculator to get an estimate based on your current circumstances.

Why Is HMRC Reviewing Repayments of Capital?

HMRC is reviewing repayments because certain restructurings can alter the amount regarded as share capital for distributions purposes without an equivalent new economic investment by the shareholder.

Under CTA 2010 section 1000(1)(B), a distribution out of a company’s assets in respect of its shares is generally within the distributions code, except to the extent that statutory exclusions apply, including a repayment of share capital or an amount representing new consideration received by the company. HMRC’s Company Taxation Manual confirms this treatment.

The consultation looks particularly at some share-for-share exchanges and holding-company restructurings.

Under certain existing arrangements, the value attributed to shares following a restructuring can produce a larger amount treated as capital for distribution purposes even where the shareholder has not contributed equivalent new funds.

The consultation considers whether the rules for new consideration and repayments of capital should be revised in these circumstances.

What Could That Mean for Company Owners?

If rules of this kind were enacted, some later payments that might currently fall partly within capital treatment could instead be treated more extensively as distributions.

This could change the capital distribution tax UK, particularly where a new holding company has been inserted above an existing business before capital is returned to shareholders.

However, this is not current law. The final approach may differ from the options discussed in the consultation.

How Could Purchase of Own Shares Tax Rules Change?

The consultation considers substantial changes to the conditions under which a company’s purchase of its own shares can receive capital rather than distribution treatment. The existing rules remain in force for now.

Under current Purchase of Own Shares rules, qualifying purchases by an unquoted trading company can receive capital treatment where statutory conditions are satisfied.

Current conditions include, among other matters:

  • the company generally being an unquoted trading company
  • the purchase being wholly or mainly for the benefit of the company’s trade
  • the seller being a UK resident
  • the seller generally having held the shares for at least five years
  • a substantial reduction in the seller’s interest
  • The seller must generally not be connected with the company immediately after the purchase, subject to the detailed statutory rules and exceptions.
  • anti-avoidance conditions concerning continued participation in company profits.

The five-year ownership period can be reduced in certain inherited-share cases.

What New Share Buyback Conditions Is HMRC Considering?

HMRC is considering the following conditions. These proposals do not currently replace the existing Purchase of Own Shares rules.

Options discussed in the consultation include:

  • requiring the seller to have at least a 5% equity interest
  • requiring ownership and employment with the company for at least two years
  • requiring the shareholder to surrender their entire shareholding and directorship
  • allowing certain staged exits where the shareholder fully leaves within two years
  • preventing consideration from exceeding market value
  • potentially applying a five-year ownership and working requirement where family connections with remaining shareholders continue
  • potentially withdrawing relief where a former shareholder returns as a shareholder or director within five years, subject to proposed exceptions.

These proposals could materially change the purchase of own shares tax planning if enacted, but they should not be applied as today’s eligibility test.

How Could the Consultation Affect Directors’ Loans and Loans to Participators?

The consultation explores possible rules for transactions where the distributions regime and participator loan rules can overlap.

Under current legislation, Section 455 CTA 2010 can impose a tax charge on a close company where it makes a loan or advance to a participator or certain associates and statutory conditions are satisfied.

For relevant loans and advances from 6 April 2026, the rate is 35.75%. The rate is linked to the dividend upper rate, which increased to 35.75% for 2026/27.

Importantly, Section 455 is generally a company-level tax charge, not simply an income tax charge imposed directly on the director receiving the loan.

The consultation explores possible mechanisms for resolving situations where a transaction could fall within both the distributions rules and Section 455.

Options include:

  • determining which tax regime should take priority
  • addressing payments originally intended as distributions that later become repayable
  • potentially placing aspects of HMRC’s treatment of inadvertent or defective distributions onto a statutory footing.

No new priority rule is currently in force.

Could Loans From Overseas Companies Face New UK Tax Rules?

Yes. The consultation separately considers whether new rules should apply to loans or other temporary extractions received from certain non-UK resident companies.

This is distinct from the existing Section 455 regime.

HMRC is considering circumstances involving a non-UK company that would broadly resemble a close company if it were a UK resident. Because the overseas company may itself fall outside the UK Corporation Tax charge, the consultation examines alternative ways of imposing an appropriate UK tax charge.

Some options could place liability on the UK-resident individual receiving the value, rather than replicating the existing UK close-company mechanism exactly.

This could be particularly relevant to UK-resident owners of overseas family businesses and closely controlled international companies.

Again, these are options being considered, not existing rules.

Could Distributions From Non-UK Companies Be Treated Differently?

Yes. The consultation explores whether the income tax treatment of distributions from non-UK resident companies should be brought closer to the treatment applying to UK resident companies.

Current international structures can raise difficulties because overseas corporate law does not always use concepts equivalent to UK share capital, dividends or capital repayments.

HMRC, therefore, asks how the UK should identify distributions and capital amounts where adequate information about a foreign company’s share capital or equivalent accounts is unavailable.

Any eventual reform could affect UK-resident individuals and trustees holding shares in overseas owner-managed companies or family businesses.

It does not mean that all overseas capital payments will automatically become dividends.

What Could Change for Corporate Demergers?

HMRC is considering whether the statutory demerger regime should be modernised alongside other changes to the distributions framework.

Existing statutory demerger provisions can allow qualifying transactions to proceed without what would otherwise be an Income Tax distribution charge, provided the detailed statutory conditions are satisfied.

The consultation recognises that tightening other routes to capital treatment could interfere with genuine commercial separations if the statutory demerger regime remains too restrictive.

HMRC therefore considers potential changes to conditions governing matters such as:

  • subsequent disposals
  • changes in control
  • cessation of activities
  • winding-up after a demerger.

These are consultation options and should not be treated as current statutory tests.

Businesses considering a demerger should continue applying the existing legislation and clearance procedures until any new rules are enacted.

What Could Happen to the Transactions in Securities Rules?

The government is considering whether to amend or replace the existing rules with an updated anti-avoidance regime. However, the design of any replacement remains under consideration and no new regime is currently in force.

The existing provisions are contained in Part 13, Chapter 1 of ITA 2007 for individuals.

Broadly, the rules can apply where transactions involving securities produce an Income Tax advantage and the statutory conditions are met.

They are particularly relevant where arrangements potentially convert what would otherwise be taxable income into capital.

An advance statutory clearance mechanism currently exists. HMRC must generally notify an applicant of its clearance decision within 30 days of receiving the necessary particulars or any further information it requests.

The consultation indicates that the government wants an updated regime that deals more clearly with modern transactions while preserving protection against income-to-capital conversion arrangements.

Why Does the Income Versus Capital Distinction Matter in 2026/27?

The distinction matters because dividend income tax and CGT apply under different rules, rates and relief regimes.

For the tax year 6 April 2026 to 5 April 2027:

Tax Treatment2026/27 Position
Dividend ordinary rate10.75%
Dividend upper rate35.75%
Dividend additional rate39.35%
Dividend allowance£500
Main CGT rates for individuals18% / 24%
Business Asset Disposal Relief rate18%
Individual CGT Annual Exempt Amount£3,000
Main CGT rate for most trustees24%
Annual Exempt Amount for most trustees£1,500

HMRC confirms the 2026/27 dividend rates and the £500 dividend allowance.

For disposals from 6 April 2026, HMRC confirms that the main CGT rates for individuals are 18% and 24%, while gains qualifying for Business Asset Disposal Relief or Investors’ Relief are charged at a separate 18% rate.

This distinction is important. BADR is not simply the standard 18% CGT rate and does not apply automatically to every share sale, company buyback or capital distribution.

The legal character of a transaction must be established before comparing possible tax rates.

For a broader explanation of current extraction methods, see Apex Accountants’ guide to taking money out of your limited company.

What Should Company Directors Do While the Consultation Is Unresolved?

Company directors should continue applying existing legislation but consider the consultation when planning transactions whose tax treatment depends heavily on whether an extraction is income or capital.

Particular care may be appropriate before:

  • introducing a holding company
  • reducing or repaying share capital
  • completing a significant company share buyback
  • restructuring a family-owned company
  • carrying out a statutory or non-statutory demerger
  • settling a substantial director’s loan account
  • extracting accumulated company value
  • entering arrangements potentially within transaction rules.

This does not mean these transactions should be postponed automatically.

The practical approach is to determine the capital distribution tax UK under current law, document the commercial purpose and then consider whether announced or proposed reforms create an additional timing or structuring risk.

FAQs

Has HMRC changed the rules for withdrawing money out of the company?

No. HMRC’s 2026 consultation has not itself changed the law. The consultation closed on 14 September 2026, and the government is considering responses before deciding which proposals should proceed.

Are capital repayments being abolished?

No. The consultation does not propose a general abolition of capital repayments. It examines, among other issues, whether the rules determining new consideration and repayments should change in certain restructuring situations.

Will every company share buyback become taxable as a dividend?

No. Existing purchase of own shares legislation continues to determine whether qualifying buybacks receive capital treatment. HMRC is considering different eligibility conditions, but those proposed tests have not yet replaced the current rules.

Does section 455 apply to every director’s loan?

No. Section 455 applies in specified circumstances where a close company makes a loan or advance to a participator or certain associates. Whether a charge arises depends on the company’s status, the recipient, the nature and timing of the loan and other statutory conditions.

For relevant loans from 6 April 2026, the Section 455 rate is 35.75%.

Can HMRC treat a capital transaction as income?

Potentially. Existing legislation can treat some company payments as distributions, while the Transactions in Securities provisions can counteract arrangements meeting the statutory conditions for an income tax advantage.

The correct treatment therefore depends on the legal form and substance of the transaction rather than simply how the payment is described.

Should I delay a company restructuring until the new rules are known?

Not automatically. Existing law remains applicable, and genuine commercial transactions can continue.

However, where a proposed restructuring depends heavily on capital treatment, directors should assess both the current statutory position and the possibility that future legislation could affect transactions implemented later.

How Can Apex Accountants Help With Company Distributions?

Before making a substantial shareholder extraction, completing a share buyback or restructuring a company, the next step is to establish how the transaction is taxed under current law, rather than planning on the assumption that consultation proposals are already effective.

Apex Accountants can review dividend planning, director’s loan accounts, capital transactions, company restructuring and shareholder extraction strategies. Our tax planning services can help assess the personal and company tax consequences before a transaction is implemented.

Where Corporation Tax issues are also involved, our corporation tax services provide further support with company tax compliance and planning.

How Company Car Tax Bands Work and What You Will Pay in 2026/27

In the UK, company cars available for private use normally create a benefit-in-kind tax charge. The value is based largely on the vehicle’s list price, while the applicable percentage is determined through company car tax bands based on CO₂ emissions, fuel type and, for some plug-in hybrids, electric-only range.

In practice, HMRC publishes percentage bands for each tax year. You multiply the car’s taxable list price by the relevant percentage to calculate the taxable benefit. Low-emission vehicles attract much lower percentages, while higher-emission cars can reach 37% in 2026/27.

The amount can also be affected by qualifying employee capital contributions, payments specifically required for private use, or periods of at least 30 consecutive days when the car is unavailable. HMRC provides official guidance on calculating company car benefits.

How Company Car Tax Bands Are Calculated

Benefit Calculation

Company car BIK is generally calculated using the car’s original list price, including VAT and taxable accessories, multiplied by the appropriate HMRC percentage.

For example, a petrol car emitting 145 g/km falls into a 35% band in 2026/27, while a fully electric car attracts a much lower 4% rate.

Emission Bands

Cars are grouped by CO₂ emissions measured in grams per kilometre. For cars emitting between 1g/km and 50g/km, electric-only range can also affect the percentage.

The following table summarises the 2026/27 company car tax rates alongside 2025/26:

CO₂ emissions (g/km) & electric range2025/26 rate (%)2026/27 rate (%)
Zero emission (fully electric)3%4%
1–50 (130+ mile electric range)3%4%
1–50 (70–129 mile range)6%7%
1–50 (40–69 mile range)9%10%
1–50 (30–39 mile range)13%14%
1–50 (under 30 mile range)15%16%
51–5416%17%
55–5917%18%
60–6418%19%
65–6919%20%
70–7420%21%
75 and above21%–37%21%–37%

Company car BIK rates for 2025/26 and 2026/27 by CO₂ emissions and electric range.

How to Calculate Company Car Tax

To work out the tax on company cars, you generally:

  1. Find the car’s taxable list price, including relevant accessories.
  2. Apply the appropriate BIK percentage.
  3. Multiply the resulting taxable benefit by the employee’s marginal Income Tax rate.

Example: A £30,000 fully electric company car has a 4% BIK rate in 2026/27.

£30,000 × 4% = £1,200 taxable benefit

A 20% taxpayer would therefore pay approximately £240 a year, while a 40% taxpayer would pay approximately £480 a year, assuming the car is available for the full tax year and no other adjustments apply.

You can also use HMRC’s company car and car fuel benefit calculator to calculate the taxable value for a specific vehicle.

Why Electric Cars Have the Lowest Tax Rates

Fully electric cars sit at the lowest end of the company car tax scale.

For 2025/26, the appropriate percentage is 3%. This rises to 4% for 2026/27.

Plug-in hybrids emitting between 1 g/km and 50 g/km with an electric range of at least 130 miles currently receive the same 4% rate in 2026/27.

This continues to make low-emission vehicles significantly more tax-efficient than many petrol and diesel company cars.

If your business is deciding whether to lease or purchase a vehicle, the VAT treatment can also affect the total cost. Our guide to VAT recovery on business cars explains the different rules for leased and purchased vehicles.

How Plug-in Hybrids and Mid-Range Cars Are Changing

Plug-in hybrids are also seeing increases in their appropriate percentages.

For 2026/27:

  • 1–50 g/km with a 70–129 mile electric range is taxed at 7%.
  • 1–50 g/km with a 40–69 mile range is taxed at 10%.
  • 1–50 g/km with less than 30 miles of electric range is taxed at 16%.
  • Cars emitting 65–69 g/km move from 19% in 2025/26 to 20% in 2026/27.

A plug-in hybrid with an electric-only range of around 100 miles therefore falls into the 7% band for 2026/27.

When These Changes Came Into Effect

The current rates apply from:

  • 6 April 2025 for the 2025/26 tax year
  • 6 April 2026 for the 2026/27 tax year

The changes form part of a gradual increase in company car appropriate percentages.

What to Expect in the Coming Years

Tax rates for zero-emission company cars will continue to rise gradually.

The currently legislated rates are:

  • 5% in 2027/28
  • 7% in 2028/29
  • 9% in 2029/30

The increases remain designed to preserve a significant tax advantage for zero-emission cars compared with conventional petrol and diesel vehicles.

HMRC has published the future company car tax rates for 2028 to 2030.

The Highest Tax Rates for Petrol and Diesel Cars

Petrol and diesel vehicles continue to sit at the upper end of the scale.

For 2026/27:

  • The maximum appropriate percentage is 37%.
  • The 37% maximum is reached at 155 g/km and above for standard petrol-powered cars.

In simple terms, higher emissions generally mean a higher taxable company car benefit.

Special Cases

The standard calculation can be adjusted in certain circumstances:

  • Capital contributions: qualifying employee contributions towards the cost of the car or accessories can reduce the price used in the benefit calculation, up to a maximum deduction of £5,000.
  • Periods of unavailability: the benefit can be reduced where the car is unavailable to the employee for at least 30 consecutive days.
  • Payments for private use: qualifying payments that the employee is required to make specifically for private use can reduce the taxable benefit.
  • Private fuel: employer-funded fuel for private journeys normally creates a separate fuel benefit charge. For 2026/27, the company car fuel benefit multiplier is £29,200.

Electricity is not treated as fuel for the company car fuel benefit charge.

Advisory Fuel Rates From September 2026

HMRC updates advisory fuel rates quarterly. The latest rates took effect on 1 September 2026 and apply when employers reimburse employees for business travel in company cars or when employees repay the cost of private fuel.

The current HMRC advisory fuel rates are:

Vehicle / engine sizeRate per mile
Petrol – 1400cc or less14p
Petrol – 1401cc to 2000cc17p
Petrol – over 2000 cc27p
Diesel – 1600cc or less15p
Diesel – 1601cc to 2000cc16p
Diesel – over 2000 cc22p
Electric – home charging7p
Electric – public charging15p

Hybrid cars are treated as petrol or diesel cars for advisory fuel-rate purposes. HMRC also allows employers to continue using the previous rates for up to one month after new rates take effect.

Key Points on Low-Emission Vehicles

  • Electric cars: Zero-emission cars have a 4% appropriate percentage in 2026/27, compared with 3% in 2025/26.
  • Plug-in hybrids: Cars emitting 1–50 g/km are taxed according to both CO₂ emissions and electric-only range.
  • Future changes: The zero-emission rate rises to 5% in 2027/28, 7% in 2028/29 and 9% in 2029/30.
  • List price matters: The benefit is calculated from the car’s tax value rather than its current second-hand value.

The relatively low 2026/27 company car tax rates for electric vehicles mean they continue to offer a considerable BIK advantage over many higher-emission alternatives.

How We Help Businesses Manage Tax on Company Cars

At Apex Accountants, we help businesses and employees navigate company car taxation and other taxable benefits. Our services include:

  • Tax planning for company cars: Advice on vehicle choices, salary sacrifice arrangements and calculating company car BIK.
  • Payroll and benefits administration: Managing P11D reporting, payroll adjustments and car-benefit reporting through our payroll services.
  • Company tax and VAT advice: Ensuring leasing, maintenance and other vehicle costs receive the correct tax and VAT treatment.
  • Employee tax support: Helping individuals understand the personal tax on company cars and how benefits affect their tax position.

Whether you are an employer arranging a fleet or an employee reviewing a company car package, our team can help you calculate the costs and apply the correct HMRC treatment.

Frequently Asked Questions About Tax on Company Cars

How is company car tax calculated in 2026/27?

Company car tax is generally calculated by multiplying the car’s taxable list price by the appropriate HMRC percentage based on its CO₂ emissions, fuel type and, where relevant, electric range. The resulting benefit is then taxed at the employee’s marginal Income Tax rate.

When do company car tax rates change?

Company car BIK percentages normally apply for each tax year beginning on 6 April. The current rates took effect on 6 April 2026. Advisory fuel rates are separate and are reviewed quarterly by HMRC.

How do I know which CO₂ figure to use for my car?

Use the vehicle’s officially approved CO₂ emissions figure. HMRC’s company car guidance and calculator use the relevant WLTP or applicable approved emissions information for the vehicle.

How much tax do you pay on an electric company car?

A fully electric company car has a 4% BIK rate in 2026/27. A £40,000 electric car therefore creates a £1,600 taxable benefit. That equates to approximately £320 a year for a 20% taxpayer or £640 for a 40% taxpayer, assuming full-year availability and no other adjustments.

What about tax on fuel costs?

If an employer provides fuel for private journeys, a separate fuel benefit may arise. The car fuel benefit multiplier is £29,200 for 2026/27. Electricity is not treated as fuel for this particular benefit charge.

What are the advisory fuel rates for electric cars from September 2026?

From 1 September 2026, HMRC’s advisory electricity rates for fully electric company cars are 7p per mile for home charging and 15p per mile for public charging.

Can I reduce my company car tax?

Potentially. Choosing a lower-emission or lower-list-price vehicle can reduce the taxable benefit. Qualifying employee capital contributions of up to £5,000 and payments specifically required for private use can also reduce the benefit in certain circumstances.

Simply paying for insurance does not automatically reduce the company car benefit, and an older car does not necessarily create a lower benefit because the calculation normally starts with its original list price.

Where can I find official information about company car tax?

HMRC publishes company car appropriate percentages, advisory fuel rates and its company car calculator on GOV.UK.

Employing Family Members in a UK Business: Why HMRC Is Asking Tougher Payroll Questions

More UK family firms than ever are employing family members, putting spouses, partners, and children on the payroll as they look for tax-efficient ways to run leaner businesses. It is one of the oldest tax planning moves in the book, and when done correctly, it is entirely legal. Yet HMRC continues to open inquiries into exactly this type of arrangement, often years after the salary was first paid. At Apex Accountants, family employment queries now land in our inbox nearly every week, usually starting with some version of the same question: “My accountant said this was fine, so why is HMRC asking questions now?”

We put together this Q&A to explain what proper family employment actually looks like, using the questions our own clients ask us most often.

Yes. There is nothing improper about paying a spouse, civil partner, or child for genuine work. HMRC’s own Employment Status Manual confirms that family employment is treated the same as any other employment relationship, provided the work is real. The trouble starts when the “employment” exists mainly on paper.

What is the “wholly and exclusively” rule everyone mentions?

This is the test HMRC applies to every deduction a business claims, and it matters more with family members than with anyone else. As set out in HMRC’s Business Income Manual, for a salary to reduce your taxable profit, the payment must be incurred wholly and exclusively for the purposes of the business. In simple words, your spouse or child needs to be doing a real job that the business genuinely needs, not simply receiving a wage because they happen to share your surname.

A client who came to Apex Accountants last year had been paying his wife a salary described only as “admin support” for three years, with no timesheet, no job description, and no record of tasks completed. When HMRC opened a check into his accounts, he could not demonstrate what she actually did. The result was a partial disallowance of the deduction and additional tax to pay, entirely avoidable with better record-keeping from day one.

Employing your spouse for tax purposes: does the pay have to match the market? 

Broadly, yes. HMRC’s guidance on wages paid to relatives makes clear that where a family member is paid more than someone unconnected would receive for the same role, skills, and hours, the excess can be disallowed. When employing your spouse for tax purposes, if your spouse manages your books for ten hours a week, the salary should reflect what a bookkeeper would realistically charge for that time, not an amount chosen purely to use up their personal allowance. 

What paperwork should be in place?

At minimum, a family employee should have:

  • A written contract of employment
  • A clear job description and set hours
  • Evidence of work actually carried out, such as invoices raised, emails sent or records maintained
  • Payslips processed through PAYE, exactly as for any other member of staff, after you have registered as an employer with HMRC
  • Pay that meets the National Minimum Wage where it applies, and pension auto-enrolment considered once thresholds are met

Skipping these steps is the single biggest reason family salaries get challenged. It is far easier to keep contemporaneous evidence than to reconstruct it years later during an HMRC enquiry.

Child employment rules UK: Can I employ my children in the business? 

Yes, subject to strict rules that many business owners are unaware of. Under child employment rules UK business owners need to understand, children generally cannot work at all before the age of 13, and even then only light work is permitted, according to GOV.UK’s guidance on the minimum ages children can work. GOV.UK also sets out restrictions on child employment, including limits on hours during term time and school holidays. Local councils can set their own bylaws on top of the national rules, and in most areas a child work permit is required before employment begins.

Once a child reaches school-leaving age, they can work full time, and the National Minimum Wage rates for their age band start to apply. School-aged children are not entitled to the National Minimum Wage, but the work must still be real and properly recorded, exactly as with a spouse.

What happens if HMRC decides the arrangement is not genuine?

If HMRC concludes that a family member is simply a route for shifting income to reduce the household’s overall tax bill, it can apply the settlements legislation. In practice this means the income is taxed as if it had never left the business owner’s hands in the first place, wiping out any saving and often triggering interest and penalties on top.

Our advice to clients

Employing family members can be a smart and legitimate way to run a small UK business, but only when it is handled properly. The role should be genuine, the pay should reflect the work done, and payroll records must be kept up to date. If you employ children, the specific rules around age, working hours, and the type of work they can do must also be followed.

In simple terms, HMRC expects family members to be treated like any other employee. That means clear duties, reasonable wages, proper PAYE reporting where required, and evidence that the work has actually been carried out.

Apex Accountants helps UK business owners review family payroll arrangements, improve compliance, and structure employment in a tax-efficient way. If you are unsure whether your current setup is correct, it is better to review it now than wait for HMRC to ask questions later.

Book a free consultation with Apex Accountants today to make sure your family business is set up properly and confidently.

Everything You Need to Know About Director’s Loan Write-Off and the Douglas Boulton Case

In a 2026 tax appeal, the First-tier Tribunal (Tax) upheld HMRC’s view that a written-off director’s loan triggers an income tax charge. The case involved Douglas Boulton, sole director of Sameday Express UK Ltd, who had an overdrawn director’s loan account (DLA). The company went into liquidation, and Boulton settled only part of the debt. When the remaining balance was “written off”, HMRC treated it as taxable income under Section 415 of the Income Tax (Trading and Other Income) Act 2005.

How Can a Director’s Loan Trigger Income Tax Charge?

Background of Douglas Boulton Case: 

Boulton’s 2013 company accounts showed a £151,802 loan owed to him. When the company liquidated in 2014, a creditors’ statement surprisingly listed just £18,000 owed. The liquidator challenged the amount and pursued the full balance.

Settlement

In March 2020 Boulton agreed to pay £60,000 in “full and final” settlement of the company’s claims (without admitting liability). Shortly after, the liquidator wrote to Boulton confirming the unpaid balance was “effectively written off” and advised him to report it as income.

Tax Return

Boulton filed his 2019–20 tax return in April 2021 but did not disclose the loan write-off. He believed that, since the settlement was without admission of liability, there was no formal debt forgiveness.

HMRC Action and the Discovery Assessment

In 2023, HMRC issued a discovery assessment for £91,802 on Douglas Boulton, the sole director of Sameday Express UK Ltd. This amount represented the original loan of £151,802 minus the £60,000 Boulton had already repaid. HMRC’s decision was based on the assumption that the remaining debt had been released or written off. Additionally, HMRC imposed a 15% penalty for failing to declare this income.

Tribunal’s Ruling

Boulton appealed this assessment to the tax tribunal, which ruled in HMRC’s favour. The tribunal agreed that the loan had effectively been written off and was therefore taxable under Section 415 of the Income Tax (Trading and Other Income) Act 2005 (ITTOIA 2005).

  • Section 415 ITTOIA 2005 mandates that individuals are liable for tax on any loan from a close company that is written off or released.
  • The tribunal concluded that Boulton’s loan had been discharged when the liquidator ceased all efforts to recover the remaining balance and confirmed that it was written off.

In essence, the tribunal ruled that Boulton had received a taxable income in the form of the £91,802 that had been forgiven.

Key Points in the Tribunal’s Decision

  • Settlement Agreement: The tribunal noted that the language of “full and final settlement” in Boulton’s agreement signified that the remaining loan was forgiven. Although there was no explicit admission of liability, the facts showed that the liquidator treated the unpaid balance as irrecoverable.
  • HMRC’s Manual: HMRC’s guidance on liquidation settlements clarified that when a company settles a loan and leaves part of it unpaid, the unpaid portion is considered written off for tax purposes. This applies even if the liquidator stops chasing the debt or if they accept a partial payment as full discharge.
  • In Boulton’s case, the liquidator’s confirmation that the remaining £91,802 was no longer recoverable confirmed that the loan had been written off.

HMRC’s Interpretation of Director’s Loan Write-Offs

HMRC’s Company Taxation Manual outlines that if a liquidator and a director enter into a settlement agreement that fully discharges the debt, even if only partially paid, this is deemed a loan write-off under Section 415.

In Boulton’s case, the tribunal affirmed that HMRC’s discovery assessment was valid because the remaining debt had effectively been written off, and Boulton had not reported this loan forgiveness on his tax return.

Tax Treatment of Written-Off Loans

HMRC treats written-off loans as dividends rather than salary. Under the current tax laws, the amount of the loan is the chargeable amount, and since 2016, the earlier gross-up calculation has been removed. Therefore, directors are required to report any loan forgiveness as income.

Failure to disclose such amounts can lead to penalties and back-tax assessments, as demonstrated in Boulton’s case. The tribunal’s decision reinforces the importance for directors to declare any loan forgiveness promptly.

Tax Rules on Director’s Loans

For UK company directors, any overdrawn director’s loan account can create tax traps. A company pays tax (Corporation Tax) if a loan to a participator isn’t repaid within 9 months after year-end (Section 455 CTA 2010), but the director also faces personal tax if the loan is later forgiven. The key rule is Section 415 of the Income Tax (TOIA) Act 2005:

  • Section 415 ITTOIA 2005: If a loan or advance made by a close company to a participator (e.g., a director/shareholder) is released or written off, the amount is treated as the individual’s income (a tax charge).
  • Close Company: A “close company” is typically one controlled by a small number of shareholders (often the directors themselves). Most owner-managed companies fall into this category.
  • Liquidation Context: HMRC’s manuals (CTM61560) explicitly say that once liquidation begins, a liquidator is expected to write off irrecoverable director loans. Any such write-off incurs a charge under s.415 on the director. Even without formal documents, if the company ceases pursuit of the debt, HMRC will treat it as written off.

In practice, when a company dissolves, the director may receive net asset distributions that reduce the loan. But if any balance remains after capital distributions and is then “released” (forgiven) by the liquidator, s.415 tax follows. This tax is calculated as ordinary dividend income (so taxed at dividend rates), and credit is given for basic-rate tax already deemed paid on the amount (for post-2016 tax years, it’s a simpler one-step charge).

Recent Cases

  1. VAT Payroll Fraud Case Ends in Heavy Prison Sentences 
  2. VAT Evasion Penalties in the UK: Cunningsburgh Man Who Evaded £166,000 in Tax Ordered to Pay Just £1 
  3. Tax Compliance for UK Businesses: Burton Fire Alarms Case Highlights Key Risks

Tribunal Outcome

In Douglas Boulton v HMRC [2026] (FTT number TC09846), the Tribunal upheld HMRC’s assessments. It found:

  • Accounts vs. Statement of Affairs: Boulton’s signed company accounts were reliable; the later statement showing a smaller debt was not on the company’s books and was therefore ignored.
  • Loan Release: After accepting £60,000, the liquidator clearly wrote off the remaining £91,802. The tribunal held that this amounted to a release/writing off of the debt under s.415. The absence of an “admission” in the settlement did not stop the debt being forgiven in law.
  • Tax Charge: Boulton was assessed for income tax on £91,802 under s.415. HMRC was right to issue a discovery assessment. Any tax due would be on that amount as dividend income.
  • Penalty: The tribunal also confirmed a penalty. Since Boulton failed to disclose the loan write-off on his tax return, a 15% penalty on the unpaid tax was applied (as HMRC’s lost revenue). The case highlights that not declaring such amounts can trigger significant penalties.

This decision echoes earlier cases. For example, in Gary Quillan v HMRC [2025], a liquidator had explicitly said no write-off occurred and no tax was charged. In Boulton’s case, by contrast, the liquidator’s actions were clear that the debt was off the books. HMRC’s guidance makes plain that substantive write-off – even if informal – triggers s. 415. The Tribunal agreed no special insolvency procedure was needed; a unilateral decision by the liquidator to forgo recovery sufficed for tax purposes.

What This Means for Directors

  1. Always Monitor Your DLA: If your company owes you money, keep track of any repayments or write-offs. A loan that disappears without repayment can become taxable income.
  2. Report Write-Offs: If part of a director’s loan is formally or effectively forgiven (especially in liquidation), report it on your Self Assessment. HMRC expects such income on a “miscellaneous” page if it isn’t covered elsewhere.
  3. Seek Advice: Situations involving liquidations and debt settlements are complex. Professional tax advice can prevent unpleasant surprises. If HMRC audits or disputes a loan write-off, having accounts in order and expert help can make the difference.
  4. Understand Penalties: Unreported taxable amounts can lead to discovery assessments and penalties. Late or inaccurate disclosures usually incur penalties under HMRC’s rules (often 15% or more of the tax due).

By following good practice – accurate accounting records, full disclosure, and early advice – company directors can avoid cases like Boulton’s.

How We Help Directors in UK

At Apex Accountants, we help business owners navigate complex tax issues. Our services include:

  • Tax Planning & Advice: We advise on directors’ loans, dividends and remuneration strategies to minimise unexpected tax charges.
  • Company Accounting & Reporting: We prepare and review company accounts (including director loan balances) to ensure transparency and compliance.
  • Liquidation & Insolvency Support: If your company is winding up, we guide you through the tax implications of loan write-offs, asset distributions and closure.
  • Self-Assessment & Disputes: We handle your personal tax returns carefully. If HMRC challenges a loan write-off (or any issue), we can represent you and manage any appeals or penalties.
  • Crisis Response: In cases of HMRC discovery assessments or late audits, we provide urgent help to gather evidence, clarify your position, and minimise any tax or penalties owed.

Our team stays up-to-date on cases like Douglas Boulton v HMRC. We can help you understand how these rulings affect your finances and how to comply with the rules.

Conclusion

The Douglas Boulton tribunal case is a clear reminder that any director’s loan debt that goes uncollected can count as taxable income. Writing off a loan – explicitly or effectively – triggers an income tax charge under Section 415 ITTOIA 2005. Directors should keep meticulous records and seek expert advice when dealing with loans and company closures. With proper planning and timely disclosure, you can avoid unexpected tax bills and penalties.

Pitch Deck Tax Points For Business Services Providers To Reassure SEIS Investors

Early-stage business services companies face two key challenges when raising capital under the Seed Enterprise Investment Scheme (SEIS), especially when presenting the pitch deck tax points: 

  1. Convincing investors of the commercial potential of what may be seen as a “slow growth” trade.
  2. Demonstrating that the tax incentives which reduce investor risk are credible, compliant and clearly explained.

For a successful pitch deck for investors, you must address both. Clear, well-structured tax messaging gives investors confidence that they will receive relief and that you (the founder) understand compliance. 

As the UK government statistics show, in the year 2023-24, SEIS investment rose to £242 million—up 51% on the previous year—after SEIS limits were expanded in April 2023.

Why tax messaging matters for business services providers

Business services companies often compete with higher-risk, high-growth tech firms for the attention of seed investors. Tax reliefs available via SEIS help level the playing field by offsetting risk. 

Some key data and insights:

  • According to the British Business Bank guidance, businesses under SEIS must be UK-based, trading for less than three years, have assets below £350k and have fewer than 25 employees.
  • HMRC statistics show that after the SEIS reforms in April 2023 the number of companies raising under SEIS in 2023-24 rose to 2,290 (from 1,835 in 2022-23) and the amount raised was £242 m (from £160 m) – an increase of 51%.

What this means for your pitch deck tax points:

  • Investors will expect a clear explanation of how they benefit from tax relief.
  • They will expect clear proof that your business meets the SEIS eligibility criteria.
  • You must link funding use, growth potential and exit strategy through the lens of tax relief.
  • If your business service model looks relatively low growth, the tax story becomes even more critical.

Key Tax Reliefs For Investors

When investors review your deck, they quickly scan for familiar reliefs and ask themselves “what’s my real risk”. 

Here are the reliefs you must present clearly.

Relief Details
Income Tax Relief Investors can claim 50% income tax relief on investments up to £200,000 in a tax year.
Capital Gains Tax (CGT) Exemption If the shares are held for at least three years and the company qualifies, gains on disposal are exempt from CGT.
CGT Reinvestment Relief Gains from other assets reinvested into SEIS-eligible shares may get relief on 50% of the gain (subject to conditions).
Loss Relief If the investment fails, the net loss (after income tax relief) can be offset against income tax or CGT.

Why each of these matters

  • Income tax relief halves the investor’s upfront cost, reducing downside.
  • CGT exemption gives the promise of a tax-free upside on exit — very attractive.
  • Reinvestment relief offers further flexibility and enhances appeal to serial investors.
  • Loss relief reduces real downside, which is crucial for higher-risk seed stages.

In your deck, include worked examples (e.g., “£20,000 invested → £10,000 net cost after relief”) so investors can visualise the benefit.

What To Include in Your Pitch Deck Tax Points

To reassure SEIS investors, your pitch deck should include a tax-focused section with these slides:

Eligibility & Compliance Slide

  • Confirm your company meets SEIS criteria: UK-based, <3 years trading, <25 employees, assets < £350k.
  • Show that your business is not in an excluded trade (e.g., property development, finance).
  • State whether you have or will apply for HMRC Advance Assurance.

Investor Tax Benefits Slide

  • List the tax reliefs for investors (income tax, CGT exemption, reinvestment relief, loss relief).
  • Provide a simple table or bullet list with numbers.
  • Include a worked example to show net cost, best-case and downside scenarios.

Round Structure Slide

  • Show how much you are raising, how much falls under SEIS, and if there is an EIS follow-on.
  • Clarify that SEIS shares will be first and that you will comply with the “risk-to-capital” condition.

Use of Funds Slide

  • Break down how the SEIS funds will be spent (e.g., hires, marketing, technology).
  • Confirm funds will be used within 3 years.
  • Link each spend category to growth/margin improvement.

Risk-to-Capital & Exit Slide

  • Acknowledge that the investment is high-risk.
  • Explain likely exit routes (trade sale, acquisition, dividend flow) and tax implications.
  • Show a plausible exit scenario with tax-free gain + downside scenario with loss relief.

By including these slides, you demonstrate to investors that you have thought through tax risk, compliance, and returns — not just the business model.

Research Insights & Market Outlook

For business services providers in particular, the following research-based points strengthen your tax-message credibility:

  • The recent SEIS statistics show 71% of companies raising under SEIS in 2023-24 raised over £50,000, and about 45% over £100,000; around 19% raised over £150,000.
  • Geographic spread is still heavily biased, as London and South East companies accounted for 65% of SEIS investment in 2023-24.
  • A commentary from London Business School points to high churn among UK start-ups and an environment where tax-incentivised investment schemes (like SEIS) help compensate for growth-stage funding bottlenecks.
  • The legal commentary outlines that SEIS reliefs are subject to strict compliance and can be withdrawn if conditions (such as three-year holding or qualifying trade) are breached.

Implications for your pitch deck:

  • Demonstrate you understand and will manage compliance risk.
  • If you are not based in London/South East, highlight your regional advantage or mitigation of typical locational investor bias.
  • Show that you are offering a credible funding size (e.g., >£50k) and that investors will get the same relief mechanics others are seeing.

Seven Tax-Point Checklist for Your Pitch Deck

Use this internal checklist to make sure you cover relevant tax points that reassure investors:

  1. The company meets SEIS qualifying criteria (trade, size, assets, age).
  2. Investor reliefs clearly stated (income, CGT, reinvestment, loss).
  3. Worked numerical example of investment net cost + upside/downside.
  4. Round structure detailed: SEIS amount, timeline, and EIS follow-on if any.
  5. Use of funds aligned to growth, spend categories, and the three-year rule.
  6. Risk-to-capital statement: high risk, illiquid, founders hold equity.
  7. Exit scenarios with tax treatment: best case (tax-free gains) + failure case (loss relief).

If you cover all seven, your tax story will be robust and investor-friendly.

How Our SEIS services For Business Service Providers Can Help

We support business services providers in building pitch decks and tax structuring for SEIS. Our services include:

SEIS eligibility & compliance review

  • Check trade, size, assets, and company history against HMRC rules.
  • Assess if your business is “service provider” eligible and free from exclusion risk.

Tax-point pitch deck drafting

  • Create tax slides aligned with investor expectations.
  • Develop worked examples of relief and exits to include in your deck.

Advance assurance & application support

  • Assist with the HMRC Advance Assurance application and documentation.
  • Guide you through SEIS3 form issuance and investor tax relief claims.

Round structuring & modelling

  • Define SEIS vs EIS sequencing, share structure, and valuation impact.
  • Model investor outcomes under different exit scenarios (success & failure).

Ongoing compliance and records

  • Monitor your spend, ensure you meet the three-year holding rule, and track relief.
  • Prepare for future fundraising without jeopardising early investor relief.

Conclusion

For UK business services providers raising seed capital, the tax story is not a nice-to-have—it is a key component of your investor pitch.

Well-explained SEIS reliefs reduce investor-perceived risk, enhance net returns, and position you competitively against tech-heavy peers. The statistics show more companies are using SEIS and raising meaningful sums; you must match the investor’s expectation for clarity, compliance, and tax-outcome description.

Building a successful pitch deck for investors with structured tax slides (eligibility, reliefs, round structure, use of funds, and exit treatment) demonstrates you take the investor’s tax position seriously, not just the business case. With this approach, you strengthen both credibility and fundraising potential.If you want specialist support, Apex Accountants provides SEIS services for business services providers, including pitch-deck tax wording, advance assurance applications, investor modelling, and full SEIS compliance. You can contact our team today for expert guidance on making your SEIS raise investor-ready.

Key Considerations for Corporation Tax for Business Services Providers in 2026

As we move into 2026, understanding the impact of corporation tax for business services providers is crucial. For businesses offering services such as consulting, IT services, marketing, and facility management, corporation tax rates can significantly affect financial planning and growth strategies. 

In this article, we’ll break down the key tax rates and explain how they apply to service businesses in the UK, providing insights into planning and compliance strategies.

Corporation Tax Rates For Service Businesses in 2026

In 2026, the UK’s corporation tax system will continue to operate under the following rates, effective from 1 April 2025:

These rates will remain unchanged for the financial year starting 1 April 2026. However, it’s important for business owners to be aware of how these thresholds can impact their tax liabilities and planning decisions.

Key Points to Remember:

  • Profits up to £50,000 are taxed at 19%.
  • Profits over £250,000 are taxed at 25%.
  • For profits between £50,000 and £250,000, a marginal relief applies to reduce the effective tax rate between 19% and 25%.

These thresholds and corporation tax rates for service businesses affect how providers calculate their tax liability and how they should plan for tax payments, investment, and growth strategies.

Why These Rates Matter for Business Services Providers

If you’re running a business in the service sector, whether you’re offering consulting, IT services, or facility management, these corporation tax rates directly impact your financials. Here’s why:

Taxable Profits For Business Services Providers: 

Taxable profits for business services providers are calculated by deducting allowable business expenses from your total income. This includes costs such as staff wages, office supplies, marketing expenses, and any other legitimate business costs.

Profit Growth Considerations For Businesses: 

Many service-based businesses don’t have large upfront capital investments, unlike manufacturing firms. This means that most service firms, especially small or start-up companies, are more likely to benefit from the small profit rate if their profits stay below £50,000.

Service Firms Profit Margins: 

Service firms often operate with higher margins, meaning that once you start scaling, crossing the £50,000 threshold can push your tax rate into the marginal relief zone. This is where tax planning becomes crucial to minimise the effective rate and ensure you’re making the most of the available tax reliefs.

Common Scenarios and What to Watch

Below are some typical scenarios and tax considerations for service businesses in the UK:

  1. Start-up Service Firms
    • Profits remain below £50,000: You will be taxed at the 19% small profits rate.
    • Strategy: Keep a close eye on profit levels, as even small increases could push your business into the marginal relief range.
  2. Growing Firms
    • Profits increase between £50,000 and £250,000: Marginal relief applies, which results in an effective tax rate between 19% and 25%.
    • Strategy: As your company approaches the £50,000 threshold, it’s essential to start planning for potential tax increases and explore how marginal relief can benefit you.
  3. Established Providers
    • Profits exceed £250,000: You will be taxed at the full 25% rate.
    • Strategy: At this level, aggressive tax planning may be needed to mitigate the tax burden, including investing in capital allowances or considering profit-shifting strategies.
  4. Group/Associated Companies
    • If you operate multiple service lines under separate companies or as part of a larger group, the £50,000 and £250,000 profit thresholds may be split between entities.
    • Strategy: Review your group structure and ensure you’re maximising tax efficiency across companies.
  5. Accounting-Period Mismatch
    • If your accounting period doesn’t align exactly with the tax year, different rates may apply during the year.
    • Strategy: Ensure your tax advisors are aware of any mismatches to avoid miscalculating your corporation tax.

Strategic Considerations for Service Businesses

To manage your corporation tax obligations effectively, consider the following strategies:

  • Review Your Company Structure:

If you operate multiple service lines under separate entities, it may be beneficial to keep each entity’s profits below the £50,000 threshold to benefit from the 19% tax rate.

  • Track Profit Growth Carefully:

Monitor your company’s financial performance to anticipate when your profits might exceed £50,000. The marginal relief is essential for optimising the tax rate for businesses with profits between £50,000 and £250,000.

  • Plan Expenses and Investment:

Service businesses can reduce taxable profits by investing in allowable expenses. For example, paying for employee training, upgrading IT infrastructure, or investing in energy-efficient equipment can help lower your profit before tax.

  • Keep Clear Records of Associated Companies:

If you have multiple companies in a group, it’s crucial to track their relationships and profits carefully. The thresholds for the small profits rate and main rate can be divided among associated companies.

  • Invest in Tangible Assets (if applicable):

Service companies with significant capital expenditure (e.g., buying property or expensive equipment) should explore allowances, such as capital allowances, that may reduce taxable profits.

How We Help With Corporation Tax For Business Services Providers in 2026

At Apex Accountants, we provide comprehensive services to help business services providers navigate corporation tax:

  • Tax-Planning Advice: We can guide you on how to structure your company to minimise tax and maximise growth opportunities.
  • Profit Forecasting: We help you forecast profits and identify when you may cross thresholds (£50k/£250k), ensuring proactive tax management.
  • Preparation and Filing of Tax Returns: Our team offers complete service for preparing and filing corporation tax returns (CT600) and computations.
  • Review of Associated Company Status: Our team assesses your company group structure and how the thresholds for corporation tax rates apply.
  • Ongoing Compliance Monitoring: As your business grows, we’ll monitor your tax status to keep you compliant with changing regulations.

Conclusion

Corporation tax in 2026 will continue to operate with a 19% rate for profits up to £50,000 and 25% for profits exceeding £250,000. For service businesses, understanding where your profits fall within these thresholds is essential to managing your tax efficiently. With careful tax planning and timely action, you can reduce your tax burden and optimise growth.

Let Apex Accountants assist you with tailored tax strategies that align with your business goals. Contact us today to discuss your corporation tax position.

Frequently Asked Questions (FAQs)

What is the corporation tax rate for companies with profits under £50,000?

The corporation tax rate for companies with profits under £50,000 is 19%. This rate applies to small firms or start-ups with lower profit margins, offering a more tax-friendly environment for growth.

What rate applies if profits are over £250,000?

If your company’s profits exceed £250,000, the corporation tax rate is 25%. This is the main rate applicable to larger businesses, impacting firms with significant profit generation.

How does marginal relief work?

Marginal relief applies to companies with profits between £50,000 and £250,000, gradually reducing the effective tax rate from 25% to 19%. This helps businesses avoid a sharp tax increase when their profits rise.

Does the rate change in April 2026?

There are no announced changes to corporation tax rates in April 2026. The existing rates of 19% for small profits and 25% for profits over £250,000 will remain in place.

What counts as taxable profits for a service firm?

For service businesses, taxable profits include income from services, investment income, and chargeable gains, after subtracting allowable expenses such as wages, office supplies, and other operating costs.

Are there different rules for manufacturing businesses?

While the basic corporation tax rate structure remains the same, manufacturing businesses may qualify for additional tax reliefs or allowances related to capital investment, unlike service businesses that typically have fewer capital expenses.

What if I have multiple companies in a group?

If you have multiple companies in a group, the small profits rate and main rate thresholds may be divided among them. This requires careful planning to ensure each company remains tax-efficient.

When must I file and pay corporation tax?

Corporation tax returns must be filed using the CT600 form within nine months and one day after your accounting period ends. Payment must be made by the same deadline to avoid penalties.

Can service-business firms invest to reduce taxable profits?

Yes, service firms can reduce taxable profits by making legitimate business investments and claiming allowable expenses. This includes items such as office upgrades, staff training, and equipment purchases that support business operations.

What are the risks of overlooking the thresholds?

Overlooking profit thresholds can result in paying more tax than necessary or missing out on marginal relief. It may also lead to penalties for inaccurate filings or misreporting profit levels, which could affect cash flow.

2026 Strategic Growth Strategies for Business Services Providers in UK

As we look towards 2026, business services firms in the UK are entering a period of transformation. With market conditions continuing to evolve, it’s crucial to adopt strategic growth strategies for business services providers that leverage their strengths, adapt to challenges, and position them for long-term success. 

In this article, we’ll explore the strategies that can help business services firms thrive in the coming years, focusing on sustainable growth, operational excellence, and the adoption of new technologies.

What Clients and Businesses Are Concerned About

Business services providers and their clients are facing several key concerns as they move into 2026:

  • Revenue Growth Amid Cost Pressures: With rising operational costs and margin squeeze, firms need to find ways to maintain or grow revenue.
  • Technology Adoption: Firms want to embrace new technologies but worry about potential disruptions to service delivery.
  • Talent Acquisition: Finding the right people to deliver services effectively is a constant challenge.
  • Tax and Compliance Changes: Keeping up with shifting regulations and tax changes remains a top priority for firms to stay compliant and avoid penalties.
  • Financial Support: Businesses are seeking financial solutions and advisory services to guide them through uncertain times.

Addressing these concerns will be crucial for business services firms looking to stay competitive and achieve growth.

Market Insights for 2026

Looking ahead, there are several trends that will influence business services firms in the UK:

  • Cautious Optimism: UK firms are generally optimistic about 2026, with growth expected to be driven by new business, export opportunities, and innovation.
  • Technology Adoption: With the rise of digital transformation, AI, and automation, firms are increasingly adopting technology to enhance efficiency and client service.
  • Global Expansion: UK businesses are searching for opportunities beyond domestic borders, with international expansion on the agenda.
  • Regulatory Changes: New tax, data protection, and AI regulations are expected to impact businesses in the coming years, making compliance a key focus.

These insights highlight the importance of adopting a forward-thinking strategy that embraces change while ensuring operational efficiency of business services firms.

Key Growth Strategies For Business Services Providers 

Here are actionable strategies that can help business services firms position themselves for growth in 2026:

1. Define Your Growth Agenda

Set clear targets for revenue, margins, and service offerings. It’s important to focus on high-value clients rather than volume-based growth. By targeting the right clients and services, firms can build a more sustainable business model that can weather market fluctuations.

2. Strengthen Service Delivery and Operational Capability

To drive growth, it’s essential to continuously improve service delivery. This can be done by:

  • Mapping out key processes to identify inefficiencies and areas for improvement.
  • Leveraging data and analytics to track performance and client satisfaction.
  • Adopting automation to reduce manual tasks and improve accuracy.

Working on the operational efficiency of business services firms can reduce costs and enhance service quality, which will drive client satisfaction and loyalty.

3. Embrace Technology and Digital Enablement

2026 will see technology playing a central role in driving growth. To stay competitive, firms should:

  • Invest in technology to enhance service delivery and improve client experiences.
  • Implement AI-driven tools to streamline processes, improve decision-making, and stay ahead of regulatory compliance.
  • Use cloud-based platforms and automation to improve efficiency and scalability.

By embracing technology, business services firms can position themselves as innovative leaders in the market.

4. Develop New Services and Markets

To stay competitive, firms should look beyond their existing service offerings and explore new opportunities. This could involve:

  • Identifying new sectors or geographic markets to expand into.
  • Offering new service models such as subscription-based services or value-added advisory.
  • Differentiating services to stand out in a crowded market.

Developing new services allows firms to diversify their revenue streams and remain adaptable to market changes.

5. Focus on Client-Centric Growth

To build long-term growth, business services firms must focus on deepening client relationships. This can be achieved by:

  • Actively seeking client feedback to understand their evolving needs.
  • Offering tailored solutions that address specific client pain points.
  • Providing value-added services, such as strategic advisory, that go beyond basic service offerings.

By putting clients at the centre of their strategy, firms can build stronger, more loyal relationships, which will contribute to sustainable growth.

6. Manage Risk and Compliance

Risk management is an essential part of any growth strategy. Firms should:

  • Stay ahead of regulatory changes and ensure they are fully compliant with tax, data, and industry-specific regulations.
  • Monitor external risks, such as economic shifts or changes in government policy, to adjust strategies accordingly.
  • Implement strong internal controls to mitigate financial and operational risks.

By managing risk effectively, firms can avoid potential setbacks and continue to focus on growth.

How Our Expertly Crafted Growth Plan For Service Businesses Can Help You

At Apex Accountants, we understand the unique challenges faced by service businesses. Our expertly crafted growth plan is designed to address the specific needs of your business, ensuring you can scale effectively and manage the complexities of financial planning, compliance, and operational efficiency. 

Here’s how we can help:

  • Accounting and Bookkeeping: We provide accurate and timely financial management, allowing you to focus on growing your business.
  • Tax Advisory Services: Our experts can help you navigate complex tax regulations and provide strategic tax planning advice.
  • Financial Support and Cash Flow Forecasting: We help businesses plan for future growth by providing detailed financial forecasts and cash flow management.
  • Business Process Review: We offer consulting services to help you streamline operations, reduce inefficiencies, and improve profitability.
  • Technology Advisory: We assist firms in adopting the right technologies, from automation tools to AI solutions, to improve service delivery and operational efficiency.
  • International Expansion Support: Our team can guide you through the process of expanding into new markets, ensuring compliance and maximising opportunities.

Why Choose Apex Accountants

At Apex Accountants, we understand the unique challenges faced by business services firms. Our team brings over 20 years of experience in helping firms navigate the complexities of tax, accounting, and business strategy. 

We offer tailored solutions that not only meet your immediate needs but also help you draft a successful growth plan for service businesses. With our support, you can focus on growing your business while we take care of the financial and compliance aspects.

Conclusion

As business services firms look ahead to 2026, growth is possible with the right strategies in place. By focusing on service delivery, embracing technology, exploring new markets, and staying client-focused, firms can position themselves for success in a rapidly changing landscape. The time to act is now, and with the right support, your firm can thrive in 2026 and beyond. If you’re ready to take the next step, get in touch with Apex Accountants today to discuss how we can help you achieve your growth goals.

Book a Free Consultation