How the UK Exit Tax Proposal Could Introduce a 20% Charge for Individuals and Businesses

The proposed UK exit tax is a one-off charge, reported at around 20%, on unrealised gains in UK business and investment assets when an individual ceases to be UK tax resident. It remained a proposal only as of September 2026 — not yet law — and some reports suggest it may have been scaled back or not taken forward, though it has not been definitively ruled out in all forms. Anyone considering leaving the UK should therefore monitor Budget statements and official guidance before acting.

Chancellor Rachel Reeves has reportedly been considering a 20% “exit tax” that would apply to high-net-worth individuals (HNWIs) leaving the UK. This UK exit tax proposal would target unrealised gains on business and investment assets acquired while an individual was a UK resident. The exit tax is being discussed as part of the 2025 Budget to help cover the UK’s growing fiscal deficit.

This exit tax would impose a capital gains tax (CGT) on unrealised gains for individuals who have been UK residents and then decide to emigrate or relocate their tax residence. Such a move aims to prevent the avoidance of UK tax when wealthy individuals move their assets abroad without paying tax on the value appreciation that occurred during their time as UK residents.

What is an Exit Tax?

An exit tax is a tax that countries impose on individuals or businesses when they leave the country and cease to be tax residents. Specifically, it taxes the unrealised gains (the increase in the value of assets, such as shares, businesses, or real estate) that have occurred during the time the individual was a resident.

Exit taxes are designed to stop people from leaving a country and selling assets in a way that avoids leaving UK capital gains tax liabilities on gains that built up while they were UK residents.

Why Might the UK Exit Tax Proposal Introduce?

The UK is facing an economic challenge, and the government needs new ways to generate revenue. Here are some reasons why the 20% exit tax UK is being considered:

1. Raise Revenue

Supporters believe the exit tax could raise around £2 billion for the Treasury by taxing unrealised gains when individuals leave the country. This would help protect the UK’s tax base and prevent individuals from avoiding capital gains tax by emigrating.

  • Wealthy individuals can avoid UK CGT by simply moving abroad and holding onto appreciating assets without selling them.

2. Align with International Norms

Other countries, such as France, Canada, and the United States, already impose exit taxes on individuals when they leave. Advocates for the UK exit tax suggest that the UK should adopt a similar approach to maintain consistency with global standards and prevent wealthy individuals from leaving without paying their fair share of tax. 

3. Prevent Tax Avoidance

The exit tax is considered a tool to curb tax avoidance by wealthy individuals who may otherwise leave the country and avoid paying tax on large capital gains. By taxing unrealised gains, the UK government can ensure that these individuals pay tax on their assets while they are residents.

Why is the 20% Exit Tax UK Controversial?

While the proposal aims to raise revenue, critics argue that it could have significant negative consequences. Here are some key concerns:

1. Possible Exodus of Wealth

Business leaders, investors, and tax advisers have warned that even the discussion of an exit tax could encourage wealthy individuals to leave the UK earlier than planned. The concern is that if the tax is introduced, many individuals might accelerate their exit plans to avoid being taxed. This could lead to a reduction in investments in the UK.

2. Practical Challenges in Valuing Assets

One of the major challenges of implementing an exit tax is how to fairly value assets, especially privately held businesses or illiquid investments. Determining the market value of these assets when an individual exits the UK can be complex and subjective. There are concerns that such an approach could create administrative burdens and disputes.

3. Impact on the UK’s Competitiveness

Imposing an additional tax burden on high-net-worth individuals may discourage entrepreneurs from investing in the UK or starting businesses here. The UK already has high corporate tax rates and the highest personal tax burden in decades. An exit tax could send the signal that the UK is no longer a hospitable place for wealth creators.

What the proposal would mean in practice

If the reported 20% exit charge were introduced, it would work as a deemed disposal when an individual ceases to be UK tax resident: unrealised gains on relevant business and investment assets would be treated as if sold at market value, triggering a Capital Gains Tax–style charge. Early reporting suggested the rate would be around 20% on those gains, with the possibility of deferring payment (for example, via instalments or until the assets are actually sold), rather than requiring the full amount immediately.

Worked example: 

A UK‑resident business owner holds shares in their trading company with a base cost of £100,000 and a current market value of £500,000, giving £400,000 of unrealised gains. On ceasing UK residence under the proposal, those gains could be taxed at about 20%, implying a potential exit charge of around £80,000. Depending on the final rules, the owner might be able to defer payment – for instance, spreading it over several annual instalments or paying only when the shares are eventually disposed of – subject to interest and anti‑avoidance conditions.

What Will Be Taxed?

The exit tax would primarily target assets held by high-net-worth individuals that have appreciated in value during their time as UK residents. These could include:

  • Business assets (such as shares in private companies)
  • Real estate (if applicable)
  • Investment assets (stocks, bonds, etc.)

The tax would likely apply when the individual departs the UK, making leaving UK capital gains tax planning particularly important. Their assets could be deemed to have been sold, with tax charged on capital gains accrued during their UK residency.

How Can Apex Accountants Help?

At Apex Accountants, we specialise in helping individuals and businesses navigate complex tax changes and plans. Our services include:

  • Tax Planning – We assess your current tax position, reviewing your assets and potential exposure to an exit tax.
  • Residency & Structuring Advice – We guide you on residency status, structuring your assets in a tax-efficient manner.
  • Cross-Border Tax Advice – We offer advice on managing your global tax liabilities when relocating or moving assets across jurisdictions.
  • Budget Monitoring – We stay on top of legislative changes, advising on the best timing for asset disposals or relocation to minimise tax exposure.

Conclusion

The proposed 20% exit tax is still under consideration, but it marks a significant change in how the UK may treat wealthy individuals who decide to leave the country. The tax aims to address tax avoidance and boost revenue, but it may also lead to unintended consequences such as driving capital away from the UK and discouraging investment. As the UK’s tax system evolves, it is crucial for high-net-worth individuals and businesses to seek professional tax planning and inheritance tax planning services and advice to plan ahead.

FAQs About UK Exit Tax Proposal

1. When Would the Exit Tax Take Effect?

The exit tax is now understood to be a reported proposal only, initially discussed around the November 2025 Budget but not enacted, with later reporting suggesting it may have been scaled back or not taken forward for individuals. If introduced in future, any start date would depend on the legislative process and government decisions, typically aligning with a specified date in the Budget or the start of a tax year.

2. What Assets Are Exempt From UK Exit Tax?

Typically, primary homes and pensions are exempt from UK exit taxes in many countries. While the UK may follow this pattern, the specifics remain uncertain until the final rules are released.

3. How Can I Prepare for the Exit Tax?

To prepare, review assets with unrealised gains, consider restructuring through trusts or offshore entities, and seek advice on residency status and cross-border tax liabilities to mitigate exposure.

4. Which Countries Have an Exit Tax?

Countries such as France, Canada, the US, and Australia have exit tax regimes that tax unrealised gains when individuals leave, preventing capital gains avoidance by emigrants.

5. How Is an Exit Tax Calculated?

The exit tax would likely calculate gains on the market value of assets at departure, taxing those gains accrued during UK residency. Deferrals may apply under certain conditions.

6. Are There Any Deferrals or Exemptions?

Some countries allow deferrals or exemptions for certain assets like primary homes or pensions. While the UK may follow a similar approach, this is not confirmed yet.
UK Wealth Tax: Would Business Owners and High Earners Pay?

Owning a valuable business does not necessarily mean having substantial cash available personally. Equally, earning a high salary does not automatically mean holding significant wealth after debts. A UK Wealth Tax based on net assets would assess these situations differently. For directors, investors and property owners, the starting point is to separate existing tax liabilities from hypothetical future charges.

Key Points

  • The UK does not currently have a general annual tax on an individual’s total net wealth.
  • Existing taxes apply separately to income, capital gains, estates and particular transactions or assets.
  • A high salary alone would not determine liability under a tax based on net wealth.
  • The proposed High Value Council Tax Surcharge concerns property in England; its final legal design remains subject to legislation.

Is There a UK Wealth Tax in Force?

The UK does not currently operate a general annual tax on total individual net wealth. There is therefore no general wealth-tax return or payment deadline for individuals, and no universal wealth-tax threshold. Existing taxes can nevertheless apply to particular assets and transactions.

The House of Commons Library explains the distinction between a tax on wealth holdings and existing asset taxes. Assets can already generate liabilities through income, gains, transfers and property transactions.

This distinction matters when assessing a UK wealth tax proposal. A suggested rate or exemption does not create a payment obligation, and a change to an existing tax does not necessarily introduce a comprehensive wealth tax.

What Would a Tax on Net Wealth Measure?

A net wealth tax would measure assets within its scope after permitted debt deductions, using the valuation rules and assessment date specified by the legislation.

Three different figures must be kept separate:

  • Income: money earned or received during a period.
  • Capital gain: a gain calculated under tax rules on a disposal or deemed disposal.
  • Net wealth: the value of included assets after allowable liabilities.

CGT generally concerns gains on a disposal or deemed disposal, rather than the asset’s full value. A hypothetical wealth tax could assess ownership without a sale.

The tax base would therefore be critical. Homes, pensions, private-company shares and overseas assets could be included or excluded under different models. None should be assumed taxable or exempt before the relevant rules exist.

Would Business Owners and High Earners Necessarily Pay?

No. Under a net wealth model, exposure would depend on included assets, deductible debts and the threshold. Salary and business turnover would not, by themselves, answer the question.

Consider a hypothetical comparison:

Financial PositionRelevant Question Under a Net Wealth Model
High salary, limited accumulated assetsDoes net wealth exceed the threshold?
Valuable private-company shareholdingHow is the particular shareholding valued?
Property portfolio with substantial mortgagesWhich debts can be deducted?
Valuable home, modest income and little cashIs the property included, and can payment be deferred?

These are design questions, not current UK wealth tax rules.

The company’s value and the value of a particular shareholding are distinct. This illustrates a valuation issue; it neither establishes a future wealth-tax rule nor guarantees a minority discount.

Why Would Valuation and Cash Flow Matter for Business Owners?

Valuation determines the assessed amount; liquidity determines whether the owner has accessible money to pay it. A hypothetical charge could be affordable relative to asset value but difficult to fund from annual personal cash flow.

An adviser reviewing a proposed model would need to examine:

  • The valuation date and evidence supporting the share value.
  • Rights attached to different share classes.
  • Whether the owner can sell shares or receive distributions.
  • How company borrowing is reflected in the valuation.
  • Whether instalments or deferral are available.

For an illustrative personal balance sheet, company debt already reflected in a share valuation should not then be deducted again as though it were the shareholder’s personal borrowing. Otherwise, the same liability would reduce the calculation twice.

This is a general valuation principle, not a confirmed deduction rule for a future tax.

How Would a Hypothetical 2% Charge Be Calculated?

If a model charged 2% only on taxable net wealth exceeding £10 million, the calculation would apply to the excess. It would not apply to every pound of wealth.

Illustrative example only: assume all listed assets are included, the share valuation is accepted, and the personal debt is fully deductible.

CalculationAmount
Private-company shareholding£9,200,000
Property£2,400,000
Savings and investments£900,000
Less permitted personal debt(£500,000)
Taxable net wealth£12,000,000
Less hypothetical threshold(£10,000,000)
Amount subject to the charge£2,000,000
Hypothetical charge at 2%£40,000

The example assumes a marginal threshold, charging only the excess. A different design might charge the full amount once a threshold is crossed. Neither approach is a confirmed UK rule.

It also says nothing about frequency. A one-off assessment payable over several years differs from an annual tax that recalculates liability each year.

How Does Current Wealth Taxation Apply in 2026/27?

Current wealth taxation consists of separate taxes with different triggers and reliefs. A disposal, dividend and inheritance must each be assessed under their own rules.

Tax or AllowancePosition for 2026/27
Capital Gains TaxFor most individual gains, 18% within the unused basic-rate band and 24% above it, subject to specific regimes and reliefs
CGT Annual Exempt Amount£3,000 for eligible individuals
Business Asset Disposal Relief18% on qualifying disposals from 6 April 2026, subject to eligibility and the remaining £1 million lifetime limit on qualifying gains
Dividend Income Tax10.75%, 35.75% or 39.35%, depending on the applicable band
Dividend Allowance£500
Inheritance TaxStandard rate on death 40%, with a basic nil-rate band of £325,000 and potentially other allowances, exemptions or reliefs

The CGT calculation takes taxable income into account when determining how much basic-rate band remains. Business Asset Disposal Relief is a separate relief regime, even though its current rate equals the main lower CGT rate.

A qualifying estate may also receive a £175,000 residence nil-rate band, subject to the value passing and other conditions. It generally requires a qualifying home to pass to direct descendants. The allowance tapers by £1 for every £2 of estate value above £2 million.

The 40% rate is the standard death rate, not a blanket rate for lifetime transfers. Non-exempt outright gifts to individuals are generally potentially exempt transfers, normally becoming exempt after seven years, subject to exceptions such as retained benefits.

Worked CGT example: assume an £80,000 chargeable investment gain, no allowable losses, no other gains, no special relief and no unused basic-rate band. With the full £3,000 annual exemption, £77,000 is taxable at 24%: £18,480.

Actual liability depends on residence, taxable income, available losses, including carried-forward losses, and the asset concerned.

Is the Proposed Property Surcharge a General Wealth Tax?

No. The proposed High Value Council Tax Surcharge targets qualifying residential property, rather than combined net assets.

The government has proposed introducing it in England only, from April 2028, for properties worth £2 million or more. The consultation sets out these proposed charges. The detailed rules remain subject to legislation and final decisions.

Property Value Band as PublishedProposed Annual Surcharge
£2 million to £2.5 million£2,500
£2.5 million to £3.5 million£3,500
£3.5 million to £5 million£5,000
Over £5 million£7,500

The consultation closed on 14 July 2026. It proposes owner liability and deferral for certain qualifying main-home owners, with interest and security over the property. These arrangements remain provisional. Deferral would delay payment, not cancel the charge.

The bands above reproduce the published descriptions. Exact boundary treatment and individual eligibility should be checked against the final rules.

How Much Would a Wealth Tax Raise in the UK?

There is no single dependable revenue figure for an unspecified wealth tax for the UK. An estimate needs a defined tax base, threshold, rate and assessment period.

The Commons Library briefing records that revenue from a potential one-off tax would depend heavily on its final design.

A useful assessment should distinguish:

  • Gross liability from revenue actually collected.
  • Annual receipts from a total collected over several years.
  • Estimates before and after administrative costs.
  • Calculations with and without assumed behavioural changes.

A modelled yield is not a guaranteed outcome. It also cannot establish what a particular owner would pay without a separate calculation.

What Should You Review Before Changing Your Arrangements?

Review current tax exposure, ownership and cash needs before making transfers in response to a hypothetical future charge. The existing consequences of a transaction are more concrete than an assumed future saving.

As general planning guidance, prepare:

  1. An asset schedule showing legal ownership and ownership percentages.
  2. Separate records of personal and company liabilities.
  3. Acquisition costs and documents supporting material valuations.
  4. A cash-flow forecast covering existing liabilities and intended transactions.
  5. A review of planned gifts, disposals and succession arrangements.

Gifts generally use market value for CGT, but no-gain/no-loss rules or reliefs may apply. For example, qualifying transfers between spouses or civil partners normally do not trigger an immediate CGT charge. The IHT gift rules require a separate assessment.

FAQs About Wealth Taxation in the UK

What Net Worth Is Considered Wealthy in the UK?

There is no single figure that determines liability across the UK tax system. A threshold used in statistics or by a financial provider is not a universal tax allowance. Each relevant tax must be assessed separately.

Would a Main Home Be Exempt From a Future Wealth Tax?

An exemption cannot be assumed. A future framework would need to specify whether homes are included and how ownership shares and mortgages are treated. Relief available under another tax would not automatically apply.

Would Putting Assets Into a Company Prevent a Wealth Tax Charge?

Not necessarily. A hypothetical model including private-company shares could still assess the owner’s shareholding. Transferring an asset may also create consequences under existing CGT rules, so incorporation should not be treated as an automatic solution.

Would Business Asset Disposal Relief Protect My Business From a Wealth Tax?

No such protection can be assumed. Business Asset Disposal Relief concerns qualifying capital gains on disposals, with eligibility conditions and limits. It does not establish an exemption from an unspecified future tax on ownership.

Would Giving Assets Away Remove All Tax Exposure Immediately?

No. A gift can create CGT consequences, while its inheritance tax treatment depends on the circumstances. For example, retaining a benefit from a gifted asset can prevent it from leaving the donor’s estate for IHT purposes.

How Can Apex Accountants Help With Your Existing Tax Liabilities?

Although the UK does not currently have a general annual tax on individual net wealth, existing taxes can affect your income, investments, business interests and estate. Apex Accountants can help you understand these liabilities and assess your options under current rules.

Our support includes:

  • Capital Gains Tax: Reviewing planned disposals, allowable costs, losses and eligibility for reliefs, including Business Asset Disposal Relief.
  • Personal and Dividend Tax: Assessing how salary, dividends and other income affect your personal tax position.
  • Inheritance Tax and Estate Planning: Reviewing gifts, available allowances and business succession arrangements.
  • Cash-Flow Planning: Estimating liabilities and payment timings before a sale, gift or ownership change.

Through our personal tax services and estate planning services, we provide advice based on your circumstances and confirmed rules. Book a free consultation to discuss your existing tax exposure and planned transactions.

A Complete Guide to UK Airbnb Tax: Rules, Reliefs and Rates for 2026/27

A host can receive regular Airbnb bookings and still be unsure whether HMRC sees the income as a small side activity or a taxable property business. The answer depends on how much you receive, whether you are letting your main home or a separate property, and which expenses or reliefs you claim.

For 2026/27, UK Airbnb tax is not a separate tax regime. Most individual hosts are taxed under the normal property income rules, while qualifying hosts using their main home may benefit from the Rent a Room Scheme. The former Furnished Holiday Lettings tax regime no longer applies.

Quick Answer

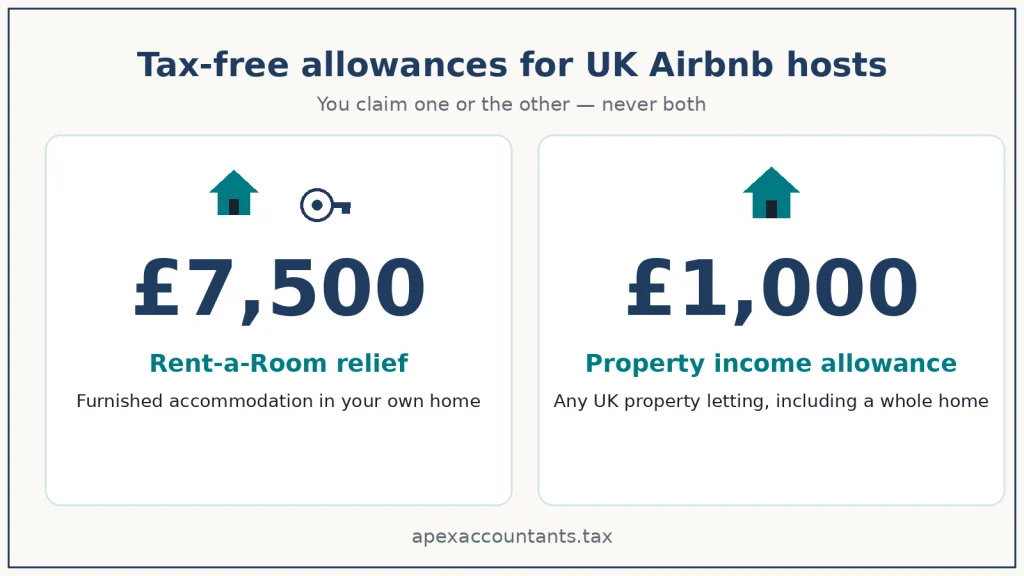
  • Individuals can generally receive up to £1,000 of qualifying gross property income under the property allowance before tax reporting is normally required.
  • The Rent a Room Scheme can provide up to £7,500 tax-free, reduced to £3,750 where the income is shared.
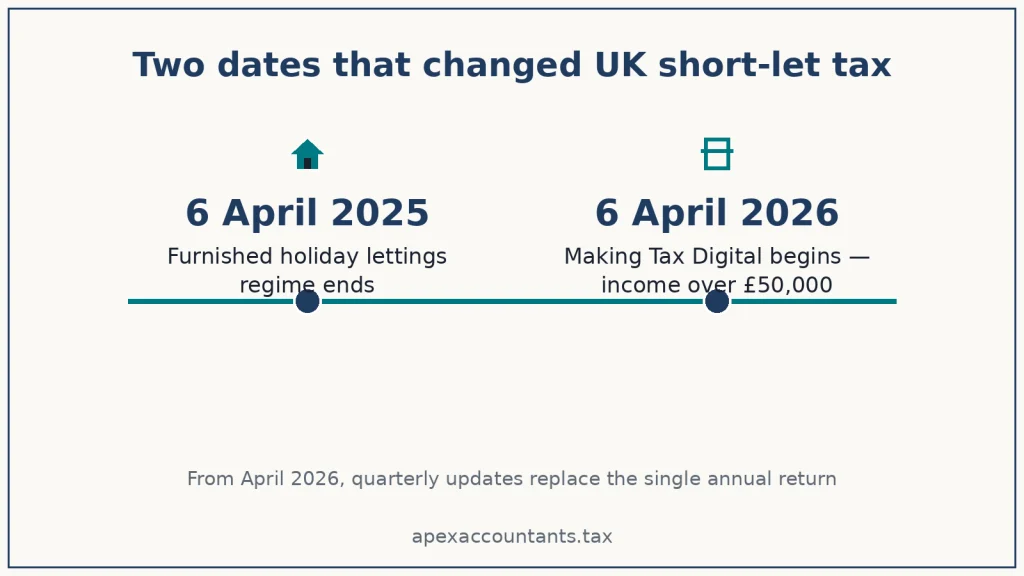
  • The special Furnished Holiday Lettings regime ended on 6 April 2025 for Income Tax and Capital Gains Tax.
  • Airbnb and other qualifying platforms can report host information to HMRC. The widely quoted 30 transactions, or €2,000 threshold relates to sales of goods, not property rentals.
  • Making Tax Digital for Income Tax became mandatory from 6 April 2026 for qualifying sole traders and landlords whose 2024/25 qualifying income exceeded £50,000.

Do You Have to Pay UK Airbnb Tax on Hosting Income?

Airbnb income is generally taxable when your receipts exceed the relief or allowance available to you. For most hosts letting an investment property, the starting point is the normal property income rules rather than a special Airbnb tax rate.

The amount subject to income tax will usually depend on your taxable property profit after allowable deductions. However, an individual with relatively small receipts may instead be able to use the £1,000 property allowance.

The position is different where you provide furnished accommodation in your only or main residence. In that situation, the Rent a Room Scheme may provide a substantially larger exemption.

This distinction matters because the two reliefs cannot simply be stacked together.

How much can you earn from Airbnb before paying tax?

You can earn up to £1,000 of gross property income tax-free each tax year, or up to £7,500 if the letting qualifies for Rent-a-Room relief. These are two different allowances with different conditions, and choosing between them matters — you claim one or the other for the same income, never both.

Property income allowanceRent-a-Room relief
Annual tax-free limit£1,000 of gross income£7,500 of gross income (£3,750 if you share the income with someone else)
Which lettings qualifyAny UK property income, including a whole flat or house let on AirbnbFurnished accommodation in your own home, while you live there — a lodger-style let
What it replacesActual expense deductions, if you claim itActual expense deductions for the letting, if you claim it
Best forHosts with low income and few expensesHosts letting a room (or their whole home occasionally) with income under £7,500

The practical difference is sharp. A host letting an entire second flat has no choice — the £1,000 allowance is the only option. A host letting a spare bedroom in the house they live in, or letting the whole house for a few weeks while on holiday, can usually use Rent-a-Room’s higher £7,500 limit. Above £7,500, you can still claim Rent-a-Room and pay tax only on the excess, which is often better than deducting actual expenses if those are small.

Remember the furnished-room requirement: Rent-a-Room does not apply to unfurnished space, and it only works for lettings in a property that is your home during the tax year.

Which Airbnb Tax UK Exemptions and Allowances Can Hosts Claim?

The main relief depends on what you are actually letting. A host renting furnished accommodation in their main home should consider Rent a Room, while a host letting a separate property may need to compare the £1,000 property allowance with actual deductible costs.

The £1,000 Property Allowance

Individuals can generally receive up to £1,000 of gross qualifying property income each tax year without needing to tell HMRC about that income. Joint owners can each potentially have their own £1,000 allowance against their share of qualifying receipts.

If gross receipts exceed £1,000, you may be able to deduct the £1,000 allowance instead of claiming actual expenses.

That choice requires care. You cannot claim the property allowance while also deducting actual expenses for the same property business, and HMRC prevents use of the allowance where you claim the residential property finance cost tax reduction.

The £7,500 Rent a Room Scheme

If you let furnished accommodation in your only or main home, Rent a Room can exempt gross receipts of up to £7,500 a year. Where another person also receives income from letting accommodation in the same residence, the limit is normally £3,750 each.

If receipts exceed the limit, you can generally choose between:

  • paying tax on your actual rental profit after eligible expenses; or
  • using Rent a Room’s alternative basis, under which the excess above the applicable exemption limit becomes taxable.

HMRC confirms that Rent a Room may apply to furnished accommodation in a person’s main residence and can also apply in relevant guest house or bed-and-breakfast circumstances.

How Is Airbnb Income Tax UK Calculated in 2026/27?

For an individual host in England, Wales or Northern Ireland, taxable Airbnb property profit is generally added to other taxable income and charged at the person’s marginal Income Tax rate. For 2026/27, the main rates remain 20%, 40% and 45%, with a standard Personal Allowance of £12,570 where it is fully available. Scottish taxpayers are subject to separate Scottish Income Tax bands.

2026/27 BandTaxable IncomeMain Rate
Personal AllowanceUp to £12,5700%
Basic rate£12,571 to £50,27020%
Higher rate£50,271 to £125,14040%
Additional rateAbove £125,14045%

A Simplified Airbnb Tax Example

Assume an English higher-rate taxpayer has:

  • Airbnb receipts of £24,000
  • ordinary allowable running costs of £6,000
  • mortgage interest of £8,000

Their taxable property profit before the finance-cost tax reduction is £18,000, because an individual residential landlord cannot deduct mortgage interest directly when calculating rental profit.

If all £18,000 falls within the 40% band, the initial tax is £7,200.

Assuming the entire £8,000 finance cost qualifies for relief and no restriction in HMRC’s calculation applies, the current 20% tax reduction is £1,600, reducing the illustrative income tax to £5,600. HMRC calculates the finance cost reduction by reference to the lowest of qualifying finance costs, property business profits and adjusted total income, so an actual calculation may differ.

This is one reason Airbnb hosts with borrowing costs should not estimate tax simply by deducting mortgage interest from cash profit.

What Expenses Can Airbnb Hosts Deduct?

Hosts using the actual-expenses method can generally deduct revenue costs incurred in running the property business, provided the costs satisfy the normal property-income rules. HMRC lists a range of deductible day-to-day expenses.

These can include:

  • letting or management fees
  • accountancy fees
  • buildings and contents insurance
  • repairs and maintenance, but not improvements
  • gas, electricity, water and other utilities paid by the landlord
  • Council Tax where borne by the landlord
  • cleaning and gardening
  • advertising and other direct letting costs
  • rent, ground rent and service charges where applicable

Costs that improve the property rather than merely repair it are normally capital expenditure rather than an immediate deduction against rental profit.

For furniture and household equipment, Replacement of Domestic Items Relief may be available when an existing qualifying item is replaced. The initial cost of furnishing a property does not automatically qualify under this replacement relief.

Airbnb’s own host service charge is not an additional UK tax. Where a platform fee is incurred directly for the letting business, its tax treatment should be considered under the normal rules for business-related letting costs.

What Changed When the Furnished Holiday Lettings Tax Regime Ended?

The special Furnished Holiday Lettings regime ceased for Income Tax and Capital Gains Tax from 6 April 2025 and from 1 April 2025 for Corporation Tax purposes. Former qualifying FHLs therefore generally fall into the ordinary property tax regime.

For Airbnb and other short-term accommodation owners, the abolition removed several advantages.

AreaFormer FHL TreatmentPosition After Abolition
Mortgage finance costs for individualsFinance-cost restriction did not applyResidential property finance-cost restriction generally applies
Capital allowancesAvailable on qualifying plant and machineryGenerally unavailable for new expenditure on items within the dwelling; replacement relief may apply
CGT business reliefsCertain trading-style CGT reliefs potentially availableSpecial FHL access removed
Pension reliefProfits could count as relevant UK earningsFormer FHL property income no longer receives this special treatment

HMRC confirms these changes in its updated Property Income Manual.

There are transitional rules for matters such as existing capital allowance pools and pre-abolition transactions, so hosts with a property that qualified as an FHL before April 2025 should not assume all historic relief simply disappeared retrospectively.

Does Airbnb Report UK Hosts to HMRC?

Digital platform reporting rules require qualifying platforms to collect and report information about sellers, including people letting short-term accommodation. The UK rules took effect from 1 January 2024, with the first reporting due from January 2025.

This is where one of the biggest pieces of misinformation around HMRC Airbnb tax UK arises.

The often-quoted exclusion for fewer than 30 transactions and no more than €2,000, approximately £1,700, applies to sales of goods. It is not a £1,700 Airbnb rental-income exemption. Property rentals are identified as a reportable platform activity.

Platform reporting also does not create a new tax. Whether tax is actually due still depends on the existing income tax rules, allowances, expenses and reliefs that apply to the host.

Hosts should therefore reconcile:

  • Airbnb booking and payout records
  • platform fees
  • cancellations and refunds
  • property expenses
  • amounts already reported to HMRC

Where HMRC receives platform information that does not match a tax return, the discrepancy can create an obvious compliance risk.

When Does Making Tax Digital Apply to Airbnb Hosts?

Making Tax Digital for Income Tax can apply to individual landlords with Airbnb property income when their combined qualifying self-employment and property income exceeds the relevant threshold.

The first mandatory phase began on 6 April 2026.

Tax Return Used to Test IncomeQualifying IncomeMTD Start Date
2024/25More than £50,0006 April 2026
2025/26More than £30,0006 April 2027
2026/27More than £20,0006 April 2028

Those brought into MTD must maintain qualifying digital records and use compatible software. For the first 2026/27 MTD year, HMRC lists quarterly update deadlines of 7 August 2026, 7 November 2026, 7 February 2027 and 7 May 2027, followed by the 2026/27 tax return deadline of 31 January 2028.

Hosts approaching the thresholds can read Apex’s Making Tax Digital for Income Tax 2026 guide before changing their bookkeeping process.

Do Airbnb Hosts Have to Register for VAT?

Holiday accommodation is generally a standard-rated supply for VAT purposes. However, an individual host does not automatically have to register for VAT simply because they list a property on Airbnb.

The compulsory VAT registration threshold is currently £90,000 of taxable turnover, measured using the relevant rolling 12-month or forward-looking registration tests. The threshold concerns the taxable turnover of the VAT person, so other taxable business activities may also need to be considered rather than looking at the Airbnb listing in isolation.

Hosts close to £90,000 should review their VAT position before crossing the threshold, particularly because adding VAT after prices and bookings have already been set can affect margins.

What Tax Applies When You Sell an Airbnb Property?

An individual selling an Airbnb investment property may face capital gains tax on any taxable gain that is not covered by available reliefs or exemptions.

For disposals from 6 April 2026, the main individual CGT rates are 18% and 24%, depending on the taxpayer’s circumstances. The individual annual exempt amount for 2026/27 is £3,000.

If CGT is due on a UK residential property disposal, it normally has to be reported and paid within 60 days of completion. A taxpayer already within Self Assessment may also need to include the disposal in the relevant tax return.

Private Residence Relief may change the calculation where the property has genuinely been the owner’s home. Former FHL owners should also remember that the special FHL treatment giving access to certain business CGT reliefs ended from 6 April 2025.

Our Capital Gains Tax services can help where a short-term rental property is being sold, transferred or restructured.

How Can You Reduce Airbnb Tax Legally in the UK?

Searches for “how to avoid Airbnb tax UK” often describe what is really a tax-planning question. The lawful objective is to claim the reliefs and deductions Parliament allows while reporting all taxable income correctly.

Depending on the facts, sensible planning can include:

  • comparing the £1,000 property allowance with actual deductible expenditure
  • checking whether Rent a Room relief applies to accommodation in your main home
  • keeping evidence for all allowable expenses
  • claiming Replacement of Domestic Items Relief where the statutory conditions are met
  • carrying forward eligible unused residential finance costs where HMRC’s tax-reducer calculation restricts relief
  • reviewing ownership and profit allocation before, rather than after, income arises
  • forecasting VAT and MTD thresholds before they are crossed

For spouses and civil partners, another post-FHL change deserves attention. Income from jointly held property is generally treated as arising equally between them unless the underlying beneficial ownership is unequal and the conditions for notifying HMRC, including Form 17, are satisfied. HMRC says the declaration must be submitted within 60 days.

Changing ownership purely for tax purposes can have wider tax, mortgage, legal and succession consequences. It should therefore be modelled before any transfer is made.

What Changes to Airbnb Tax From 6 April 2027?

A confirmed change takes effect from 6 April 2027: separate rates of income tax will apply to property income in England, Wales and Northern Ireland.

For 2027/28, the property rates are set at:

  • 22% property basic rate
  • 42% property higher rate
  • 47% property additional rate

The government has also confirmed that the residential property finance cost tax reduction will move to the 22% property basic rate.

This change does not alter the current 2026/27 calculation. It does, however, mean Airbnb hosts planning pricing, borrowing or portfolio decisions for 2027/28 should model the higher property-specific rates rather than assuming today’s 20%, 40% and 45% structure will continue.

FAQs About Airbnb Tax UK

What Is the 15% Host Fee on Airbnb?

The so-called 15% Airbnb host fee is a platform service charge, not a UK tax. Airbnb’s 2026 UK material describes its move to a single host-paid service fee of 15.5%, replacing the previous split-fee model for affected hosts.

Hosts should check their own Airbnb account for the fee applying to their listings. For tax purposes, business-related platform charges should be considered alongside the normal property expense rules.

What Are the New Tax Rules for Airbnb Rent a Room?

There is no separate new Airbnb-specific Rent a Room exemption for 2026/27. The normal scheme continues to provide a £7,500 annual threshold, generally reduced to £3,750 where another person receives income from letting accommodation in the same residence.

The accommodation must form part of the taxpayer’s only or main residence and meet the other Rent a Room conditions.

What Does the 80/20 Rule Mean for Airbnb?

There is no HMRC rule called the 80/20 rule — in hosting circles it is a revenue observation, not a tax provision: roughly 80% of a property’s income typically comes from about 20% of its booking dates, usually peak weekends and holidays. The tax angle is twofold. First, concentrated peak income means your profits arrive in bursts, so set cash aside for the following 31 January. Second, it is a useful record-keeping prompt: a small number of peak bookings determine most of your tax, which makes reconciling your platform statements against your declared income quick work.

Is There a £1,700 Airbnb Tax Exemption?

No. The approximately £1,700 or €2,000 figure associated with digital platform reporting is an exclusion connected with occasional sales of goods, alongside a fewer-than-30-sales condition. It is not an Airbnb property-income tax exemption.

For an individual Airbnb landlord, the relevant tax relief may instead be the £1,000 property allowance or, where the conditions are satisfied, Rent a Room relief.

Can I Use the £1,000 Property Allowance and Claim Mortgage Interest Relief?

Generally, no. HMRC states that the property allowance cannot be used where the taxpayer claims the residential property finance-cost tax reduction.

Hosts with mortgage borrowing should therefore compare the result under actual property expenses and finance-cost relief with the simpler £1,000 allowance before choosing a method.

Do you pay National Insurance on Airbnb income?

Usually not. Letting property is investment income rather than a trade, so Class 2 and Class 4 National Insurance contributions do not apply. That position can change where a host provides substantial hotel-like services — daily servicing, meals, concierge arrangements — to the point the activity is really a business, but ordinary self-catering Airbnb lettings stay outside NIC.

When do you have to pay tax on Airbnb income?

Under Self Assessment, the tax on your letting profit for a tax year is due by 31 January following the tax year end, alongside any payments on account. Two separate deadlines sit outside that cycle: Capital gains tax on a sold let property is due within 60 days of completion, and from April 2026 Making Tax Digital quarterly updates apply once qualifying income exceeds £50,000. Penalties for late filing and late payment apply to each deadline separately.

Do you need an accountant for Airbnb income?

For a single room under Rent-a-Room’s £7,500 limit, almost certainly not. Beyond that, the cases where advice pays for itself are easy to list: choosing between allowances, the post-FHL transition, mortgage interest credit calculations at higher rates, 60-day CGT filings on a sale, and Making Tax Digital registration and software setup from April 2026. A fixed-fee adviser who has seen the platform’s data before HMRC does is considerably cheaper than a penalty.

How Can Apex Accountants Help Airbnb Hosts?

Airbnb tax now sits at the intersection of ordinary property taxation, digital platform reporting, Making Tax Digital and, for larger operators, VAT. The abolition of the Furnished Holiday Lettings regime has also changed the calculation for many established short-term rental owners.

Apex Accountants can help you review rental profits, allowable expenditure, mortgage finance cost relief, MTD, VAT and capital gains tax as one connected tax position rather than addressing each issue separately.

For hosts unsure whether their current reporting or structure is still appropriate, a tax review is the sensible next step.

HMRC Landlord Tax Crackdown Recovers £100m in Unpaid Tax

A landlord can report rental income for several years and still discover that the figures do not match the rent paid into their bank account. The difference may result from an incorrectly divided jointly owned property, restricted mortgage interest relief, or income from a short-term letting platform.

That is why the landlord tax crackdown matters. HMRC can obtain information from letting agents and digital platforms, compare it with tax returns, and ask landlords to explain inconsistencies. Reviewing the position before HMRC makes contact usually gives the landlord more control over how to correct an error.

Quick Answer

  • There is no new tax called a landlord crackdown. The article describes HMRC’s continuing work to identify undeclared or incorrectly reported property income.
  • Landlords paid £104m in unpaid taxes in 2025/26.
  • HMRC can obtain bulk information about rent paid by letting agents and receive seller and property information from qualifying digital platforms.
  • Individual residential landlords can use the Let Property Campaign to disclose earlier undeclared rental income.
  • Once HMRC acknowledges a Let Property campaign notification, the landlord normally has 90 days to submit the disclosure and pay or arrange payment.
  • Depending on the behaviour involved, HMRC may examine records for up to 4, 6 or 20 years.

What Does the Landlord Tax Crackdown Mean in 2026?

The landlord tax crackdown is not a new tax or a single temporary investigation. It is a broad description of HMRC’s ongoing use of data, compliance letters, voluntary disclosure arrangements and formal enquiries to collect tax that should already have been paid.

Landlords have paid £100m in HMRC’s tax crackdown, which is evidence of compliance activity. The reported £104m figure is the tax recovered through landlord disclosures during 2025/26. 

The legal obligations themselves are clear. Individuals must report taxable rental income correctly, retain supporting records and correct earlier failures where necessary. HMRC has also confirmed to Parliament that it uses several data sources to identify property-sector non-compliance and may open formal compliance interventions where landlords do not come forward.

Why Does HMRC Target UK Landlords With Undeclared Rent?

HMRC targets UK landlords because it can check rental income against information held by third parties. A landlord’s tax return is no longer the only source showing that a property has been let or how much rent may have been collected.

Under Schedule 23 of the Finance Act 2011, HMRC has data-gathering powers that can be used to obtain information from relevant data holders. HMRC’s own compliance manual specifically gives rental payments made by letting agents to landlords as an example of bulk third-party information that can be collected.

Digital platform reporting has added another source of information. Qualifying UK platform operators must collect and report information about reportable sellers, including people who rent out immovable property. For property rentals, the information can include the seller’s identity, income and the address of each property offered through the platform.

HMRC can therefore compare information from sources such as:

  • Self-assessment returns
  • Letting agents and property managers
  • Short-term rental and accommodation platforms
  • Previous correspondence and disclosures
  • Information exchanged with overseas tax authorities
  • Records requested during a compliance check

Receiving a letter does not automatically mean HMRC has proved that tax is owed. It normally means the information available to HMRC does not appear to match the return, registration position or other records.

Which Landlords Should Review Their Tax Position?

Any landlord whose gross property income exceeded the relevant reporting limits should check that the income was reported in the correct tax year and by the correct owner.

The property allowance can exempt up to £1,000 of gross property income for qualifying individuals. Where annual gross property income exceeds £1,000, further reporting action is generally required. 

A landlord should contact HMRC when gross rental income is between £1,000 and £2,500 and may need to register for Self Assessment when it exceeds £2,500. Separate self-assessment reporting limits may also apply where gross receipts exceed £10,000 or profit after expenses exceeds £2,500.

Landlords at greater risk of an incorrect return include those who

  • Let a property for the first time without registering for self-assessment
  • Became an accidental landlord after moving home or inheriting a property
  • Received rent through Airbnb or another short-term letting platform
  • Own property jointly but report all income under one owner
  • Claimed mortgage interest as a full deduction rather than a tax reduction
  • Deducted improvements as though they were routine repairs
  • Own UK property while living abroad
  • Have overseas rental income
  • Continued using former furnished holiday letting rules after their abolition
  • Sold a rental property without checking Capital gains tax reporting

The Let Property Campaign covers individual landlords renting residential property in the UK or abroad. It can also cover a single property, several properties, holiday accommodation, inherited property and income above the Rent a Room Scheme limit.

It does not cover disclosures made by companies or trusts, nor does it cover landlords letting only non-residential property, such as shops, garages or lock-ups. Those taxpayers may need to use another disclosure route.

What Rental Tax Errors Does HMRC Commonly Look For?

HMRC is likely to examine whether the landlord reported all rent and applied the property tax rules correctly. An error can arise even where the landlord did not intend to conceal income.

Area CheckedCorrect General TreatmentCommon Risk
Gross rentReport rent and other property receipts belonging to the taxpayer.Reporting only the amount left after an agent deducts fees
Joint ownershipReport the share belonging to each beneficial owner.Putting all rent on the lower earner’s return without supporting ownership
Mortgage interestIndividual residential landlords normally receive a basic-rate tax reduction.Deducting all mortgage interest from rental income
RepairsRevenue repairs may normally be deducted.Treating an improvement or extension as a repair
Property allowanceClaim the allowance or actual expenses where permitted.Claiming both against the same property income
Short-term letsReport taxable receipts from digital platforms.Assuming occasional or platform income is automatically tax-free
Overseas propertyUK residents may need to report foreign property incomeReporting UK rent but omitting an overseas property
Property saleCheck capital gains tax and the UK property reporting deadline.Assuming the annual self-assessment return is the only report required

For married couples and civil partners living together, income from jointly owned property is normally taxed equally. A different division generally requires the income split to follow the couple’s actual beneficial ownership and a valid Form 17 declaration where applicable. Simply paying rent into one person’s account does not, by itself, transfer the taxable income.

Individual residential landlords cannot normally deduct finance costs directly when calculating property profit. Instead, they may receive a tax reduction calculated at the basic rate, subject to the statutory limits.

Worked Example of the Mortgage Interest Error

Assume an individual landlord receives:

  • Rent: £18,000
  • Allowable non-finance expenses: £4,000
  • Mortgage interest: £7,000

The property profit before the finance cost tax reduction is £14,000, not £7,000.

Subject to the landlord having enough property profit, adjusted total income and income tax liability, the £7,000 finance cost may produce a tax reduction of up to £1,400, calculated at 20%. A landlord who deducts the full £7,000 when preparing the rental profit may materially understate taxable income.

Repairs also require care. HMRC distinguishes expenditure that restores an existing asset from expenditure that improves or changes it. Routine repairs may be deductible, while capital improvements are generally not deducted from rental income.

How Can Landlords Make a Voluntary Tax Disclosure?

An individual residential landlord can normally use HMRC’s Let Property Campaign to disclose undeclared rental income before the tax authority starts a formal investigation.

Voluntary tax disclosures by landlords involve two main stages:

  1. The landlord must notify HMRC that they will make a disclosure.
  2. Calculate, disclose and pay the tax, interest and penalties due.

The initial notification does not require the landlord to provide the complete calculation. HMRC issues a disclosure reference and payment reference after receiving it.

The full disclosure must then normally be submitted within 90 days of the date HMRC acknowledges the notification. The landlord must pay the amount due by that deadline or agree payment arrangements with HMRC before submitting the disclosure.

The calculation should normally consider:

  • Gross rental income for each affected tax year
  • The landlord’s legal or beneficial share
  • Allowable running expenses
  • Residential finance cost tax reductions
  • Other undeclared income that must be included
  • Income Tax or Capital Gains Tax due
  • Late payment interest
  • The appropriate penalty
  • Payments already made

Joint owners cannot make one combined disclosure. HMRC requires each taxpayer to notify and disclose their own share separately.

A disclosure that is incomplete or materially inaccurate may not be accepted. HMRC may reopen the position if later information shows that important income or liabilities were omitted.

How Far Back Can HMRC Investigate a Landlord?

HMRC may look back for 4, 6 or 20 years, depending on whether the landlord took reasonable care, acted carelessly, failed to notify the tax authority or deliberately withheld information.

Tax BehaviourMaximum Period Commonly Covered
Reasonable care taken, but too little tax paid4 years
Careless error6 years
Failure to notify HMRC of a liabilityUp to 20 years
Deliberate understatement or omissionUp to 20 years
Certain offshore mattersSeparate extended rules may apply.

HMRC states that most Let Property Campaign disclosures are expected to cover no more than six years. A longer period can apply where the landlord failed to register or deliberately omitted income.

The applicable period should not be selected simply because it produces the lowest bill. It depends on what happened, what the landlord knew and what steps were taken to check the return.

For example, a landlord who registered for self-assessment and relied on incomplete agent statements may have a different position from someone who received rent for ten years and never told HMRC that the property existed.

What Penalties Can Apply to Undeclared Rental Income?

A landlord may have to pay the unpaid tax, late payment interest and a penalty based on the potential tax lost. The percentage depends on whether the error was careless or deliberate, whether it was concealed and whether the disclosure was prompted by HMRC.

Indicative onshore inaccuracy penalty ranges include:

BehaviourGeneral Penalty Range
Careless inaccuracy0% to 30% of potential lost revenue
Deliberate inaccuracy20% to 70%
Deliberate and concealed inaccuracy30% to 100%

Where there has been a non-deliberate failure to notify and HMRC prompts the disclosure more than 12 months after the tax became due, HMRC’s published example gives a penalty range of 20% to 30% of potential lost revenue. Different ranges can apply according to the precise failure, timing and whether offshore income is involved.

Coming forward voluntarily does not cancel the underlying tax or interest. It can, however, affect whether HMRC treats the disclosure as prompted or unprompted, and it can also affect the reduction available for the quality of the disclosure.

The quality assessment considers how fully the taxpayer has:

  • Tells HMRC what went wrong
  • Helps HMRC establish the correct position
  • Gives HMRC access to relevant records

A landlord should not guess the penalty percentage. The calculation should match the tax behaviour, disclosure route and affected years.

Does Making Tax Digital Increase HMRC’s Oversight of Landlords?

Making Tax Digital gives HMRC more frequent information about in-scope property businesses, although quarterly updates are not the same as full tax investigations.

From 6 April 2026, landlords and sole traders must use Making Tax Digital for Income Tax when their combined qualifying gross income from property and self-employment exceeds £50,000 in 2024/25.

The rollout continues as follows:

Start DateRelevant Qualifying Income
6 April 2026More than £50,000 in 2024/25
6 April 2027More than £30,000 in 2025/26
6 April 2028More than £20,000 in 2026/27

Those in scope must keep digital records and use compatible software to submit quarterly updates. They must still complete the year-end tax return process and pay tax by the applicable self-assessment deadline.

MTD does not automatically correct historical rental income errors. A landlord who has already omitted earlier income may need a separate disclosure even after entering MTD.

Our guide on MTD for Income Tax for landlords and sole traders explains the reporting process in more detail. 

What Should a Landlord Do After Receiving an HMRC Letter?

A landlord should first identify exactly what HMRC is asking and avoid sending an estimated or incomplete response.

The following steps can help:

  1. Check the deadline. HMRC letters normally specify when a response is required.
  2. Identify the tax years involved. Do not assume the enquiry concerns only the latest return.
  3. Reconcile gross rent. Compare bank statements, letting-agent records, tenancy agreements and platform statements.
  4. Check ownership. Establish who was legally and beneficially entitled to the income.
  5. Review every expense. Separate allowable running expenses, finance costs and capital expenditure.
  6. Check other liabilities. Consider overseas rent, capital gains tax and other undeclared income.
  7. Do not use the wrong disclosure route. The Let Property Campaign is not available for every taxpayer or property type.
  8. Obtain professional advice before making statements about behaviour. Describing an error as careless or deliberate can affect the years and penalties involved.

Landlords should retain their rental records for at least five years after the 31 January filing deadline for the relevant tax year. HMRC may charge penalties where records are incomplete, inaccurate or not retained for the required period.

Professional HMRC tax investigation support can be particularly useful where HMRC has already identified discrepancies or requested several years of records.

FAQs About Landlord Tax Crackdown

Does HMRC Know That I Own a Rental Property?

HMRC may receive information indicating that a person rents out property even where no rental income appears on their tax return. Its statutory data-gathering powers cover information held by relevant third parties, and qualifying digital platforms report seller and property information.

Ownership alone does not prove that taxable income arose, but the landlord may need records showing whether the property was occupied, empty, used privately or let.

Can I Use the Let Property Campaign After HMRC Contacts Me?

You should obtain advice before assuming that the Let Property campaign remains available. If HMRC has identified the issue, it may treat any disclosure made after that as prompted, which can affect the penalty position.

HMRC may also direct the landlord to respond through the existing compliance check rather than submit a separate voluntary disclosure.

Do I Need to Declare Rent When the Property Makes a Cash Loss?

Possibly. Taxable property profit is not necessarily the same as the cash left after paying the mortgage.

Individual residential landlords normally cannot deduct mortgage interest directly from rental profit. They receive a basic-rate tax reduction instead, so a property can produce little cash while still generating taxable profit.

Can Joint Landlords Submit One Disclosure?

No. Each joint owner must normally submit a separate notification and disclosure covering their own share of rental income, expenses and tax.

The income split should reflect the applicable ownership and tax rules. Married couples and civil partners should also check whether the standard equal division or a valid Form 17 treatment applies.

Will a Voluntary Disclosure Prevent an HMRC Investigation?

HMRC may accept a complete and accurate disclosure without opening a wider investigation, but acceptance is not automatic. It can check the calculations, request supporting records and reopen the position if later information shows that the disclosure was incomplete.

A properly prepared disclosure should cover all relevant years, liabilities, interest and penalties.

Do I Need an Accountant for a Let Property Campaign Disclosure?

There is no legal requirement to appoint an accountant, but professional advice can be valuable where several years, joint ownership, mortgage interest, overseas property or missing records are involved.

An adviser can reconstruct the rental accounts, calculate the correct tax and penalty, prepare the disclosure and correspond with HMRC under the appropriate authority.

How Can Apex Accountants Help With a Landlord Tax Disclosure?

The next step is to establish the correct rental income before responding to HMRC or submitting a disclosure.

Apex Accountants can review rental records, reconstruct missing accounts, check allowable expenses, calculate finance cost relief and prepare voluntary disclosures. Where HMRC has already written to you, our HMRC investigation specialists can review the letter and manage the response.

Landlords who need broader return and property income support can book a consultation to discuss the landlord tax crackdown and their individual position.

Tax Liabilities From Cryptoassets Explained for UK Investors and Traders 

We are increasingly approached by people who have traded between tokens for several years but never withdrawn money to a UK bank account. Many assume that no tax arises until cryptocurrency is converted into pounds. That is not how the UK rules work.

HMRC has confirmed that it may contact people who have traded cryptoassets by letter, email or text message. The contact may ask them to check whether their crypto income and gains have been declared correctly. This makes it important to review potential tax liabilities from cryptoassets before replying or submitting another tax return.

Quick Answer

  • Buying and continuing to hold cryptoassets does not normally create an immediate tax charge.
  • Selling, exchanging, spending or giving away tokens can be a disposal for Capital Gains Tax.
  • Crypto received through employment, mining, staking or lending may be subject to Income Tax.
  • The Capital Gains Tax annual exempt amount is £3,000 for 2026/27.
  • Cryptoasset service providers have collected customer tax details under the Cryptoasset Reporting Framework since 1 January 2026.
  • Undeclared liabilities can sometimes be corrected through self-assessment or HMRC’s Cryptoasset Disclosure Service.

What Are Cryptoassets for UK Tax Purposes?

Cryptoassets are digital representations of value whose transactions are secured and validated using distributed ledger technology or similar cryptographic systems. They include exchange tokens such as bitcoin, utility tokens, security tokens, stablecoins and non-fungible tokens.

HMRC does not generally treat cryptoassets as money or currency. Their tax treatment depends on the nature of the asset, how it was acquired and what the owner did with it. A token received as payment for work can therefore have a different treatment from the same token bought as an investment.

This distinction is central to Cryptoassets and tax because a transaction may fall under:

  • Capital Gains Tax
  • Income Tax
  • National Insurance contributions
  • Corporation Tax
  • Inheritance Tax
  • VAT, where a business supplies taxable goods or services in return for cryptoassets

For most individuals buying tokens as investments, HMRC expects gains and losses to fall within the Capital Gains Tax rules rather than being treated as trading profits. The position may differ where the frequency, organisation, commercial purpose and overall circumstances amount to a financial trade.

Why Is HMRC Reviewing Tax Liabilities From Cryptoassets?

HMRC is reviewing crypto activity because exchange and service-provider information can be compared with tax returns and other taxpayer records. Its official guidance confirms that people who traded cryptoassets may receive letters, emails or text messages asking them to check and report crypto income or gains.

Receiving a letter does not automatically mean HMRC has opened a formal investigation or decided that tax is due. It does mean the taxpayer should carry out a proper reconciliation rather than reply from memory.

A review should include:

  • Centralised exchange accounts
  • Self-custody wallets
  • Decentralised exchanges
  • Staking and lending platforms
  • Airdrops and token rewards
  • Purchases made using tokens
  • Transfers between personally controlled wallets
  • Transactions on overseas platforms
  • Previous disposals and reported capital losses

One common mistake is to review only cash withdrawals. A taxable disposal may have occurred even where the proceeds remained within the crypto ecosystem.

Which Crypto Transactions Trigger Capital Gains Tax?

Capital gains tax can arise when an individual sells, exchanges, spends or gives away cryptoassets. The tax is charged on the gain, not the total amount received.

HMRC treats the following transactions as disposals:

Crypto ActivityUsual UK Tax TreatmentPractical Point
Buying and holding tokensNo immediate disposalTax is normally considered when the tokens are later disposed of.
Selling tokens for poundsCapital disposalCalculate the difference between disposal proceeds and allowable cost.
Exchanging one token for anotherCapital disposalThe sterling market value of the token received is used.
Using tokens to buy goods or servicesCapital disposalTax may arise even though no cash is received.
Gifting tokens to another personUsually a market-value disposalTransfers to a spouse or civil partner normally follow different rules.
Moving tokens between wallets under the same ownershipNormally no disposalEvidence of beneficial ownership should be retained.
Donating tokens to charityUsually no Capital Gains TaxExceptions can apply to tainted donations or sales above acquisition cost.

HMRC specifically confirms that exchanging one type of token for another is a disposal. Moving the same tokens between wallets that remain under the same beneficial ownership is not normally a disposal.

The gain is broadly calculated as:

Sterling disposal value minus allowable acquisition cost and allowable transaction costs

Allowable costs may include acquisition expenditure, transaction fees, certain valuation costs and the appropriate share of a pooled acquisition cost. Costs already deducted for Income Tax cannot normally be deducted again.

When Does Receiving Crypto Create an Income Tax Liability?

Crypto received from employment, mining, staking or lending can create an Income Tax liability at the point of receipt. Its sterling value at that time is normally used to calculate the taxable amount.

How Crypto Is ReceivedUsual Tax Treatment
Employment remunerationEmployment income, potentially subject to PAYE and National Insurance
Mining carried on as a trade.Trading income
Occasional mining outside a tradeMiscellaneous income
Staking rewards outside a tradeMiscellaneous income
Lending or DeFi returnsUsually miscellaneous income where no trade exists
Airdrop received for performing a serviceTrading or miscellaneous income
Unsolicited personal airdrop with no service or conditionMay fall outside Income Tax, although a later disposal can create a capital gain

HMRC allows up to £1,000 of combined trading and miscellaneous income each tax year through the trading and miscellaneous income allowance. Crypto income counts towards the same allowance as other relevant income sources. Where total miscellaneous income is between £1,000 and £2,500, HMRC says the individual should contact it. Where it exceeds £2,500, self-assessment registration may be required.

An airdrop does not automatically create Income Tax. HMRC says Income Tax may not apply where tokens are received without the recipient providing a service, meeting conditions or carrying on a related trade. A later sale or exchange can still produce a chargeable gain.

Where income tax has already been charged on tokens, the value taxed as income generally becomes part of their acquisition cost. Capital gains tax is then considered only on the subsequent increase or decrease in value.

How Much Tax on Cryptoassets Could You Pay in 2026/27?

For 2026/27, individuals have a capital gains tax annual exempt amount of £3,000. Gains falling within the unused basic-rate band are generally taxed at 18%, while gains above that band are generally taxed at 24%.

2026/27 MeasureAmount or Rate
Capital Gains Tax annual exempt amount£3,000
Capital Gains Tax rate within the available basic-rate band18%
Capital Gains Tax rate above the basic-rate band24%
Basic-rate band used in the CGT calculation£37,700
Trading and miscellaneous income allowanceUp to £1,000

Income from employment, staking, mining or lending is taxed under the relevant Income Tax rules rather than the Capital Gains Tax rates. The precise rate depends on the taxpayer’s total income, residence and circumstances. Scottish Income Tax bands differ for certain types of non-savings, non-dividend income.

Worked Crypto Capital Gains Tax Example

Suppose an individual has taxable income of £30,000 and makes total net crypto gains of £15,000 during 2026/27.

  1. Deduct the £3,000 annual exempt amount.
  2. The taxable gain is £12,000.
  3. The remaining basic-rate band is £37,700 minus £30,000, which equals £7,700.
  4. £7,700 is taxed at 18%, producing £1,386.
  5. The remaining £4,300 is taxed at 24%, producing £1,032.
  6. The total Capital Gains Tax is £2,418.

This assumes there are no other gains, losses or reliefs affecting the calculation.

A separate reporting rule can apply even where the gain is below £3,000. An individual already registered for self-assessment must report capital disposals if the total proceeds from relevant assets exceed £50,000 for 2023/24 onwards.

How Are Crypto Gains Calculated Under HMRC Pooling Rules?

Fungible tokens of the same type are normally grouped into a separate Section 104 pool. Instead of identifying the precise bitcoin or ether sold, the taxpayer maintains a running quantity and pooled allowable cost.

Each token type requires its own pool. Bitcoin, ether and another token would therefore have three separate calculations.

Disposals are matched in this order:

  1. Tokens acquired on the same day as the disposal
  2. Tokens of the same type acquired within the following 30 days
  3. Tokens held in the Section 104 pool

The 30-day rule can affect people who sell tokens and buy the same type back shortly afterwards. It may prevent the new purchase cost from immediately entering the general pool and instead match it against the earlier disposal.

NFTs are normally separately identifiable. HMRC therefore states that they are not pooled in the same way as interchangeable tokens.

Pooling is one reason exchange-generated gain reports should not be accepted without checking them. A platform may not know what the user holds elsewhere, whether tokens were transferred between personal wallets or whether a same-day or 30-day acquisition occurred on another exchange.

What Records Does HMRC Expect Crypto Investors to Keep?

Taxpayers must keep records showing how each taxable figure was calculated. An exchange statement alone is rarely sufficient where several platforms or private wallets have been used.

Records should include:

  • The type and quantity of tokens
  • Acquisition and disposal dates
  • Sterling values at the time of each transaction
  • Transaction identifiers
  • Wallet addresses
  • Exchange statements
  • Bank statements
  • Fees and other allowable costs
  • Tokens remaining after each disposal
  • Pooled costs before and after each transaction
  • Evidence that wallet-to-wallet movements remained under the same beneficial ownership
  • Records of mining, staking, lending and airdrop income

HMRC warns that exchange reports are not tax calculations and do not maintain a taxpayer’s complete pooled costs. Individuals remain responsible for keeping their own records.

Values must be converted into pounds sterling using a reasonable and consistently applied valuation at the relevant transaction time. Retaining the pricing source and calculation is particularly important for low-liquidity tokens.

How Does the Cryptoasset Reporting Framework Affect HMRC Data?

The Cryptoasset Reporting Framework requires relevant service providers to collect identifying information and report transaction data. It gives HMRC a more systematic method of linking crypto activity to individual and business tax records.

Since 1 January 2026, service providers have been required to collect details, including a customer’s:

  • Full name
  • Address
  • Country or countries of tax residence
  • Tax identification number

Entities may also need to provide information about their controlling persons.

The first provider reports must be submitted between 1 January and 31 May 2027, covering the calendar year from 1 January to 31 December 2026. Subsequent reports are due by 31 May for the preceding calendar year.

Using an overseas exchange does not necessarily keep the activity outside HMRC’s view. Where the provider’s country participates in the same international reporting arrangements, its tax authority can share information with HMRC.

CARF data does not calculate the customer’s UK tax liability. It provides transaction and identity information that HMRC can compare with declared income and gains. The taxpayer must still apply the UK income, disposal, pooling and loss rules correctly.

What Should You Do if HMRC Contacts You About Crypto?

You should verify the communication, preserve the underlying records and calculate the correct position before replying. A rushed response based only on one exchange account may create further inconsistencies.

Take the following steps:

  1. Confirm the contact is genuine. Compare it with HMRC’s published contact guidance and do not provide information through an unverified link.
  2. Read the wording carefully. Establish whether it is an educational letter, a request to review your position, a formal information notice or an investigation.
  3. Download transaction histories promptly. Platforms can close, merge or restrict access to old records.
  4. Map transfers between accounts and wallets. This avoids treating internal movements as sales while identifying genuine swaps.
  5. Separate income from capital transactions. Staking income should not simply be grouped with investment gains.
  6. Reconstruct token pools. Apply same-day, 30-day and Section 104 matching rules.
  7. Review all relevant tax years. Do not restrict the calculation to the year mentioned unless the letter clearly does so.
  8. Correct errors through the appropriate route. This may involve an amended return, a new return or HMRC’s disclosure service.
  9. Reply within the stated deadline. Keep a copy of the calculations, supporting records and correspondence.

Where the records involve multiple wallets, DeFi arrangements, historic transactions or missing acquisition values, obtaining professional HMRC investigation support before responding can reduce the risk of providing an incomplete explanation.

How Can Undeclared Crypto Tax Be Corrected?

Undeclared crypto income or gains should be corrected using the route appropriate to the tax year and the taxpayer’s filing position. HMRC operates a dedicated Cryptoasset Disclosure Service for unpaid Income Tax and Capital Gains Tax relating to assets including exchange tokens, NFTs and utility tokens.

CircumstancePossible Correction Route
A current return has not yet been submitted.Include the correct figures in Self Assessment
A submitted return remains open for amendment.Amend the Self Assessment return
A return should have been submitted but was not.Register or submit the missing return as required.
Unpaid tax relates to earlier years.Consider the Cryptoasset Disclosure Service.
HMRC has already opened an enquiry.Follow the enquiry process rather than making an unrelated disclosure.

The number of years covered depends partly on the taxpayer’s behaviour:

  • Up to 4 years where reasonable care was taken
  • Up to 6 years where insufficient care was taken
  • Up to 20 years where the failure was deliberate

HMRC charges interest from the date the tax should have been paid. Its crypto disclosure guidance also requires the taxpayer to calculate the appropriate penalties and generally pay the disclosed amount within 30 days of submitting the disclosure.

Penalties are fact-specific. HMRC states that where it identifies unpaid crypto tax, a penalty can reach 100% of the tax due, plus interest, with potentially higher penalties for offshore matters. This is a maximum rather than an automatic rate. The final percentage depends on matters such as behaviour, disclosure and cooperation.

A voluntary and complete disclosure will generally place a taxpayer in a stronger position than waiting for HMRC to identify the discrepancy.

What Crypto Tax Changes Are Planned From April 2027?

The government has published draft legislation proposing new rules for eligible stablecoins, cryptoasset loans and liquidity pools from April 2027. These measures are not yet the rules for 2026/27 and should not be applied early.

The proposed changes include:

  • Exempting disposals of eligible stablecoins from Capital Gains Tax for individuals and trustees
  • Taxing interest-like returns from eligible stablecoins as savings income
  • Applying the stablecoin changes from 6 April 2027 for individuals and trustees
  • Applying separate company provisions from 1 April 2027
  • Introducing no-gain, no-loss treatment for specified crypto lending arrangements
  • Introducing new rules for certain borrowing and automated market-maker liquidity arrangements

The government intends to include these measures in Finance Bill 2026/27. Draft legislation was released for technical consultation, which means the final wording may change before enactment.

Until the legislation takes effect, eligible stablecoin exchanges and transfers into lending or liquidity arrangements must be considered under the existing rules. Taxpayers should not assume that a stablecoin transaction is currently exempt merely because its value is linked to sterling or another fiat currency.

For more background on the reporting changes, see our guide to crypto tax reporting requirements in the UK.

FAQs About Tax on Cryptoassets in UK

Do I Pay Tax if I Only Buy and Hold Crypto?

Buying cryptoassets and continuing to hold them does not normally create an immediate Capital Gains Tax charge. Tax is generally considered when the tokens are sold, exchanged, spent or given away. Income Tax may apply earlier where the tokens were received as earnings or rewards.

Are Crypto-to-Crypto Swaps Taxable Without a Cash Withdrawal?

Yes. Exchanging one type of token for another is normally a disposal for Capital Gains Tax, even when no pounds enter a bank account. The sterling market value of the tokens received is used when calculating the disposal proceeds.

Can I Claim a Tax Loss if I Lose My Private Key?

Losing a private key does not itself count as a disposal because the tokens still exist on the distributed ledger. A negligible-value claim may be possible where there is no realistic prospect of recovering the key or accessing the assets. Evidence of the loss and recovery attempts should be retained.

Must I Report Crypto Gains Below the £3,000 Allowance?

You will not normally pay Capital Gains Tax where total taxable gains remain within the annual exempt amount. However, someone already within Self Assessment must report relevant disposals if total proceeds exceed £50,000. Reporting a capital loss may also be worthwhile so it can be used against qualifying gains in later years.

Can HMRC See Transactions on an Overseas Crypto Exchange?

HMRC may receive information from overseas providers where the relevant country participates in international cryptoasset reporting arrangements. CARF is designed to allow transaction and identity information to be exchanged between participating tax authorities.

Do I Need an Accountant to Report Crypto Tax?

There is no general legal requirement to appoint an accountant solely because you own cryptoassets. Professional assistance is required where there are multiple exchanges, DeFi transactions, missing records, historic liabilities, large gains or HMRC correspondence. The value lies in reconstructing the figures correctly and applying the income, pooling and disclosure rules consistently.

When Should You Seek Professional Crypto Tax Advice?

Professional advice is particularly useful before responding to HMRC, correcting several tax years or submitting calculations involving multiple exchanges and wallets.

Apex Accountants can review transaction records, reconstruct token pools, separate income from capital gains and assess whether a tax return amendment or disclosure is required. Our capital gains tax services and HMRC tax investigation support can provide a structured route to correcting the position.

The next step is to book a consultation before replying to HMRC or submitting figures that may be incomplete.

Legally Pay Zero Property Tax Under UK Rules in 2026

Property owners often ask whether they can legally pay zero property tax, particularly after seeing claims about tax-free property companies, uninhabitable homes, or overseas-style exemptions. The difficulty is that the UK does not have one tax officially called “property tax.” Different liabilities can arise when you buy, own, rent, sell, or pass on a property.

A landlord may, therefore, pay no Stamp Duty Land Tax on one transaction but still owe Income Tax on rent. A homeowner may sell a main residence without capital gains tax but continue paying council tax. Paying nothing is legally possible only when a specific allowance, exemption, or relief covers the relevant charge.

Quick Answer

  • The UK has no single annual tax called property tax.
  • Rental income can be tax-free where it falls within the £1,000 property allowance or qualifying Rent-a-Room Relief.
  • A qualifying main-home sale can result in £0 Capital Gains Tax through Private Residence Relief.
  • Stamp Duty Land Tax may be £0 where the purchase price falls within the relevant nil-rate band.
  • Property condition alone does not create general “uninhabitable property” Stamp Duty relief.
  • Council Tax reductions depend on the occupants, property use, and the rules applied by the local authority.

What Does Property Tax Mean in the UK?

“Property tax” is an umbrella expression rather than the name of one UK tax. The charge that applies depends on what the owner does with the property and where it is located.

Tax or ChargeWhen It May AriseCan the Liability Be £0?
Income Tax or Corporation TaxWhen a property produces rental profitYes, if no taxable profit remains or an allowance covers the income
Capital Gains TaxWhen an individual disposes of a property at a gainYes, where reliefs, losses or the annual exempt amount cover the gain
Stamp Duty Land TaxWhen land or property is acquired in England or Northern IrelandYes, where the consideration is within the nil-rate band or a valid relief applies
Land and Buildings Transaction TaxProperty purchases in ScotlandYes, depending on Scottish thresholds and reliefs
Land Transaction TaxProperty purchases in WalesYes, depending on Welsh thresholds and reliefs
Council TaxResidential property in England, Scotland and WalesSometimes, through discounts, reductions or exemptions
Domestic RatesResidential property in Northern IrelandSometimes, under Northern Ireland relief rules
Inheritance TaxWhen property forms part of a chargeable estateYes, where exemptions, reliefs and available bands cover the estate

Stamp Duty Land Tax applies only to England and Northern Ireland. Scotland uses Land and Buildings Transaction Tax, while Wales uses Land Transaction Tax. Northern Ireland also uses domestic rates rather than Council Tax.

Can You Legally Pay Zero Property Tax in the UK?

You can legally pay zero on a particular property tax where the facts meet an exemption, allowance, nil-rate band, or relief. There is no general election that removes every tax connected with owning property.

For example, a person might legitimately pay:

  • £0 Income Tax because their qualifying rental receipts fall within an allowance.
  • £0 Capital Gains Tax because the property has always qualified as their only or main residence.
  • £0 Stamp Duty Land Tax because the purchase price is within the relevant nil-rate band.
  • Reduced or no Council Tax because an exemption or reduction applies.

The position changes when one person owns several properties, receives substantial rent, or holds investment property through a company. Legal planning requires each tax to be calculated separately.

Claims that a particular ownership structure automatically allows investors to avoid tax on investment property in the UK should be treated cautiously. Companies, partnerships, trusts, and individual ownership can all create different tax costs at purchase, during ownership, and on extraction or sale.

When Can Rental Income Be Completely Tax-Free?

Rental income can be tax-free where the available allowance covers the receipts or allowable expenses reduce the taxable profit to zero. The correct result depends on the type of letting and the owner’s other income.

When Does the Property Allowance Apply?

Individuals can generally receive up to £1,000 of gross property income per tax year without paying tax on it. Where gross receipts exceed £1,000, the taxpayer can normally choose between deducting the £1,000 allowance or claiming actual allowable expenses, subject to the detailed restrictions.

The property allowance is based on gross income, not profit. It may not be available in some connected-party or company-related arrangements, so owners should check the conditions before relying on it.

When Does Rent-a-Room Relief Apply?

Rent-a-Room Relief can exempt up to £7,500 a year where an individual lets furnished accommodation in their only or main home. The limit is £3,750 each when the income is shared with another person.

The relief does not generally apply to a separate buy-to-let property. It is aimed at furnished accommodation within the taxpayer’s home.

How Can Landlords Reduce Property Income Tax Legally?

Landlords can reduce property income tax by claiming expenses that are wholly and exclusively connected with the rental business, using available allowances and keeping evidence for every deduction. They cannot simply reclassify private or capital spending as a rental cost.

Typical allowable revenue expenses may include the following:

  • Letting agent and management fees
  • Landlord insurance
  • Repairs and routine maintenance
  • Accountancy costs relating to the rental business
  • Council Tax, utilities and service charges paid by the landlord
  • Legal costs for short-term tenancy matters
  • Replacement of qualifying domestic items

Capital improvements are treated differently. The cost of adding a new extension, substantially upgrading a property, or buying an asset for the first time is not normally deducted as an ordinary repair. Some expenditure may instead be relevant when calculating a future capital gain.

Replacement of Domestic Items Relief can apply when a landlord replaces items such as furniture, appliances, or kitchen equipment provided to a tenant. It applies to replacements rather than the first purchase of an item, and deductions may be restricted where the replacement is significantly better than the original.

How Is Mortgage Interest Treated?

Individual residential landlords cannot deduct mortgage interest directly when calculating property profit. Instead, qualifying finance costs generally produce a basic-rate Income Tax reduction.

For 2026/27, a higher-rate landlord might have the following:

  • Gross rent: £18,000
  • Allowable non-finance expenses: £4,000
  • Mortgage interest: £6,000
  • Taxable property profit: £14,000
  • Income Tax at 40%: £5,600
  • Basic-rate finance-cost reduction: £1,200
  • Simplified net liability: £4,400

This example assumes the full tax reduction is available and ignores the taxpayer’s other income, losses, and restrictions.

The government has announced separate property income tax rates of 22%, 42% and 47% from 6 April 2027 for England, Wales and Northern Ireland, with the finance-cost reduction moving to 22%. The practical application, including interaction with devolved powers, should be rechecked before the 2027/28 tax year.

Landlords with qualifying gross income above £50,000 entered Making Tax Digital for Income Tax from 6 April 2026, subject to exemptions and transitional rules.

Does a Limited Company Always Reduce Tax on Investment Property?

A limited company does not automatically produce the lowest overall tax bill. A company pays Corporation Tax on its property profits, while its shareholders may face further tax when profits are withdrawn.

Residential finance costs are generally dealt with differently for companies, which can make incorporation appear attractive to highly geared investors. However, the comparison must also consider:

  • Stamp Duty Land Tax when property is acquired or transferred
  • Capital Gains Tax or Corporation Tax on a future disposal
  • Tax on dividends, salary or loans used to extract funds
  • Mortgage pricing and refinancing costs
  • Accountancy, Companies House and legal obligations
  • Inheritance Tax and succession objectives

Transferring an existing personally owned property portfolio to a company is not a simple administrative change. It is a disposal and acquisition that can create tax liabilities unless the facts support a particular relief.

A properly modelled comparison should cover the expected holding period, borrowing, income requirements and planned exit. 

When Can Capital Gains Tax on a Property Sale Be £0?

Capital Gains Tax can be £0 where Private Residence Relief covers the full gain, allowable losses absorb it or the taxable gain falls within the annual exempt amount. The annual exempt amount is £3,000 for individuals in 2026/27.

Residential property gains are generally taxed at 18% to the extent they fall within the taxpayer’s unused basic-rate band and 24% above it.

When Does Private Residence Relief Cover the Full Gain?

A homeowner can usually receive full Private Residence Relief where the property has been their only or main home throughout ownership and the statutory conditions are met. In that situation, the qualifying gain may be completely exempt.

The final nine months of ownership normally qualify where the property has been the owner’s main residence at some point. A 36-month final period can apply in certain cases involving disabled people or people moving into long-term residential care.

Relief may be restricted where:

  • Part of the property was used exclusively for business
  • The property was let
  • The grounds exceed the area permitted for reasonable enjoyment
  • The owner did not occupy it as a genuine residence
  • The property was acquired mainly to make a gain

UK residents who dispose of UK residential property and have Capital Gains Tax to pay generally need to report and pay it within 60 days of completion.

A detailed calculation may be needed where occupation changed during ownership. Apex provides capital gains tax services for property disposals and relief claims.

When Can Stamp Duty Land Tax Be £0 or Lower?

Stamp duty land tax can be £0 where an England or Northern Ireland residential purchase falls within the applicable nil-rate band. Relief may also apply to qualifying first-time buyers and certain specialist transactions.

The standard residential rates for 2026/27 are:

Portion of Residential PriceStandard SDLT Rate
Up to £125,0000%
£125,001 to £250,0002%
£250,001 to £925,0005%
£925,001 to £1.5 million10%
Above £1.5 million12%

These are progressive rates, so each percentage applies only to the portion within that band.

Qualifying first-time buyers can pay:

  • 0% on the first £300,000
  • 5% on the portion from £300,001 to £500,000

No first-time buyer relief is available where the purchase price exceeds £500,000.

A qualifying first-time buyer purchasing for £295,000 could therefore pay £0 SDLT. An ordinary buyer purchasing at the same price would pay SDLT under the standard bands.

Additional residential properties generally attract rates that are five percentage points above the standard rates. A buyer replacing their main residence may avoid the higher rates where the previous main home is sold on time. A refund may be available when it is sold within the relevant 36-month period.

Other points include:

  • A 2% non-UK resident surcharge can apply.
  • Mixed-use and non-residential property uses different rates, beginning with a £150,000 nil-rate band.
  • Multiple Dwellings Relief was abolished for transactions completing on or after 1 June 2024, subject to transitional rules.

Is There Stamp Duty Relief for an Uninhabitable Property?

There is no standalone stamp duty relief for uninhabitable property. A building attracts non-residential rates only where, at the effective transaction date, it is not suitable for use as a dwelling under the statutory test.

HMRC describes this as a narrow test. A property does not stop being a dwelling merely because it needs major repairs, has no working utilities or cannot be occupied safely without renovation. The question is whether it retains the fundamental characteristics of residential accommodation.

In Mudan v HMRC [2025] EWCA Civ 799, the Court of Appeal upheld the conclusion that a severely dilapidated property remained suitable for use as a dwelling for SDLT purposes. The case shows why a renovation budget or survey describing a property as uninhabitable does not, by itself, justify applying non-residential rates.

Factors such as a damaged roof, missing boiler, defective wiring, damp or an unusable kitchen must be considered together. No single defect guarantees non-residential treatment.

A buyer remains responsible for the accuracy of the return even where a SDLT repayment agent submits the claim. Interest, penalties and professional fees can outweigh any temporary refund. 

Which Council Tax Reductions Can Lower Recurring Property Costs?

Council Tax can be reduced where the occupants, property or use meets the relevant conditions. The rules are administered locally, so owners should check the policy of the council where the property is situated.

In England and Wales:

  • A 25% discount usually applies where only one resident is counted for Council Tax.
  • A 50% discount may apply where every resident is disregarded but the property is not fully exempt.
  • Council Tax Reduction may be available to people on a low income.
  • Certain properties can be exempt for a limited or continuing period.

The Disabled Band Reduction Scheme can place a qualifying home in the band immediately below its normal band. The home must contain a qualifying feature required by a disabled resident, such as an additional room, bathroom, kitchen or sufficient indoor wheelchair space.

Empty homes do not automatically receive an exemption. A council may grant a discount, charge the full amount or impose a premium depending on how long the property has been empty.

English councils have also been able to charge a premium of up to 100% on second homes from April 2025, subject to notice requirements and statutory exceptions.

For UK readers, reducing recurring property taxes generally means checking Council Tax, Scottish Council Tax or Northern Ireland domestic-rate reliefs. It does not refer to a single UK-wide annual property tax.

Can Inheritance Tax on Property Be £0?

Inheritance Tax on property can be £0 where the estate is covered by exemptions, reliefs and available nil-rate bands. Property does not receive a universal exemption simply because it was the deceased’s home.

For 2026/27:

  • The ordinary nil-rate band is £325,000.
  • The standard Inheritance Tax rate above available allowances is 40%.
  • The residence nil-rate band can provide up to £175,000 where a qualifying home passes to direct descendants.
  • The residence nil-rate band begins to taper for estates above £2 million.

The available amount can depend on lifetime gifts, previous spouse or civil-partner transfers, trusts, debts, ownership shares and the identity of the beneficiaries. The nil-rate bands are currently scheduled to remain frozen until 5 April 2031.

Giving away a home while continuing to live there rent-free may fall within the gift-with-reservation rules, meaning the property can remain part of the estate. Property owners considering gifts, trusts or succession structures should take advice before changing legal ownership.

What Changed for Furnished Holiday Lets After April 2025?

The separate Furnished Holiday Let tax regime ended on 6 April 2025 for Income Tax and Capital Gains Tax and from 1 April 2025 for Corporation Tax. Former qualifying holiday-let businesses are now generally taxed under the ordinary property-income rules.

This removed several former advantages, including special finance-cost treatment for individual owners and access to certain capital gains reliefs based solely on FHL status.

Owners may now need to review the following:

  • Finance-cost restrictions
  • Replacement of Domestic Items Relief
  • Capital allowances previously claimed
  • Loss relief
  • VAT registration and taxable turnover
  • Business rates or Council Tax treatment
  • Whether Making Tax Digital applies

The end of the FHL regime does not mean every short-term rental is treated identically. VAT, planning, rates and trading questions can still depend on the services provided and the use of the property.

How Can Property Owners Pay the Least Amount of Property Taxes Legally?

Property owners can pay the least amount of property taxes by applying valid reliefs at the correct time, claiming only supportable expenses and choosing an ownership structure based on complete calculations. The aim should be the correct legal liability, not an artificial zero-tax result.

Before buying, transferring or selling property, check:

  1. Whether the property is a home, investment, commercial building or mixed-use asset.
  2. Whether higher purchase tax rates apply.
  3. Whether ownership will be personal, joint, corporate, partnership or trust-based.
  4. Which expenses are revenue costs and which are capital.
  5. Whether Private Residence Relief or another disposal relief applies.
  6. Whether a return, election or claim has a deadline.
  7. Whether the arrangement has non-tax costs, including refinancing and legal fees.

Effective property tax exemptions and reliefs depend on evidence. Keep completion statements, tenancy agreements, invoices, finance records, valuations, occupation evidence and correspondence with local authorities.

FAQs About Zero Property Tax in UK

Do I Need to Declare Rental Income Below £1,000?

Gross property income of no more than £1,000 may be covered by the property allowance, meaning no tax return is required solely for that income in many cases. Exceptions can apply, including where the income comes from certain connected businesses or the taxpayer needs to register for another reason.

Can I Claim the Cost of Replacing a Kitchen in a Rental Property?

The cost may be deductible as a repair where the work restores the existing kitchen without a significant improvement. A substantial upgrade, extension or redesign may be capital expenditure. The invoice and scope of work should separate repairs from improvements where possible.

Is an Empty Property Exempt From Council Tax During Renovation?

Not automatically. The local authority may charge the full bill, offer a discretionary discount or impose a premium if the property remains empty for a prolonged period. Owners should obtain the council’s decision rather than assuming building work creates an exemption.

Is Buying Property Through a Company Always More Tax-Efficient?

No. A company can offer different treatment of finance costs and retained profit, but it may also create purchase taxes, extraction taxes, administrative costs and different disposal consequences. The structure should be compared using expected rental profit, borrowing, ownership period and exit plans.

Do I Always Pay No Capital Gains Tax When Selling My Home?

No. Full Private Residence Relief normally requires the property to have been a genuine only or main residence throughout the qualifying period. Letting, exclusive business use, large grounds or periods of non-occupation may leave part of the gain taxable.

Can an SDLT Refund Company Guarantee an Uninhabitable Property Claim?

No adviser can guarantee that ordinary disrepair makes a home non-residential. HMRC may challenge the return, recover the refund and charge interest or penalties. Buyers should obtain independent regulated advice before signing a fee agreement or amending an SDLT return.

Speak to Apex Accountants About Property Tax Planning

Paying £0 tax is lawful only where the facts fall within a recognised allowance, exemption or relief. Apex Accountants can review rental profits, ownership structures, purchase taxes, capital gains tax and estate planning to identify the correct liability and reduce unnecessary exposure without relying on aggressive arrangements.

How to Complete CT600P Form for Creative Tax Relief Claims 

We are increasingly asked the same question by production companies and arts organisations: why does a claim that looked routine last year now need another corporation tax schedule? The short answer is that HMRC introduced the CT600P form for creative sector tax relief claims in April 2026 and from returns submitted on or after 6 April 2026. It must now accompany creative industries’ relief and expenditure credit claims made on a CT600. HMRC also moved the expenditure-credit redemption detail into CT600P, so this is not a cosmetic extra page; it is now part of what makes many claims complete and processable. 

Quick answer

  • CT600P is HMRC’s new creative industries supplementary page for corporation tax claims, covering AVEC, VGEC, the legacy film, TV and video game reliefs, and the cultural reliefs for theatre, orchestras, museums, and galleries. 
  • If you submit a creative industries claim on or after 6 April 2026, you generally need to file CT600P with the CT600 at the same time, including for amended claims. 
  • CT600P does not replace the additional information form. The additional information form is still mandatory and must be sent before or on the same day as the CT600; otherwise, HMRC can treat the claim as invalid and amend the return to remove it. 
  • The biggest practical risks are missing the claim deadline, mismatching dates between the CT600 and the additional information form, omitting BFI certification or cost breakdowns, and forgetting that CT600P can cover only 12 months at a time. 

What is the CT600P form for creative sector tax relief claims?

CT600P is HMRC’s new supplementary page for creative industries claims made as part of a Company Tax Return. HMRC published the form on 6 April 2026, and the current form is CT600P (2026) Version 3. It is designed to capture the figures for creative reliefs and expenditure credits, including the redemption steps for AVEC and VGEC that determine how much is set against tax, surrendered in a group, or paid out. 

In practice, the form does three jobs. It records the expenditure and credit figures for AVEC and VGEC; it carries out the step-by-step redemption calculation for those credits; and it also provides the Corporation Tax supplementary reporting for the older audiovisual and video games reliefs plus the cultural reliefs. That matters because CT600P is not limited to new-style credits: it also reaches legacy claims still alive in the transitional period. 

It is important to note here that CT600P is not just an AVEC/VGEC form. It is a single creative-industries schedule that now sits across film, television, video games, theatre, orchestra, and museums and galleries’ claims. 

Who now has to file the new supplementary page CT600P?

Any company submitting a return on or after 6 April 2026 for a creative industries relief or expenditure credit claim should complete CT600P unless HMRC’s current guidance states otherwise.

HMRC’s public guidance says the requirement applies to creative industry claims submitted on or after that date, and HMRC’s online service guidance confirms it applies to both new and amended claims. 

The claims in scope are set out in HMRC’s CT600P guidance and creative industries guidance.

SituationIs CT600P needed?Why it matters
New AVEC claimYesCT600P carries the expenditure figures and credit redemption steps
New VGEC claimYesCT600P carries the expenditure figures and credit redemption steps
New legacy film, TV or video games relief claimYesCT600P still covers predecessor reliefs during transition
New theatre, orchestra, museum or gallery claimYesCT600P also covers cultural reliefs
Amended creative industries claimYesHMRC says the requirement applies to amended claims too
Company receiving surrendered AVEC/VGEC from a group companyOften yesCT600P can be used even if the recipient is not making its own creative claim, and CT600 box 614 may also be relevant

** The table above reflects HMRC’s current guidance on CT600P scope and on group-surrendered AVEC/VGEC amounts. 

One overlooked edge case is group relief for expenditure credits. HMRC’s CT600P guidance says a company can include amounts surrendered from other group companies even where it is not itself claiming a creative tax relief in that return. If you decide not to include some surrendered amounts in CT600P, HMRC still expects the surrendering company details to appear in the computations. 

Read: How Creative Industry Tax Reliefs Can Reduce Your Corporation Tax Bill

Which claims and headline rates does CT600P cover in 2026?

CT600P covers both the new expenditure-credit regimes and the reliefs that still survive in the transitional window. For audiovisual and video games, the tax system is now centred on AVEC and VGEC, with legacy film, television, animation and video games reliefs closing to new productions after 31 March 2025 and closing fully from 1 April 2027. 

Claim typeCurrent headline rateImportant transitional point
AVEC for most films and high-end TV34%Available on qualifying expenditure incurred from 1 January 2024
AVEC for children’s TV and animation39%Applies to animated films and animated TV programmes, plus children’s TV
AVEC for certified independent films53%Higher rate claimable from 1 April 2025 on costs incurred from 1 April 2024, with a £15 million core-cost cap
Additional AVEC for relevant VFX costs39%Available from 1 April 2025 for qualifying UK VFX costs incurred from 1 January 2025; outside the usual 80% cap
VGEC34%Available on qualifying video game expenditure incurred from 1 January 2024
Legacy film, TV and video games reliefsUsually 25% payable credit on surrendered lossClosed to new productions after 31 March 2025 and close fully from 1 April 2027
Theatre, Orchestra and Museums/Galleries reliefs40% non-touring, 45% touring and orchestralPermanent rates from 1 April 2025

**The rates and dates above come from HMRC’s current AVEC, VGEC and legacy-relief guidance, plus the government’s policy papers on the permanent cultural-relief rates. 

  • Eligibility

The rule set still turns heavily on whether the claimant is the proper production company and whether the production meets the relevant certification test. 

  • AVEC

Films and TV programmes must be certified as British or qualify under a co-production treaty, and at least 10% of core costs must relate to UK activities. 

  • VGEC

The game must be British-certified, intended for supply to the general public, and at least 10% of core costs must relate to UK activities. 

What does CT600P guidance require you to enter?

CT600P guidance requires three broad categories of information: the accounting-period details, the expenditure-and-credit figures, and the cross-reference figures that feed back into the main CT600. The form starts with company details and an accounting period that cannot exceed 12 months. If the company’s period of account is longer than 12 months, you will need more than one tax return and more than one additional information form. 

AVEC and VGEC Guidance

HMRC asks for the building blocks of the calculation. That includes relevant global expenditure, the part of that expenditure that is UK expenditure, the qualifying expenditure for the period, and the credit claimed for the period. For AVEC, CT600P also has a separate box for the additional visual effects credit. 

For AVEC and VGEC, the form then walks through the six redemption steps. That is where many businesses slip: CT600P is not asking only what the gross credit is, but also how much is used against Corporation Tax, how much survives the notional tax charge, how much is surrendered to a group company, how much is used against other liabilities, and what is left as a payable amount. 

For legacy film, TV, video games and cultural reliefs

HMRC allows you to enter combined totals on CT600P, but your corporation tax computation should still show the calculation for each production separately. That is an important distinction. CT600P can aggregate; your supporting computations should not. 

A genuinely useful cross-check is the CT600 box mapping. HMRC’s manuals say the following CT600 boxes must line up with CT600P figures for a valid claim.

CT600P figureCT600 boxWhat it represents
P245541AVEC/VGEC used to discharge liabilities
P190886Payable AVEC/VGEC after redemption steps
P325540Legacy creatives tax credit used to discharge liabilities
P330885Payable legacy creatives tax credit
P310663Total creatives core expenditure for predecessor reliefs
P315665Total creatives additional deduction for predecessor reliefs
—614AVEC/VGEC surrendered to this company by a group company
—658Tick to confirm the additional information form has been completed

**HMRC’s Creative Industries Expenditure Credit Manual sets out those CT600 box links expressly. 

If you expect a payable amount, do not forget the bank details on the CT600. HMRC’s manual says payments will be made using the bank details supplied in the CT600. 

Also Read: Cross-Border VAT for Film Companies: Updated Guidance for UK Producers and Distributors

What supporting evidence must be submitted with a CT600P claim?

CT600P is only part of the filing package. Since 1 April 2024, all creative industries claims must also be backed by an online additional information form, and HMRC says that form must be submitted before, or on the same day as, the CT600. If it is late, the original claim is invalid and the return has to be amended and the claim re-submitted. 

The supporting package will usually include the following.

  • Company identifiers such as the UTR, and if applicable the VAT and PAYE references, matching the CT600. 
  • The start and end dates of the accounting period, matching the CT600 exactly. HMRC says a date mismatch can cause the additional information form to be rejected and the claim removed from the CT600. 
  • For film, TV and video games, a digital BFI certificate and the DCMS reference number on that certificate. HMRC no longer accepts the British cultural certificate as a CT600 attachment for these claims; it must now go with the additional information form. 
  • Statements of core costs, split between UK and non-UK costs, plus a breakdown of costs by category. 
  • Connected party transaction details where relevant. HMRC’s additional information rules and manuals specifically require connected-party information for relevant claims, and if the required connected-party information is not supplied, qualifying expenditure can be restricted. 
  • For AVEC/VGEC claims, a computation showing how the credit was calculated for each production and an expenditure breakdown separating core from non-core expenditure and UK from non-UK expenditure. 

If you are claiming the additional AVEC for visual effects, HMRC now wants more than a top-line figure. The updated additional information form asks for the amount of additional credit, vendor details, the cost incurred with each vendor, and the number of people engaged in qualifying VFX work. If there were more than 10 vendors, the excess vendor details must be attached separately. 

For theatre, orchestra, and museums and galleries, the evidence pack is slightly different. Touring claims need venue or performance detail, and HMRC’s updated process now allows full production detail for only up to 10 productions, with a summary section for the rest. 

How do AVEC and VGEC calculations work in practice?

AVEC and VGEC are calculated by reference to qualifying expenditure, and the figure is generally the lower of 80% of total core costs and the amount of UK core costs. Qualifying expenditure is calculated on a cumulative basis, which is why prior-period claims matter. 

For AVEC and VGEC, the gross credit is taxable, and CT600P then takes you through the statutory redemption steps. First, it is used against Corporation Tax; then the notional tax charge is worked through; then any balance may be used against other Corporation Tax liabilities, surrendered to group companies, used for other company liabilities, or paid as a cash credit if an amount remains. That is why the gross credit on the production is not automatically the cash you receive. 

A worked example makes the point. HMRC’s own example for AW Games Ltd shows a video game with £40 million of core expenditure, of which £30 million is UK expenditure. The qualifying expenditure is £30 million, because that is lower than 80% of total core costs; at 34%, the gross VGEC is £10.2 million. HMRC then notes that the payable amount depends on the company’s wider tax position and the redemption steps, not just the headline rate. 

HMRC’s AW Games exampleAmount
Core expenditure£40 million
UK core expenditure£30 million
80% of total core expenditure£32 million
Qualifying expenditure£30 million
VGEC rate34%
Gross expenditure credit£10.2 million

The figures above come directly from HMRC’s worked example. 

Two exceptions deserve separate attention. 

First, independent films can claim AVEC at 53%, but only on up to £15 million of core costs, and only where the film meets the BFI low-budget certification rules. 

Second, qualifying VFX costs for non-animated, non-independent films and for high-end TV can attract 39% additional credit and are outside the normal 80% cap, but the extra VFX credit is only claimed in the completion period or a later period. 

What are the main transitional traps, deadlines and compliance risks?

The biggest filing risk is timing

HMRC says creative industries claims should normally be made within 2 years from the end of the period of account or within 42 months from the beginning of the period of account where the period is longer than 18 months. 

For older legacy audiovisual and video games relief periods, you may still encounter the older rule allowing claims up to one year after the company’s filing date, with the newer two-year rule applying to accounting periods beginning on or after 1 April 2024. 

That time limit interacts with filing defects in an awkward way. 

If the additional information form or mandatory evidence was not in place by the date the CT600 was filed, the claim is invalid and HMRC will amend the return to remove it. If the missing material is submitted later, the company must amend the CT600 and the date of claim becomes the date of the amendment, which can matter if the statutory deadline is already close. 

Transition is the second major trap

AVEC and VGEC became mandatory for new productions from 1 April 2025 and become mandatory for all productions from 1 April 2027. Legacy film, television and video game releases, therefore, still exist for some productions, but only inside that narrowing window. A common mistake is assuming that because a claim is filed in 2026, it must automatically be under the new regime. That is wrong; the correct regime still depends on the production’s start date and the closure rules. 

The third trap is assuming all cultural claims work on a purely UK-only basis for every open period.

 From 1 April 2025, theatre, orchestra and museums and galleries reliefs moved to 40% and 45% permanent rates, and EEA expenditure stopped qualifying. But CT600P guidance still warns that in some cultural-relief cases you may need to consider European expenditure, which reflects the fact that older periods can still sit under earlier rules. Transitional periods therefore need careful handling rather than blanket assumptions. 

A final practical point: HMRC has acknowledged a small CT600P validation issue affecting some companies. HMRC says it does not affect the validity of claims, and the online service guidance is being updated as the workaround evolves, with a service update planned for April 2027. 

FAQs About CT600P Claim Guidance

Can I submit CT600P without the additional information form?

No, HMRC requires companies to submit the additional information form as part of a valid creative industries claim. Companies must submit the form before or on the same day as the CT600. If they submit it late or provide incomplete information, HMRC can amend the CT600 and remove the claim.

Does CT600P apply to amended returns as well as new claims?

Yes. HMRC’s online service guidance states that companies must complete the CT600P requirement for both new and amended claims involving one or more creative reliefs or credits. This requirement also applies to businesses correcting earlier returns after 6 April 2026.

Do I need a separate CT600P for each production?

No, not necessarily. CT600P allows combined totals for multiple productions in the same category, but HMRC says your corporation tax computations should still show the figures for each production separately. In other words, the schedule can aggregate, but your support file should not. 

What if my accounting period is longer than 12 months?

CT600P can cover only one accounting period of up to 12 months. If your period of account is longer, you will normally file more than one CT600 and HMRC expects a separate additional information form for each accounting period claimed. 

Can a company file CT600P just because another group company surrendered AVEC or VGEC to it?

Potentially, yes. HMRC’s guidance says a company can include surrendered AVEC or VGEC on CT600P even if it is not itself claiming a creative relief in that return. The recipient may also need to use CT600 box 614, and the surrendering company details should still be visible in the computations. 

Do I need an accountant to complete CT600P?

The law does not require one, but the form is technical enough that professional review is often sensible, especially where the claim mixes AVEC or VGEC with legacy reliefs, includes connected-party costs, or involves group surrender or VFX uplift. The gross credit, the CT600 entries, and the payable amount are not the same figure, and that is where self-prepared claims often go wrong. 

Need help with a CT600P claim?

If your company is making its first CT600P form for creative sector tax relief claims, the sensible next step is to review the claim before filing rather than after HMRC challenges it. At Apex, we would usually look at the corporation tax service side first, then the wider tax planning service position, and where the project overlaps with innovation expenditure, we would also check the R&D tax accountant service to make sure costs are not being pushed into the wrong regime.

If you want a second review before submission, contact us today and we can look at the claim, the evidence pack, and the CT600 mapping together.

Changes to Lower Value Tax Debts: HMRC Bank Deduction Plans

A business can fall behind with a relatively modest VAT or PAYE liability after one difficult trading quarter. Because the amount is not substantial enough to trigger immediate court action, some directors assume HMRC will give it less attention.

That assumption may become increasingly dangerous. The government is consulting on a new automated process for recovering lower value tax debts through monthly deductions from UK bank and building society accounts.

The proposals are not yet law. However, they show that HMRC wants a practical enforcement tool for taxpayers who can make payments but repeatedly ignore collection letters, calls and other contact attempts.

Quick Answer

  • The proposals are currently at the consultation stage and are not confirmed law.
  • HMRC does not presently expect the measure to cover total debts above £5,000 for individuals or £10,000 for companies, although the final limits remain undecided.
  • It would apply only after HMRC’s standard collection process had been exhausted and the taxpayer had persistently failed to engage.
  • HMRC is considering a 14-day Pre-Deduction Notice before the first monthly deduction.
  • Taxpayers could object because of an HMRC error, financial hardship, additional support needs or third-party ownership of funds.

What Are Lower Value Tax Debts Under HMRC’s Proposal?

Lower value tax debts would be established HMRC liabilities that fall within proposed upper limits and remain unpaid after repeated collection attempts. The indicative limits are £5,000 for individuals and £10,000 for companies, including accrued penalties and interest at the point HMRC considers taking action.

These figures are not final thresholds. The consultation states that the upper limits have not yet been decided and seeks views on what would be proportionate.

HMRC would consider a taxpayer’s total debt across different tax regimes rather than examining each liability separately. The measure could therefore cover a combination of:

  • Self Assessment Income Tax
  • VAT
  • PAYE and National Insurance
  • Corporation Tax
  • Stamp taxes
  • Tax penalties
  • Accrued interest

For example, a company owing £2,000 in VAT and £1,500 in PAYE would have a combined tax debt of £3,500 for the proposed eligibility test. Splitting liabilities across different taxes would not prevent them from being considered together.

Read: Employing Family Members in a UK Business: Why HMRC Is Asking Tougher Payroll Questions

Why Is HMRC Targeting Smaller Tax Debts?

HMRC is targeting smaller tax debts because many remain unresolved after letters, calls and referrals to debt collection agencies. Traditional enforcement methods can also cost too much to use efficiently against modest liabilities.

Official analysis indicates that approximately 4.8 million individuals and companies hold debts within the indicative limits. These represent around 11.5 million separate debts, with a combined value of about £4 billion.

Each year, more than 750,000 lower-value debts worth over £2 billion are returned to HMRC after debt collection agencies have been unable to secure payment. HMRC believes the absence of a scalable enforcement process may encourage some taxpayers to assume that smaller liabilities will not be pursued.

HMRC already resolves more than 95% of tax debt by value each year. Its concern is the remaining population of older debts where the taxpayer has repeatedly declined to communicate.

How Would HMRC Tackle Lower Value Tax Debts?

HMRC would tackle lower value tax debts by instructing a bank or other deposit-taking institution to make fixed monthly deductions from a taxpayer’s account. The proposed process would begin only after normal collection activity and opportunities to agree a voluntary payment plan had failed.

The likely process would be:

  1. A tax liability becomes final and remains unpaid.
  2. HMRC sends reminders and attempts to contact the taxpayer.
  3. The case may be referred to a debt collection agency.
  4. HMRC confirms that standard collection routes have been exhausted.
  5. HMRC issues a formal Pre-Deduction Notice.
  6. The taxpayer receives a final opportunity to pay, arrange Time to Pay or object.
  7. If no action is taken, HMRC instructs the bank to begin monthly deductions.

The Pre-Deduction Notice would state the debt amount, penalties and interest, proposed monthly payment, deduction date and planned payment period. HMRC is considering allowing 14 days between issuing the notice and making the first deduction.

The 14-day period is only a consultation proposal. It is not yet a statutory deadline.

Which Debts and Taxpayers Would Be Within Scope?

The proposed power would cover individuals and companies with final, legally enforceable HMRC debts who have persistently failed to engage. It would not be a first response to a recently missed payment.

The following cases would be expected to fall outside the proposed process:

  • Debts subject to an active appeal
  • Liabilities under an ongoing enquiry or compliance review
  • Recent debts still within HMRC’s standard collection cycle
  • Debts covered by an agreed Time to Pay arrangement
  • Cases already subject to another enforcement arrangement
  • Taxpayers without an identifiable UK bank or building society account
  • Overseas bank accounts

A disputed liability should not qualify merely because HMRC has issued an assessment. The amount would need to be final and legally enforceable, with the normal appeal process completed or expired.

This distinction matters. A taxpayer who disagrees with an assessment must challenge the underlying liability through the correct appeal route. Ignoring collection correspondence is not an effective way to preserve appeal rights.

What Safeguards Would Apply Before Bank Deductions?

HMRC proposes safeguards covering notice, affordability, additional support needs, objections, independent review and possible tribunal oversight. Automation would be paused where the available information suggests that human judgement is required.

The proposed safeguards include:

  • More than 10 attempts to contact the taxpayer before using the power
  • A formal notice before deductions begin
  • Opportunities to disclose financial hardship or support needs
  • Manual review by trained HMRC staff
  • The right to object before or during the payment schedule
  • An independent HMRC review of an objection
  • A possible external appeal to a tribunal or court
  • Refunds and compensation for charges caused by HMRC errors

HMRC proposes allowing objections where:

  • HMRC has made a factual or procedural error
  • The deductions would cause financial hardship
  • The taxpayer requires additional support
  • Funds in the account belong to another person
  • A joint account holder has a beneficial interest in the money

An objection would pause deductions while HMRC reviewed the case. The proposed appeal route has not been finalised, although HMRC is considering a timeframe similar to the usual 30-day tax appeal deadline.

A complaint would be different from an objection. Complaining about HMRC’s service would not automatically stop deductions, although HMRC could intervene where its investigation identified an error or serious procedural failure.

Also Read: HMRC Automatic Bank Deductions: What Beneficiaries Must Know Now

How Would HMRC Decide Whether Monthly Deductions Are Affordable?

HMRC is considering using tax records, business information and credit reference data to estimate affordable monthly payments. The final methodology has not been decided and forms a significant part of the consultation.

For individuals, HMRC might consider PAYE information, Self Assessment returns and other income records. For businesses, it could consider VAT turnover figures or recently filed accounts.

The consultation also considers applying HMRC’s existing Time to Pay affordability principle. This generally means that debt repayments should not exceed 50% of the taxpayer’s disposable income.

However, an automated assessment may not reflect current circumstances. Historical profits, turnover or PAYE data may give an inaccurate picture after redundancy, illness, loss of a customer or a sudden decline in trading.

Taxpayers would therefore need to contact HMRC promptly where the suggested payment creates hardship. Financial difficulty would not automatically exclude someone from the process if they continued to ignore HMRC.

Under the current proposal:

  • There would be no standard payment-plan length.
  • Payment periods could vary according to debt and affordability.
  • Penalties associated with the debt would stop accruing once deductions began.
  • Interest could continue until the balance was cleared.
  • HMRC is not currently proposing a fixed minimum balance that must remain in the account.

These details remain subject to consultation and could change before legislation is drafted.

How Is the Proposal Different From Existing Direct Recovery of Debts?

The proposed system would collect smaller liabilities through recurring instalments, while existing Direct Recovery of Debts normally involves holding and removing a lump sum. Existing DRD also has different thresholds and safeguards.

Under current DRD rules, HMRC can use bank information to recover established debts of more than £1,000. It must leave at least £5,000 available across the taxpayer’s accounts after placing the hold.

Existing DRD is largely manual. It involves obtaining bank information, placing money on hold and allowing the taxpayer 30 calendar days to object before funds are transferred.

The proposed lower-value system would instead:

  • Operate through regular monthly deductions
  • Be designed for high-volume use
  • Use automated eligibility and affordability checks
  • Potentially have a 14-day initial notice period
  • Apply without the existing £5,000 protected account balance, provided the instalments pass affordability checks

HMRC restarted existing DRD through a controlled test phase in September 2025 and began a wider rollout from April 2026. The new monthly instalment proposal is separate and would require legislation before HMRC could use it.

What Should You Do If You Owe Smaller Tax Debts Now?

You should contact HMRC as soon as you know that a tax payment cannot be made in full. Early engagement provides more options than waiting for the debt to move into enforcement.

HMRC may agree to a Time to Pay arrangement where the proposed payments are realistic and affordable. Taxpayers setting up a plan should prepare details of their income, regular spending, assets, savings and other tax liabilities.

Companies may also be asked how they can reduce the debt by releasing assets, obtaining finance or introducing funds. HMRC will expect a company’s proposal to address both the overdue balance and its ability to meet future tax payments.

As at 16 July 2026, the main HMRC late-payment interest rate is 7.75%, applying from 9 January 2026. The rate is linked to the Bank of England base rate and can change, so it should be checked again before publication.

Ignoring the debt can lead to:

  • Referral to a debt collection agency
  • Recovery through PAYE or pension income
  • Taking Control of Goods
  • Direct recovery from bank accounts
  • Court proceedings
  • Bankruptcy or company winding-up action in serious cases

HMRC should provide notice before taking enforcement action, but continued non-engagement substantially reduces the opportunity to agree a voluntary solution.

Where an HMRC letter appears incorrect, retain the correspondence and supporting records. Consider obtaining advice before making admissions or agreeing to a payment schedule. 

FAQs About Lower Value Tax Debts

Can HMRC Take Money From My Bank Account Now?

Yes, HMRC already has Direct Recovery of Debts powers in limited circumstances. Existing DRD normally applies where more than £1,000 is owed and at least £5,000 would remain available across the taxpayer’s accounts. The proposed automated monthly deductions for lower-value debts are separate and are not yet law.

Could HMRC Use a Joint Bank Account?

Under the proposal, HMRC would consider a joint account only where no suitable sole account existed or a sole account held insufficient funds. A non-debtor joint account holder would be able to object where the money belonged to them. The final joint-account rules have not yet been legislated.

Would a Time to Pay Agreement Prevent Automatic Deductions?

An active and agreed Time to Pay arrangement would be outside the proposed automated deduction process. Taxpayers must maintain the agreed payments and keep up with new tax liabilities. A failed arrangement could lead HMRC to reconsider enforcement options.

Would Interest Stop Once Monthly Deductions Begin?

The consultation proposes stopping further penalties associated with the debt when instalment deductions begin. It does not propose stopping late-payment interest, which may continue until the balance is cleared. The precise interest treatment should be confirmed in any final legislation.

Can I Object Because I Cannot Afford the Proposed Payment?

Yes. Financial hardship is one of the proposed grounds for objection, and an objection would pause deductions while HMRC reviewed the case. You should provide current evidence of income, essential expenditure, cash flow and other debts rather than relying on a general statement that the payment is unaffordable.

Do I Need an Accountant to Deal With an HMRC Tax Debt?

An accountant is not legally required, but professional support can help verify the liability, correct returns, prepare affordability evidence and negotiate a realistic payment proposal. Advice is particularly valuable where the debt covers several taxes, the amount is disputed or HMRC is considering enforcement action.

How Can Apex Accountants Help With HMRC Tax Debt?

Apex Accountants can review how the liability arose, reconcile HMRC’s figures, identify errors and prepare a practical proposal for payment. Where the matter involves disputed assessments or formal enforcement, our HMRC tax investigation services can support communication and representation.

The sensible next step is to address the debt before HMRC exhausts its standard collection process. Book a consultation to discuss the liability, available payment options and any urgent HMRC correspondence.

Inheritance Tax Calculation UK: How It Works in 2026

A client came to Apex Accountants earlier this year after inheriting her late father’s house and modest savings. She was convinced the estate was far too small to attract any tax. It turned out her father had also gifted a large sum to her brother four years before he died, something she knew nothing about until the executors began pulling the paperwork together. That gift changed the whole calculation. It is a scenario we see often, and it is why inheritance tax calculation UK guidance matters before families assume an estate is too small to attract tax. 

With thresholds frozen for years and property values still climbing, the inheritance tax has quietly become one of the most talked about taxes in the country. Below, we answer the questions clients ask us most, in the order the calculation actually follows.

What is the basic tax-free allowance?

Every individual has a nil rate band of £325,000. The nil rate band has been fixed at that level since 2009 and, following Budget 2025, will remain frozen until 5 April 2031. Anything left within this threshold passes free of tax.

Is there anything else?

Yes. Where a main home is left to children, grandchildren or other direct descendants, an additional residence nil rate band of £175,000 can apply, taking a single person’s threshold to £500,000. This allowance is not automatic. It only applies to the value of a qualifying home passing to direct descendants and does not extend to lifetime gifts.

What about married couples?

Any part of the nil rate band or residence nil rate band that is left unused on the first death can be transferred to the surviving spouse or civil partner. In practice, this means a couple can often pass on up to £1 million between them before tax becomes due, provided the family home goes to children or grandchildren.

Does the residence allowance taper away for larger estates?

It does. For estates worth more than £2 million, the residence nil rate band is reduced by £1 for every £2 above that threshold. Once an estate reaches £2.35 million, the residence allowance disappears completely, leaving only the standard £325,000 threshold.

What rate do inheritance tax accountants UK apply above the thresholds? 

The standard rate is 40%, charged only on the portion of the estate above the available allowances. If at least 10% of the net estate is left to charity, the rate on the taxable remainder drops to 36%, which is worth factoring in at the will drafting stage rather than after the event.

How did the gift affect the inheritance tax calculation UK families had to make? 

This is the part people underestimate most. Gifts made in the seven years before death are generally pulled back into the estate for tax purposes. This is often called the seven-year rule. If a person survives seven years after making a gift, it falls outside the estate entirely. If they do not, the gift is added back, using up the nil rate band before the rest of the estate is assessed.

Where gifts made in that seven-year window exceed the nil rate band, taper relief can reduce the rate charged, but only on the portion of tax due, not on the value of the gift itself. The reduction runs on a sliding scale: full tax applies to gifts made within three years of death, then the effective rate steps down the longer the person survived afterwards, reaching its lowest point for gifts made between six and seven years before death.

Are any gifts exempt from the start?

Several are, and they sit outside the seven-year rule altogether, as set out in GOV.UK’s guidance on gifts:

  • An annual exemption of £3,000 per tax year, which can be carried forward one year if unused
  • Small gifts of up to £250 per person, provided no other exemption was used on that person in the same year
  • Wedding gifts, with limits depending on the relationship to the giver
  • Regular gifts made from surplus income, provided the giver’s standard of living is unaffected
  • Gifts between spouses or civil partners, and gifts to UK-registered charities

Is there anything on the horizon that could change these calculations?

Yes, and it is significant. From 6 April 2027, most unused pension funds and pension death benefits will be brought within the value of a person’s estate for inheritance tax purposes, following legislation confirmed in the Finance Act 2026. Pensions have historically sat outside the estate altogether, so this change will bring a meaningful number of estates into scope for the first time and increase the liability for others. Anyone relying on their pension as a tax-efficient way to pass on wealth should review that plan with accountants for inheritance tax planning well before the change takes effect. 

Where do we come in? 

For a reliable inheritance tax calculation UK families can act on, work out the full picture before assuming an estate is too small to matter. Add together the value of the home, savings, investments, and any gifts made in the past seven years, then apply the allowances in the right order. Getting the sequence wrong, or missing a lifetime gift, is one of the most common reasons families are caught out, and it is exactly the kind of detail inheritance tax accountants UK are asked to unpick once HMRC has already raised a question. 

The better approach is to work through the calculation properly before that happens. If you are unsure how your estate would be assessed, get in touch with Apex Accountants, accountants for inheritance tax planning, for a clear, professional review. It is a straightforward conversation now, rather than a complicated one later.

Book a Free Consultation