Director Tax Return 2025/26: New Self Assessment Rules for Close Company Directors

If you run an owner-managed or family company, your director tax return 2025/26 asks for more information than ever before. From the 2025/26 tax year, HMRC requires company directors to report the company name, its registration number, the dividends they received from that company and their highest shareholding percentage. The tax you pay does not change, but every missing item can cost £60, and the details you provide now let HMRC cross-check your return against your company’s accounts. The return is due by 31 January 2027 online. Here is exactly who the rules catch, what to report and what to do before you file.

Key takeaways

  • Company directors must complete new mandatory boxes on the employment pages from the 2025/26 return.
  • For each company you direct, report the company name, Companies House registration number, dividends received from it (enter 0 if none) and your peak shareholding percentage.
  • You need a separate employment page for every directorship you held during the year.
  • File online by 31 January 2027 (31 October 2026 on paper).

Who Do the New Rules Apply To?

The rules apply to directors of close companies who already complete a Self Assessment return. If HMRC already expects a return from you and you direct a close company, the new boxes apply to you. Any director in that position, paid or unpaid, is caught by the new reporting.

A close company, in simple terms, is a UK company controlled by five or fewer participators, or by any number of participators who are also directors. Participators include shareholders and anyone with a share in the company’s capital or income, including people entitled to distributions or benefits from it. That definition covers most owner-managed, family-owned and privately held businesses in the UK, so the vast majority of owner-managed companies fall inside it.

The rules reach further than directors formally registered at Companies House. They can also apply to people who act as directors without being formally appointed, including those falling within the relevant definition of a shadow director. Even unpaid directors of dormant close companies must complete the new boxes if they are already required to file a Self Assessment return. 

What Exactly Changed on the Director Tax Return SA102 Pages?

Before this year, the pages asked optional questions about directorships.From the 2025/26 return, close company questions carry mandatory additional information requirements. For each close company where you held a directorship at any point during the tax year, you must report four things on your director tax return:

  1. The company’s full name (box 7.1).
  2. Its Companies House registration number (box 7.2).
  3. The dividends you received from that company during the year (box 7.3), including nil. If you took nothing out, you enter 0, not a blank. This figure must match the dividend income on your main return.
  4. Your highest percentage of ordinary share capital at any point in the year (box 7.4). If your shareholding changed, report the peak, not the end-of-year figure.

Alongside these new reporting requirements, directors should also review their salary and dividend planning for 2026/27 to structure future withdrawals efficiently and consider the wider impact on both their personal and company tax position. 

You also complete a separate page for each directorship, so a director with two companies files two sets of employment pages. Dividends from close companies are now separated from your other UK dividend income on the main SA100 return, which makes the cross-check between your company accounts and your personal return automatic.
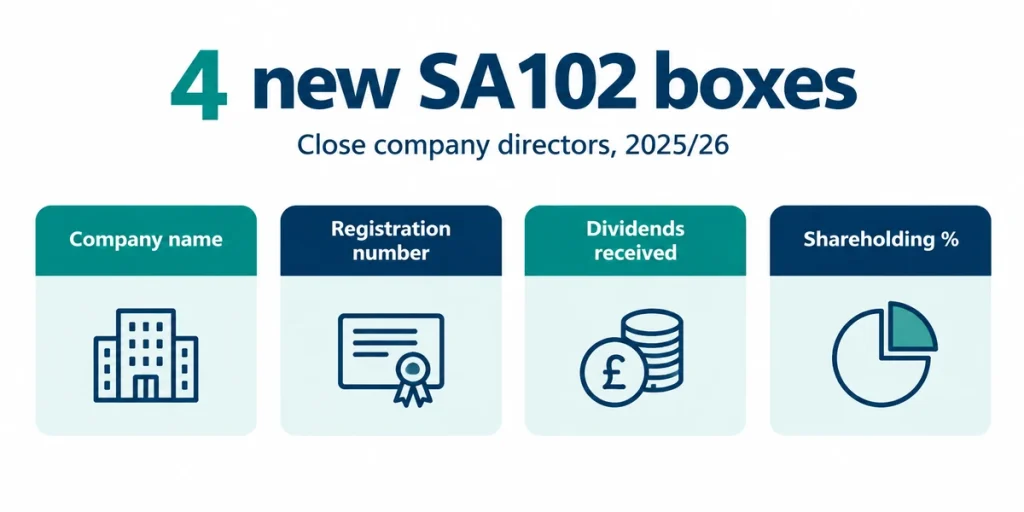
Infographic of the 4 new SA102 boxes for close company directors 2025/26: company name, registration number, dividends received and shareholding percentage.

Worked Example: Two Companies, One Return

Priya is a director of two close companies. She holds 60% of A Ltd and took £40,000 in dividends from it during 2025/26. She holds 25% of B Ltd and took nothing from it.

Her Self Assessment return requires a separate employment page for each directorship. For A Ltd, she enters the company name and registration number, £40,000 in dividends and a 60% shareholding. For B Ltd, she enters the company name and registration number, £0 in the dividend box and a 25% shareholding.

On her main return, the £40,000 sits in the dividend income section, and the 2025/26 dividend tax rules apply to it. Directors should consider reviewing how dividends interact with salary, allowances and their wider personal tax position. After the £500 Dividend Allowance, £39,500 of her dividend income remains taxable:

2025/26 tax bandDividend tax rate
Dividend allowance (first £500)0%
Basic rate8.75%
Higher rate33.75%
Additional rate39.35%

If her other taxable income has already used all of her basic-rate band, and the full £39,500 of dividends above the £500 Dividend Allowance falls within the higher-rate band, she owes approximately £13,331.25 in dividend amount of tax (£39,500 × 33.75%). 

What Should Close Company Directors Do Before Filing?

Four preparations make the new reporting straightforward:

  1. Gather every dividend voucher and board minute for each company you direct, so the dividend figure you report matches your records.
  2. Confirm your shareholding percentage for the year, including the peak if you transferred or issued shares mid-year. Alphabet shares and mid-year changes need careful calculation of the highest holding.
  3. Complete your Companies House identity verification so a mismatch does not delay your return.
  4. Reconcile your personal return against your company accounts before filing. The whole point of the new boxes is that HMRC can now compare the two automatically, so they must agree.

What Happens If You Get the New Boxes Wrong?

The new reporting requirement does not carry a separate filing charge, although taxpayers may incur software or professional-adviser costs. HMRC may charge a £60 penalty for failure to comply with the additional information requirement, regardless of the number of directorships or missing items. Standard accuracy penalties may also apply where an inaccurate return results in tax being understated and the relevant penalty conditions are met.

The context matters too. HMRC links the change to the tax gap, where small businesses account for a large share of missing revenue, and to transactions between companies and their owners. Because every close director in the company now discloses company-level details, HMRC can spot undeclared dividends and inconsistent records immediately. The professional bodies agree on the substance: the ICAEW and the ATT have both published member guidance on the new requirements.

When Are the 2025/26 Deadlines?

The 2025/26 return covers income from 6 April 2025 to 5 April 2026.Directors who still need to register should also check the Self Assessment registration deadline before preparing their return. 

 Key dates:

  • 31 October 2026: paper return deadline.
  • 31 January 2027: online return deadline.
  • 31 January 2027: payment of any tax due.

Directors who prepare dividend paperwork and shareholding records now avoid a January scramble with the new boxes.

Frequently Asked Questions

Do I complete the new boxes if I received no dividends? 

Yes. You enter 0 in the dividend box for each close company you direct. Leaving it blank counts as a missing item.

I am an unpaid director of a dormant close company. Do the rules apply to me?

Yes, if you already complete a Self Assessment return. Director status, not income, triggers the reporting.

Does every directorship need its own employment page? 

Yes. Each directorship you held at any point in the year requires a separate set of employment pages.

Does this change the dividend on tax I pay? 

No. The rules change what you report, not what you owe. Your tax on divident and other liabilities follow the existing 2025/26 rates.

What if my shareholding changed during the year? 

You report the highest percentage you held at any point in the tax year in box 7.4.

How Apex Accountants Can Help

We prepare proper Self Assessment returns for directors every January, and the new close company boxes are now a standard part of that service. Our team cross-checks your personal return against your company accounts so the dividend figures, shareholding percentages and registration numbers agree before anything reaches HMRC. 

We maintain your dividend vouchers and board minutes through our bookkeeping and company accounts services, handle salary and dividend planning for the 2026/27 year ahead, and manage multiple directorships in one place. If you direct a close company and want the 2025/26 return handled properly, contact Apex Accountants and we will take the paperwork off your desk.


What Happens to Your Personal Allowance over £100,000 Income?

For UK taxpayers asking “What happens to my Personal Allowance if I earn over £100,000?”, the answer depends on HMRC’s Personal Allowance taper rules. For the 2026/27 personal tax allowance, the standard tax-free amount remains £12,570, but it gradually reduces once adjusted net income exceeds £100,000. The allowance falls by £1 for every £2 earned above this threshold and disappears completely when income reaches £125,140. This affects employees, company directors, pensioners and anyone with multiple taxable income sources.

The issue has become increasingly relevant because frozen tax thresholds mean more taxpayers are entering higher tax bands without changes to the underlying allowances. For high earners, the taper can significantly change take-home pay and create unexpected tax liabilities if income is not planned carefully.

Key Points

  • The standard Personal Allowance for 2026/27 is £12,570.
  • The allowance reduces once adjusted net income exceeds £100,000.
  • The reduction rate is £1 of allowance lost for every £2 of additional income.
  • The Personal Allowance becomes unavailable at £125,140.
  • High earners can face an effective marginal tax rate of 60% between £100,000 and £125,140.
  • Pension contributions and income timing can affect adjusted net income.

How the Personal Allowance Taper Works for High Earners in 2026/27

The Personal Allowance is the amount an individual can earn before paying Income Tax. As part of the wider UK income tax rates system, it provides a tax-free amount for most taxpayers.

The personal tax allowance 2026/27 remains a key reference point for taxpayers because it determines how much income can be received before Income Tax applies. However, higher earners may receive a reduced allowance once their adjusted net income passes the £100,000 threshold.

For the 2026/27 tax year, the standard Personal Allowance is £12,570. It is reduced by £1 for every £2 that adjusted net income exceeds £100,000, reaching zero when income reaches £125,140.

Adjusted net income is not limited to salary. It can include:

  • Employment income and bonuses
  • Pension income
  • Rental income
  • Taxable benefits
  • Certain investment income

This means someone earning £95,000 from employment may still enter the taper zone if additional income, such as bonuses or benefits, takes their adjusted net income above £100,000.

Why More Taxpayers Are Watching the £100,000 Threshold

The personal tax allowance 2026/27 remains at £12,570 following several years of frozen thresholds. This has increased interest in searches such as UK personal allowance 2026 increase and When will the personal tax allowance increase?

The freeze means that as wages rise, more individuals may move into higher tax positions without receiving an increase in the amount of income they can earn tax-free. This has increased searches around a potential UK personal allowance 2026 increase, as taxpayers look for clarity on whether future budgets may change the current threshold.

Questions such as “Will Labour increase personal tax allowance?” also reflect wider public interest in whether future governments will change income tax thresholds. However, current rules continue to apply unless legislation changes.

Who Is Affected by the Personal Allowance Reduction

The taper mainly affects:

  • Employees with an annual income above £100,000
  • Directors receiving salary and dividends
  • Individuals with large bonuses
  • Professionals with pension income alongside employment earnings
  • People with multiple taxable income sources

Company directors are particularly affected because remuneration decisions can involve salary, dividends and pension contributions. A change in one area can alter adjusted net income and affect the amount of Personal Allowance available.

Why the £100,000–£125,140 Band Creates a 60% Tax Trap

The Personal Allowance taper creates a higher effective tax rate than many taxpayers expect.

Between £100,000 and £125,140, taxpayers lose part of their tax-free allowance while also paying Income Tax on additional earnings. This creates an effective marginal rate of 60% for affected income.

The interaction between Personal Allowance tapering and UK income tax rates means some taxpayers experience a higher effective tax cost than expected, even though the headline Income Tax bands remain unchanged.

For example, an individual earning £110,000 does not simply pay tax on the extra £10,000 above £100,000. Their Personal Allowance is also reduced by £5,000, increasing the amount of income subject to tax.

This is why high earners often review pension contributions, bonus timing and income structure before the end of the tax year.

HMRC confirms that adjusted net income above £100,000 can reduce the Personal Allowance over £100,000 Income, with the allowance withdrawn completely where adjusted net income reaches £125,140.

What UK Businesses Should Consider

For employers, the Personal Allowance taper creates payroll considerations, especially where employees receive variable pay.

Businesses should:

  • Apply HMRC tax codes correctly through payroll.
  • Inform employees when bonuses may affect their tax position.
  • Review director remuneration arrangements annually.
  • Ensure payroll systems reflect updated tax codes.
  • Encourage employees to review their HMRC records.

Employers do not calculate the Personal Allowance over £100,000 Income taper manually. HMRC provides tax codes based on individual circumstances, and businesses must apply those codes accurately.

How Can Apex Accountants Help?

Apex Accountants supports directors, businesses and high earners with tax planning and payroll advice linked to Personal Allowance changes.

We can help with:

  • Reviewing PAYE tax codes for higher earners.
  • Assessing how salary, dividends and bonuses affect tax exposure.
  • Advising directors on remuneration planning.
  • Reviewing pension contribution strategies.
  • Supporting businesses with payroll accuracy.

Our approach focuses on helping clients understand how tax rules affect real financial decisions. Call us now, and our tax experts will guide you on your personal allowance and the £100k tax trap.

Conclusion

For anyone asking “What happens to my Personal Allowance if I earn over £100,000?”, the key point is that the allowance gradually reduces after the £100,000 threshold and disappears completely at £125,140. The taper can significantly affect take-home pay, especially for directors, professionals and individuals with multiple income sources.

Understanding how Personal Allowance interacts with income, bonuses and pension planning can help taxpayers make better decisions. To review your tax position, contact Apex Accountants or book a free consultation.

FAQs

What is Personal Allowance?

Personal Allowance is the amount of income an individual can receive before paying Income Tax. For most taxpayers, this provides the first level of tax-free income before Income Tax rates apply.

Does a bonus affect my Personal Allowance?

Yes. Bonuses count towards adjusted net income and can reduce the available Personal Allowance.

Will the Personal Allowance increase in future?

Future increases depend on government policy decisions. Current thresholds remain fixed unless changed through legislation.

When does the UK Personal Allowance start to reduce?

The Personal Allowance starts to reduce when adjusted net income exceeds £100,000. It falls by £1 for every £2 above that threshold and can reduce to zero.

What is adjusted net income?

Adjusted net income starts with total taxable income and then applies specific adjustments, including certain pension contributions and Gift Aid donations. It is the figure HMRC uses for the Personal Allowance taper and some other income-related rules.

Can pension contributions affect the £100,000 Personal Allowance taper?

Some pension contributions can reduce adjusted net income, which may preserve part of the allowance. The contribution method, annual allowance and wider tax position must be checked before acting.

Can You Reclaim VAT on Transaction Fees in the UK

Most businesses ask this as a yes-or-no question, but UK VAT does not work that neatly. Whether a business can reclaim VAT on transaction fees depends on who received the service, what the transaction was for, and whether the cost links to taxable business activity rather than a passive investment or an exempt share sale.

How VAT on Deal Fees is Applied in Various Situations

Deal situationUsual VAT outcome
A trading company issues new shares to raise funds for its taxable businessOften recoverable under the normal rules, because a new share issue is not a VAT supply in itself. If the issue supports economic activity, the related VAT can be input tax, subject to partial exemption if relevant. 
A passive holding company buys shares to earn dividends or sell later for gainUsually not recoverable. Pure shareholding for dividends or capital growth is treated as investment activity, not taxable business activity. 
A holding company buys a subsidiary and supplies genuine management services for real considerationOften recoverable, but only if the holding company is the recipient of the adviser services, carries on economic activity, and makes taxable supplies. Partial exemption can still reduce the claim. 
An acquisition is a direct extension of an existing taxable tradeOften recoverable. Such as buying a competitor, a key supplier, a key customer, or a property-owning subsidiary from which the buyer intends to trade. 
A business sells existing sharesUsually restricted or blocked, because the sale of existing shares is normally an exempt supply. If the share sale is only incidental to the wider business, there are special partial exemption rules rather than an automatic full block. 
The target company incurs vendor due diligence costsRecovery can be possible for the target if the target is the actual recipient of the services and they were received for its own business. 
A deal aborts after fees have been incurredRecovery can still be possible if there is genuine, objective evidence of an intention to make taxable supplies. Failed projects do not automatically destroy recovery. 

How VAT Applies to Common Payment Processing Fees

VAT treatment can vary between payment providers and by the type of service supplied. While many financial services are VAT-exempt, technical or administrative payment-processing services do not automatically qualify for that exemption.

Businesses should therefore check the provider’s invoice, the contracting entity and the nature of each charge before treating transaction fees as recoverable input VAT.

Stripe

Stripe fees are not automatically VAT-exempt. Card-processing services can be subject to standard-rated VAT where the service is treated as taxable payment processing.

The exact VAT treatment can depend on which Stripe entity provides the service, whether the supply is made from the UK or cross-border, and the particular service being charged for. Different treatment may apply to services such as terminal hardware, platform fees, payouts or other additional features.

Where the supply is cross-border, businesses may also need to consider whether the reverse charge applies.

PayPal

Some core PayPal payment services may qualify for the VAT exemption that applies to certain financial services, particularly where the service involves the transfer or movement of funds.

However, this does not mean every PayPal charge is VAT-exempt. Additional merchant services, administrative charges and other ancillary services can have different VAT treatment.

Businesses should review the individual charge and supporting invoice rather than assuming all PayPal fees receive the same VAT treatment.

GoCardless

GoCardless generally charges standard-rated VAT on UK transaction fees. Since April 2020, its UK transaction fees have been treated as taxable supplies rather than VAT-exempt financial services.

Where VAT is correctly charged, a VAT-registered business may be able to reclaim it subject to the normal input tax recovery rules and the use of the service for taxable business activities.

Traditional Banks

Many core banking services are VAT-exempt under the financial services exemption. This commonly includes standard banking and payment services.

However, banks may also provide additional or ancillary services that are taxable. Charges for certain administrative, advisory or other non-financial services may therefore include VAT.

For VAT recovery on bank charges, businesses should check each charge individually to confirm whether VAT has actually been applied and whether it is recoverable under the normal input tax rules, rather than assuming every fee on a bank statement is VAT-exempt.

Why Payment Processing Fees Are Not Always VAT-Exempt

The VAT exemption for financial services does not automatically extend to every service involved in making or receiving a payment.

Following court decisions including Bookit and NEC, HMRC distinguishes between services that actually perform an exempt financial transaction and technical or administrative services that simply facilitate card payments. Card-handling and processing services that only enable a customer to make a payment can therefore be standard-rated at 20%.

The key point is that a transaction fee does not automatically contain reclaimable VAT. Businesses should check whether VAT has actually been charged, identify what service the fee relates to and confirm that the normal input tax recovery conditions are met before including it on a VAT return.

What Decides Whether to Reclaim VAT on Transaction Fees

Three questions usually decide the result. 

  1. Was the fee incurred in taxable business activity?
  2. Is there a direct and immediate link between that cost and taxable supplies? 
  3. Is the business claiming the VAT actually the recipient of the service?

That is why labels like “legal fee”, “corporate finance fee” or “due diligence fee” do not settle the point on their own. The same type of cost can be recoverable in one structure and blocked in another, simply because the underlying activity is different.

Importance of the Invoice Trail

A second point is often missed: the invoice trail matters. Whether the claimant contracted for the service, was invoiced, paid for it, and made use of it, while general VAT record rules also require valid VAT invoices and records that support the claim.

Using professional accounting services can also help ensure adviser invoices, payments and supporting records are captured consistently before the VAT return is prepared.

Partial Recovery for Mixed Activity

If a business has both taxable and exempt activity, it may only recover the taxable portion unless the de minimis rules help. The current de minimis limit is £625 per month on average and no more than half of the total input tax, with an in-period check and a year-end review.

Practical Takeaways

  • Decide early on the recipient entity: Decide before the first engagement letter is signed which entity should receive the service, because attribution is based on actual or intended use when the purchase is received.
  • Give the holding company a real taxable role: If a holding company is meant to recover VAT, give it a real taxable role. Genuine management services for more than nominal consideration are a strong starting point.
  • Expect partial exemption with loans: If the structure also includes interest-bearing loans, expect partial exemption to enter the picture.
  • Don’t ignore the year-end de minimis review: A claim that looks acceptable during the year can be clawed back later if the annual test fails.

Read: Court of Appeal ruling puts VAT on education grants under scrutiny 

How common deal structures are treated

Share acquisitions through a holding company

A holding company does not get recovery just because it owns subsidiaries. If it only holds shares, receives dividends and hopes for a later sale, that is investment activity, and the VAT on acquisition costs is normally not recoverable. 

The position improves where the holding company buys the subsidiary to make taxable management services for consideration. The acquisition costs of such a holding company are part of its general overheads, so the VAT can be deductible only if the holding company receives the adviser services and makes taxable supplies. 

A practical observation here is that vague plans do not help much. If the structure only contemplates charging the subsidiary “at some point later” or only if profits allow, that is weak; official case summaries and guidance both stress the need for genuine, priced services and real consideration. 

Acquisitions that strengthen an existing trade

Not every acquisition needs a separate management charge to support recovery. Share acquisition can sometimes be a direct, continuous and necessary extension of an existing taxable trade, such as buying a competitor, a key supplier, a key customer, or a property-owning subsidiary from which the buyer plans to trade. 

That is a useful point in real deals. If a trading business buys a company to reinforce its own trading operation, the fee can sometimes sit with the buyer’s existing taxable business rather than a standalone investment case. 

Share Sales and VAT

A sale of existing shares is normally an exempt supply. That is why VAT on legal and advisory fees linked directly to a share disposal is usually a problem, and a wider commercial reason for the sale does not automatically fix it.

Immediate Transaction Matters

That last point matters. Selling shares to raise money for wider taxable trading does not by itself turn the disposal fees into recoverable VAT, because the immediate transaction still matters.

Restructuring Context

There is, though, an important nuance. Some disposals in a restructuring context may fall within economic activity where the disposal is a direct, permanent and necessary extension of the taxable business, but this is fact-sensitive and should never be assumed.

Standard Partial Exemption Method

If the business uses the standard partial exemption method and a share sale is merely incidental to the main business, the value of that share sale should be excluded from the standard method calculation. The VAT on the related costs is then dealt with using normal attribution rules rather than by simply including the deal in the denominator and accepting the result.

Special Method and Residual Costs

If the business uses a special method, certain residual costs on incidental share sales must be apportioned by use. Costs such as:

  • Accountants
  • Financial advisers
  • Lawyers
  • Advertising agencies
  • Marketing consultants
  • Listing and registration services
  • Document preparation services

Share Sales Are Not TOGC

One other point saves confusion in practice: a share sale is not a TOGC. Where a limited company changes hands by way of a share transfer, the assets remain owned by the company, so there is no asset transfer to which TOGC rules apply.

Fundraising and VAT

A new share issue is treated differently from a sale of existing shares. The issue of new shares is not a supply for VAT purposes, and related VAT can be recoverable to the extent the issuer’s business generates taxable supplies.

Target-Side Fees

On the seller side, the target company’s own fees can sometimes be overlooked. Vendor due diligence and similar costs incurred by the target may be deductible where:

  • The target is the recipient of the services
  • The services were received for the target’s business

Aborted Deals

Aborted deals are not automatically lost causes either. If there was genuine objective evidence that the business intended to make taxable supplies, preparatory VAT can still be recoverable even where the project fails before those supplies are made.

A Must Read: Everything About VAT Return Deadlines in the UK

Check the Adviser’s VAT Status

Also check whether there is actually any VAT on the adviser bill in the first place.

  • Pure advice, such as advice on capital raising or defending takeovers, is taxable
  • A genuine intermediary service in a securities transaction can itself be exempt if it meets the exemption conditions

How to improve the chances of recovery before the deal closes

The biggest practical point is timing. VAT attribution is based on how the service is used, or intended to be used, when the service is received, so sloppy structuring at the start of the deal is hard to repair later. 

In real transactions, the weak spot is often not the technical rule. It is the evidence pack: the engagement letter is in one company’s name, the invoice is sent to another, and the payment comes from a third. That makes it much harder to show who really bought and used the service. 

Document or stepWhy it matters
Engagement letter in the right entity’s nameHelps show which business contracted for the service and was the recipient. 
VAT invoice in that same entity’s nameA recoverable claim needs a valid VAT invoice and records that support it. 
Payment trailOfficial guidance on recipient status looks at who paid for the service as well as who contracted and who used it. 
Board minutes, deal papers and business planThese can provide objective evidence of intended taxable supplies, especially where the deal never completes or charges begin later. 
Management services agreement with a real charging modelHelps show that services are genuine, for consideration, and more than nominal. 
Actual management invoices after completionStrong evidence that the structure reflected real taxable activity rather than a vague future intention. 
Partial exemption workingsEssential where deal fees support both taxable and exempt activity, including share sales or exempt lending. 
Six-year retention of VAT recordsVAT records generally need to be kept for at least six years. 

A final but important point is VAT grouping. Joining a VAT group does not automatically create recovery, and it does not turn passive investment activity into taxable business activity. 

Where claims usually break down

The most common failure point is assuming that “commercial purpose” is enough. It is not enough to say the deal helped the group overall; what matters is the VAT link between the cost and taxable outputs. 

Other problem areas come up again and again:

  • Passive holding activity dressed up as a business activity. Receiving dividends and holding shares is not enough on its own. 
  • Management services that are never properly priced or invoiced. A loose intention to charge later is weak evidence. 
  • Assuming a later VAT group will rescue old acquisition VAT. It does not do that automatically. 
  • Invoices and contracts sitting with the wrong entity. The claimant still needs to show it received, used and paid for the services. 
  • Forgetting the share-sale rules in partial exemption. Incidental share sales have their own treatment under both standard and special methods. 
  • Ignoring the possibility that the adviser’s own service was exempt. Pure advice is usually taxable, but some intermediary work in securities transactions can be exempt instead. 
  • Missing the annual de minimis re-test. Recovery allowed during the year can still be reversed at year end. 

A smaller but still important trap is “stewardship” or group overhead costs. Some group audit, legal, regulatory, brand defence and bid defence costs may really belong to the group as a whole, even if the holding company receives the invoice for convenience. 

How Apex Accountants Can Help Reclaim VAT on Transaction Fees

At Apex Accountants, we keep this area practical. Our focus is not just on whether VAT looks reclaimable in principle but on whether the contract, invoice trail, management model and partial exemption position actually support the claim.

We help clients with:

  • reviewing legal, due diligence, corporate finance and other transaction fees line by line
  • checking which entity should contract for, receive and pay each adviser
  • building evidence for management charges, intended taxable supplies and aborted deals
  • calculating partial exemption, de minimis and pre-registration claims
  • reviewing VAT grouping points before and after completion
  • preparing clear support packs for internal sign-off and external review

Conclusion

VAT recovery on deal fees is possible, but it is rarely automatic. The strongest claims usually involve one of two positions: the fee sits inside an existing taxable business, or the acquiring company is carrying on real taxable activity and can prove it with proper documents and real charges. 

Claims usually fail for the opposite reasons. The structure is really an investment; the fee links to an exempt share sale, the wrong entity received the service, or the paperwork does not match the story the business wants to tell. 

FAQs on VAT on Deal Fees

Can a holding company reclaim VAT on acquisition fees?

Yes, but not just because it is a holding company. Recovery normally depends on the company being the recipient of the adviser services, carrying on economic activity, and making taxable supplies such as genuine management services for consideration. 

What if the holding company only receives dividends?

That usually points the wrong way. Simply holding shares for dividends or a later capital gain as investment activity, not taxable business activity. 

Do management charges need to be real and priced?

Yes. The services need to be genuine, provided for consideration that is more than nominal, and not left as a vague future idea that may or may not be billed later. 

Does the invoice need to be in the claimant’s name?

In practice, yes, that is the safest position. Whether the claimant contracted for the service, was invoiced, paid for it and used it, and normal VAT rules also require valid VAT invoices and records to support the claim. 

Does joining a VAT group automatically fix the issue?

No. Joining a VAT group does not automatically create recovery and does not turn passive investment activity into taxable business activity. 

Can VAT on share sale fees be recovered?

Usually not in full, because the sale of existing shares is normally an exempt supply. If the share sale is only incidental to the wider business, special partial exemption rules may soften the effect, but that is not the same as an automatic full reclaim. 

Can a partly exempt business still recover all the VAT?

Sometimes. If the exempt input tax is no more than £625 per month on average and no more than half of the total input tax, the de minimis rules can allow full recovery, but the position must still be reviewed at year-end. 

Can the target company recover VAT on vendor due diligence?

It can if the target is the real recipient of the services and the services were received for the purposes of the target’s own business. 

What if the deal aborts?

A failed deal does not automatically kill the claim. Where there was genuine, objective evidence of an intention to make taxable supplies, preparatory VAT can still be recoverable even if the business never reaches the point of making those supplies. 

Can pre-registration VAT on deal fees be reclaimed?

Potentially, yes. For services, normally a six-month lookback before registration, while goods can go back four years, but only where the costs were bought for the taxable business that is now registered.

How the UK Exit Tax Proposal Could Introduce a 20% Charge for Individuals and Businesses

The proposed UK exit tax is a one-off charge, reported at around 20%, on unrealised gains in UK business and investment assets when an individual ceases to be UK tax resident. It remained a proposal only as of September 2026 — not yet law — and some reports suggest it may have been scaled back or not taken forward, though it has not been definitively ruled out in all forms. Anyone considering leaving the UK should therefore monitor Budget statements and official guidance before acting.

Chancellor Rachel Reeves has reportedly been considering a 20% “exit tax” that would apply to high-net-worth individuals (HNWIs) leaving the UK. This UK exit tax proposal would target unrealised gains on business and investment assets acquired while an individual was a UK resident. The exit tax is being discussed as part of the 2025 Budget to help cover the UK’s growing fiscal deficit.

This exit tax would impose a capital gains tax (CGT) on unrealised gains for individuals who have been UK residents and then decide to emigrate or relocate their tax residence. Such a move aims to prevent the avoidance of UK tax when wealthy individuals move their assets abroad without paying tax on the value appreciation that occurred during their time as UK residents.

What is an Exit Tax?

An exit tax is a tax that countries impose on individuals or businesses when they leave the country and cease to be tax residents. Specifically, it taxes the unrealised gains (the increase in the value of assets, such as shares, businesses, or real estate) that have occurred during the time the individual was a resident.

Exit taxes are designed to stop people from leaving a country and selling assets in a way that avoids leaving UK capital gains tax liabilities on gains that built up while they were UK residents.

Why Might the UK Exit Tax Proposal Introduce?

The UK is facing an economic challenge, and the government needs new ways to generate revenue. Here are some reasons why the 20% exit tax UK is being considered:

1. Raise Revenue

Supporters believe the exit tax could raise around £2 billion for the Treasury by taxing unrealised gains when individuals leave the country. This would help protect the UK’s tax base and prevent individuals from avoiding capital gains tax by emigrating.

  • Wealthy individuals can avoid UK CGT by simply moving abroad and holding onto appreciating assets without selling them.

2. Align with International Norms

Other countries, such as France, Canada, and the United States, already impose exit taxes on individuals when they leave. Advocates for the UK exit tax suggest that the UK should adopt a similar approach to maintain consistency with global standards and prevent wealthy individuals from leaving without paying their fair share of tax. 

3. Prevent Tax Avoidance

The exit tax is considered a tool to curb tax avoidance by wealthy individuals who may otherwise leave the country and avoid paying tax on large capital gains. By taxing unrealised gains, the UK government can ensure that these individuals pay tax on their assets while they are residents.

Why is the 20% Exit Tax UK Controversial?

While the proposal aims to raise revenue, critics argue that it could have significant negative consequences. Here are some key concerns:

1. Possible Exodus of Wealth

Business leaders, investors, and tax advisers have warned that even the discussion of an exit tax could encourage wealthy individuals to leave the UK earlier than planned. The concern is that if the tax is introduced, many individuals might accelerate their exit plans to avoid being taxed. This could lead to a reduction in investments in the UK.

2. Practical Challenges in Valuing Assets

One of the major challenges of implementing an exit tax is how to fairly value assets, especially privately held businesses or illiquid investments. Determining the market value of these assets when an individual exits the UK can be complex and subjective. There are concerns that such an approach could create administrative burdens and disputes.

3. Impact on the UK’s Competitiveness

Imposing an additional tax burden on high-net-worth individuals may discourage entrepreneurs from investing in the UK or starting businesses here. The UK already has high corporate tax rates and the highest personal tax burden in decades. An exit tax could send the signal that the UK is no longer a hospitable place for wealth creators.

What the proposal would mean in practice

If the reported 20% exit charge were introduced, it would work as a deemed disposal when an individual ceases to be UK tax resident: unrealised gains on relevant business and investment assets would be treated as if sold at market value, triggering a Capital Gains Tax–style charge. Early reporting suggested the rate would be around 20% on those gains, with the possibility of deferring payment (for example, via instalments or until the assets are actually sold), rather than requiring the full amount immediately.

Worked example: 

A UK‑resident business owner holds shares in their trading company with a base cost of £100,000 and a current market value of £500,000, giving £400,000 of unrealised gains. On ceasing UK residence under the proposal, those gains could be taxed at about 20%, implying a potential exit charge of around £80,000. Depending on the final rules, the owner might be able to defer payment – for instance, spreading it over several annual instalments or paying only when the shares are eventually disposed of – subject to interest and anti‑avoidance conditions.

What Will Be Taxed?

The exit tax would primarily target assets held by high-net-worth individuals that have appreciated in value during their time as UK residents. These could include:

  • Business assets (such as shares in private companies)
  • Real estate (if applicable)
  • Investment assets (stocks, bonds, etc.)

The tax would likely apply when the individual departs the UK, making leaving UK capital gains tax planning particularly important. Their assets could be deemed to have been sold, with tax charged on capital gains accrued during their UK residency.

How Can Apex Accountants Help?

At Apex Accountants, we specialise in helping individuals and businesses navigate complex tax changes and plans. Our services include:

  • Tax Planning – We assess your current tax position, reviewing your assets and potential exposure to an exit tax.
  • Residency & Structuring Advice – We guide you on residency status, structuring your assets in a tax-efficient manner.
  • Cross-Border Tax Advice – We offer advice on managing your global tax liabilities when relocating or moving assets across jurisdictions.
  • Budget Monitoring – We stay on top of legislative changes, advising on the best timing for asset disposals or relocation to minimise tax exposure.

Conclusion

The proposed 20% exit tax is still under consideration, but it marks a significant change in how the UK may treat wealthy individuals who decide to leave the country. The tax aims to address tax avoidance and boost revenue, but it may also lead to unintended consequences such as driving capital away from the UK and discouraging investment. As the UK’s tax system evolves, it is crucial for high-net-worth individuals and businesses to seek professional tax planning and inheritance tax planning services and advice to plan ahead.

FAQs About UK Exit Tax Proposal

1. When Would the Exit Tax Take Effect?

The exit tax is now understood to be a reported proposal only, initially discussed around the November 2025 Budget but not enacted, with later reporting suggesting it may have been scaled back or not taken forward for individuals. If introduced in future, any start date would depend on the legislative process and government decisions, typically aligning with a specified date in the Budget or the start of a tax year.

2. What Assets Are Exempt From UK Exit Tax?

Typically, primary homes and pensions are exempt from UK exit taxes in many countries. While the UK may follow this pattern, the specifics remain uncertain until the final rules are released.

3. How Can I Prepare for the Exit Tax?

To prepare, review assets with unrealised gains, consider restructuring through trusts or offshore entities, and seek advice on residency status and cross-border tax liabilities to mitigate exposure.

4. Which Countries Have an Exit Tax?

Countries such as France, Canada, the US, and Australia have exit tax regimes that tax unrealised gains when individuals leave, preventing capital gains avoidance by emigrants.

5. How Is an Exit Tax Calculated?

The exit tax would likely calculate gains on the market value of assets at departure, taxing those gains accrued during UK residency. Deferrals may apply under certain conditions.

6. Are There Any Deferrals or Exemptions?

Some countries allow deferrals or exemptions for certain assets like primary homes or pensions. While the UK may follow a similar approach, this is not confirmed yet.

UK VAT On Prize Draws Faces Scrutiny As HMRC Clarifies Tax Position

Paid entries to UK online prize draws are subject to VAT at the standard 20% rate when the entry fee buys a place in a draw rather than a free competition route. HMRC’s clarified position means operators must account for output tax on paid entries, while genuine free-entry competitions stay outside VAT. 

The UK government has confirmed that paid entries to online VAT on prize draws offering both a free and paid route will be subject to value added tax (VAT) at the standard rate, challenging the widespread assumption that such draws fall within the betting and gaming exemption. Responding to a House of Commons question tabled on 9 February, Treasury minister Dan Tomlinson stated on 17 February that HM Revenue & Customs (HMRC) “confirm that prize draws offering both paid and free entry routes are not eligible for VAT exemption and paid entries will be subject to VAT at the standard rate of 20%”. The clarification comes as the Department for Culture, Media & Sport (DCMS) prepares to implement a voluntary code of practice for prize draw operators and as the sector attracts increased regulatory and fiscal scrutiny.

Why VAT on online prize draws matters

Prize draws have become a lucrative segment of the UK online promotions market, and VAT on online prize draws is increasingly under scrutiny. Independent research commissioned by DCMS estimated that around 7.4 million adults took part in prize draws and competitions (known collectively as PDCs) in the 12 months to November 2023, spending around £1.3 billion—with a market size range of £700 million to £2.1 billion. The sector is dominated by around 400 operators and is growing rapidly, prompting concerns about consumer protection, gambling harm and tax compliance. The Treasury’s recent statement, coupled with the forthcoming voluntary code, means operators must reassess whether their ticket sales attract VAT and consider potential historic exposures.

HMRC’s Clarified Position in Brief

  • HMRC confirmation: The government has confirmed that prize draws with both paid and free entry routes are not covered by the VAT exemption for betting, gaming, and lotteries; VAT for online prize draw operators will apply at 20% for paid entries.
  • Policy trigger: The clarification followed a parliamentary question about the tax treatment of such draws, asked amid the roll‑out of the voluntary code of practice.
  • Growing market: Research shows 7.4 million participants and annual spending around £1.3 billion, with at least 401 operators, each of whom must understand VAT for online prize draw operators to avoid penalties. 
  • Exemption complexities: VAT legislation exempts facilities for betting or playing games of chance, but the supply of games of skill is standard‑rated. The classification of prize draws sits in this grey area.
  • Voluntary code: Operators signing the code must implement its player‑protection measures within six months and no later than 20 May 2026.
  • Uncertain tax treatment: Larger businesses taking a tax position inconsistent with HMRC’s “known position” must notify HMRC under the uncertain tax treatment regime.

What Has Happened with VAT on Prize Draws

A written question from Maureen Burke, Labour MP for Glasgow North East, asked the Chancellor to clarify the VAT treatment of ticket sales for online prize draws that offer both a paid and a free entry route. In the response on 17 February 2026, Treasury minister Dan Tomlinson confirmed that HMRC regards paid entries as standard‑rated supplies, meaning VAT must be charged at 20 %. The minister’s statement effectively rejects the view that such draws are exempt under Group 4 of Schedule 9 to the Value Added Tax Act 1994, which exempts facilities for betting, gaming and lotteries.

The parliamentary question reflects growing uncertainty in the sector. Many operators have treated their prize draws as VAT‑exempt on the basis that they provide a game of chance similar to a lottery. HMRC’s position draws a distinction between games of chance, which are exempt, and games of skill or commercial competitions, which are standard‑rated. The government’s clarification suggests that a dual‑entry prize draw—where free postal entries coexist with paid online tickets—does not fit neatly within the gambling exemption.

Why Prize Draws Attracted HMRC Scrutiny

Under existing HMRC guidance, supplying facilities for betting or playing games of chance is normally exempt from VAT. A game of chance involves an outcome determined wholly or partly by chance, whereas games of skill, such as certain competitions, are subject to VAT. HMRC’s VAT notice cites “spot the ball” competitions as examples; these were deemed games of chance and thus exempt after a Court of Appeal ruling in 2016. The line between skill and chance, however, is nuanced. In prize draws offering both free and paid entry, HMRC appears to consider the paid ticket sale as a taxable supply rather than a stake in a game of chance.

The value of the exemption may be substantial. Participation in games of equal chance became VAT‑exempt from 29 April 2009, and the exemption covers stakes or takings less any winnings. Operators who have not accounted for VAT on ticket sales may face assessments, penalties and interest. Moreover, under the uncertain tax treatment (UTT) regime, large businesses must notify HMRC when they take a tax position that is uncertain and exceeds a £5 million tax advantage. Treating prize draw entries as exempt despite HMRC’s stated position would therefore trigger a disclosure obligation.

Key details or changes

The voluntary code of good practice for prize draw operators, published by DCMS and updated in February 2026, contains detailed measures on player protection, transparency and accountability. Signatories must fully implement the code within six months of publication and no later than 20 May 2026, sharing best practices and supporting non‑signatories. The code prohibits operators from accepting credit card payments above £250 per month per player, requires age verification and clear complaints processes, and encourages spend limits and self‑exclusion options. While the code does not address VAT directly, it signals heightened regulatory interest in the sector.

The research commissioned by DCMS highlights the scale of the market and its proximity to gambling. An estimated 88 % of prize draw participants also engage in commercial gambling activities, compared with 60 % of adults in the general population. This connection has raised concerns that prize draws may serve as a gateway to gambling, prompting calls for tighter oversight and clearer taxation rules.

Who is affected?

  • Online prize draw operators offering paid and free entry routes are directly affected. Those who have treated entry fees as exempt may face liabilities for under‑declared VAT and should review historic transactions.
  • Businesses using prize draws for promotions, such as retailers and charities, need to consider whether entry fees constitute taxable supplies. Promotional competitions based solely on skill may remain subject to VAT; free-entry draws with no paid option are outside the scope.
  • Large corporations are subject to the uncertain tax treatment rules. If their interpretation diverges from HMRC’s position, they must disclose the uncertainty.
  • Players and consumers are unlikely to see direct tax impacts, but operators may adjust ticket prices or limit paid entries to account for VAT.

Expert Analysis 

From a tax and accounting perspective, HMRC’s confirmation narrows the scope of the betting and gaming exemption. The key determinant is whether the consideration paid by participants is a stake in a game of chance (exempt) or payment for a right to enter a competition or prize promotion (taxable). Operators offering both free and paid entry routes effectively sell a participation right. HMRC’s position aligns with the principle that a competition with a free route is not a “bet” and therefore falls outside the Group 4 exemption.

Businesses that have relied on the exemption should assess their exposure. This includes analysing whether entry fees were treated as exempt and whether input VAT recovery on related expenses (such as prizes or marketing) was restricted. Where VAT was not charged, operators may need to correct past VAT returns and negotiate time‑to‑pay arrangements with HMRC. The UTT regime adds a further layer: taking a position contrary to HMRC’s known stance—such as claiming exemption after February 2026—must be disclosed if the potential tax difference exceeds £5 million.

Why this matters for UK businesses

For operators, the immediate impact of VAT treatment for promotional competitions is financial. Charging 20 % VAT on ticket sales could significantly reduce margins and may require price adjustments or reductions in charitable donations. Businesses that fail to account for VAT risk assessments, penalties and reputational damage. Those using prize draws as marketing tools must also be aware that VAT applies where participants pay to enter; free draws with no purchase requirement remain outside the scope. Compliance obligations extend beyond VAT; operators must implement the voluntary code’s player‑protection measures by May 2026.

The clarification also underscores the need for robust tax governance. Uncertain tax positions should be documented, and businesses should engage early with HMRC to seek confirmation or apply for rulings. Transparent communication reduces the likelihood of costly disputes. In the longer term, litigation may test whether the dual-entry draw model genuinely falls outside the betting exemption, echoing the successful “spot the ball” challenge. Until courts provide further guidance, conservative treatment and disclosure will be prudent.

VAT Treatment for Promotional Competitions: What Businesses Should Do

  • Review current and historic prize draw models to determine whether entry fees have been correctly treated for VAT purposes and identify any under‑declared VAT.
  • Distinguish between games of chance and games of skill. Where an element of skill predominates, treat the supply as taxable; where it is pure chance with a stake, exemption may apply.
  • Implement the DCMS voluntary code by 20 May 2026, including spend limits, age verification and restrictions on credit card payments.
  • Assess uncertain tax treatments and notify HMRC if the tax advantage exceeds the £5 million threshold, particularly if adopting a position contrary to HMRC’s statement.
  • Seek professional advice before launching prize promotions to ensure VAT compliance and mitigate potential liabilities.

How Apex Accountants Can Support Your Business with VAT on Prize Draws and Competitions

At Apex Accountants & Tax Advisors, we offer expert guidance on VAT and indirect taxes related to prize draws and promotional competitions. Our services include:

  • VAT Reviews: Assessing your prize draw and competition models to ensure they align with the latest VAT regulations.
  • Exemption Analysis: Determining whether VAT exemptions apply and evaluating any potential historic VAT exposure.
  • VAT Registration & Return Adjustments: Supporting VAT registration, filing adjustments, and handling negotiations with HMRC.
  • Voluntary Code Compliance: Assisting with the implementation of the voluntary code, including age verification and spend limits compliance.
  • Uncertain Tax Treatment Notifications: Offering expert advice on uncertain tax treatment and helping you prepare necessary documentation.

Contact us now to ensure your business remains VAT-compliant with the latest regulations.

Conclusion

The UK government’s confirmation that paid entries to prize draws are subject to standard‑rated VAT signals a shift in the treatment of a rapidly growing sector. With millions of participants and significant sums at stake, prize draw operators must reassess their tax positions and prepare for increased compliance obligations. The forthcoming voluntary code aims to improve consumer protections, and the uncertain tax treatment regime encourages transparency. Businesses that take proactive steps to review their prize promotions, implement the code and engage with HMRC will be better positioned to manage risks and avoid costly disputes.

FAQs About VAT on Prize Draws in 2026

Are online prize draws subject to VAT? 

Yes. HMRC has confirmed that prize draws offering both paid and free entry routes are not eligible for the betting and gaming exemption; paid entries must be charged VAT at 20%.

What about free‑entry routes? 

Where entry is genuinely free and no payment is required, there is no taxable supply and VAT does not arise. The tax liability applies to the paid entry, not the free option.

Why are games of chance usually VAT‑exempt?

Group 4 of Schedule 9 to the Value Added Tax Act 1994 exempts the provision of facilities for betting or playing games of chance. A game of chance is defined as one where chance or chance and skill combined determine the outcome. However, competitions based principally on skill are standard‑rated.

When does the voluntary code come into force? 

Signatories must fully implement the code within six months of its publication and no later than 20 May 2026. The code is not legally binding but demonstrates good practice and may influence regulatory expectations.

What is the uncertain tax treatment regime? 

Since 1 April 2022, large businesses with turnover above £200 million or assets exceeding £2 billion must notify HMRC when they adopt a tax position that is uncertain and exceeds a £5 million tax advantage. Adopting a position contrary to HMRC’s confirmed view on prize draws could trigger this notification.

Do prizes attract VAT? 

For exempt betting and gaming supplies, the stake money is outside the scope of VAT and prizes are not taxable; only the net takings are exempt. Where a prize draw is taxable, any input VAT on goods given as prizes may be recoverable, subject to normal rules.

Could future litigation change HMRC’s position? 

Possibly. The 2016 “spot the ball” case demonstrated that courts may classify certain competitions as games of chance. If a court were to decide that dual‑entry prize draws are bets or lotteries, they could become exempt. Until then, HMRC’s stated position applies, and businesses should account for VAT accordingly.

Are online prize draws subject to VAT in the UK?

Yes, when entry is paid. A paid entry fee to an online prize draw is consideration for a place in the draw and attracts VAT at the standard 20% rate. Free-entry prize competitions sit outside VAT altogether.

Why are games of chance usually VAT-exempt?

Betting, gaming and lotteries as such are VAT-exempt because the law treats the stake as participation in the gambling rather than payment for a supply. The exemption falls away when a promoter charges for entries to a draw that is not a regulated lottery.

TikTok Tax Guide for UK Creators in 2026

TikTok is one of the fastest‑growing platforms for creators and small businesses. With more than a billion users worldwide, it’s now a serious income stream. A recent study found that the average Brit earning money via social media makes around £1,223 a year, which is above HMRC’s £1,000 trading allowance. Yet only 44% of people say they have registered for a self-assessment tax return, and more than half don’t realise they need to pay tax on additional income or gifted items. That gap in understanding can lead to penalties and interest. Apex Accountants work with content creators every day. This TikTok tax guide explains how monetisation works, how and when UK creators need to pay tax, what reliefs and deductions are available, and why accurate reporting matters.

How TikTok Earnings Work

UK creators monetise their TikTok channels in several ways:

Creator Fund and Creativity Program

The Creator Fund paid low rates of about £0.015–£0.075 per 1,000 views, but it has transitioned to the Creator Rewards or Creativity Program, now offering higher estimates like £0.40–£1.00 (around US $0.50–$1.20) per 1,000 qualified views for UK creators, paid monthly roughly 30 days after the month ends. Eligibility requires 10,000 followers and 100,000 views in 30 days.​

LIVE Gifts and Coins

Viewers buy coins for gifts during lives, which are converted to diamonds for creators; TikTok takes a 50%+ cut, with payouts to PayPal or bank after reaching about £50 (higher than US $10), not the lower US minimums.​

Other Income Streams

Brand deals, sponsorships, TikTok Shop sales, merchandise, and paid series subscriptions/tips are all taxable as self-employment income above £1,000 annually, often requiring self-assessment registration and potential VAT if turnover exceeds £90,000. Subscriptions typically require 10,000 followers, aligning with the summary.

Is TikTok Income Taxable in the UK?

Yes. HMRC treats earnings from TikTok as self‑employment income. The tax rules for UK TikTok creators apply to cash payments, affiliate commissions, and non-cash gifts received for promoting products. HMRC’s guidance on online platforms states that income from creating videos, podcasts or social‑media influencing counts towards your trading income, and you must declare it if your total trading income (from all side hustles) exceeds the £1,000 trading allowance. Gifts and services must be valued at their market value and included as income.

You usually don’t need to tell HMRC if all of the following are true:

  • Your total gross trading income from TikTok and all other self-employment or side-hustle activities is £1,000 or less for the tax year.
  • You may be able to use the trading allowance, provided the relevant conditions apply.
  • You do not need to complete a self-assessment tax return for another reason, and no other reporting obligation applies.

The £1,000 trading allowance applies to your total trading income, not £1,000 for each individual activity. For example, if you earn £700 from TikTok and £500 from another side hustle, your combined gross trading income is £1,200. You will normally need to register for self-assessment and report the income, subject to your individual circumstances.

2026/27 TikTok Tax Guide: What Changes for TikTok Creators?

The £1,000 trading allowance remains available for the 2026/27 tax year. However, creators with higher trading income also need to consider Making Tax Digital for Income Tax.

From 6 April 2026, MTD for Income Tax applies to sole traders and landlords whose combined qualifying income from self-employment and property was more than £50,000 in the relevant 2024/25 tax year. The threshold falls to more than £30,000 from 6 April 2027, based on 2025/26 qualifying income and to more than £20,000 from 6 April 2028, based on 2026/27 qualifying income.

Qualifying income is the combined gross income from self-employment and property before expenses. Affected creators generally need to keep digital records using compatible software, send quarterly updates to HMRC and complete the relevant end-of-period reporting. Exemptions may apply in some circumstances.

Creators who need to register for Self-Assessment should also check the relevant registration deadlines.

Worked Example: A TikTok Creator Earning £15,000

Suppose a TikTok creator earns £15,000 of gross trading income during 2026/27 and has no other income or allowable expenses. Because the gross trading income is more than £1,000, the creator will normally need to register for self-assessment and report the income.

If the creator claims the £1,000 trading allowance instead of deducting actual allowable expenses, their taxable trading profit would be £14,000. Assuming they have the standard £12,570 Personal Allowance, no other income and no other adjustments, £1,430 would be taxable at 20%. For a taxpayer in England, Wales or Northern Ireland, this would produce an income tax liability of £286.

The creator may also have a Class 4 National Insurance liability. For 2026/27, Class 4 NIC is charged at 6% on profits above £12,570 up to £50,270. On £14,000 of profits, the calculation would be £1,430 × 6% = £85.80, before considering any other relevant circumstances.

This example assumes that the creator has no other income, claims the £1,000 trading allowance and has no other adjustments. A creator with employment income, other trading income, allowable expenses, losses or different circumstances could have a different tax position. They should retain records of income and expenses and check what they need to report to HMRC.  Following this TikTok tax guide can help creators understand what income needs to be reported and what records they should retain for self-assessment.

Gifts are income too

Many creators receive free products or services in exchange for content. HMRC treats these perks as taxable income. The value you must include on your tax return is the fair market value of the item or experience. Failing to report freebies is one of the most common mistakes we see.

Digital platform reporting – HMRC can see your earnings

From 1 January 2024, TikTok has been sharing information about UK creators’ earnings with HMRC, including payouts from the Creator Fund, Creativity Program and TikTok Shop sales. Similar rules apply across many platforms and are being rolled out worldwide. HMRC uses this data to cross‑check your tax return, so it’s much harder to hide income. That’s why accurate records and timely filing are critical.

When to register and report

You need to register for Self‑Assessment if your total self‑employment income (TikTok plus any other freelance work) exceeds £1,000 during the tax year. Registration must be done by 5 October following the end of the tax year. For example, if you exceeded the allowance in the 2025/26 tax year (ending 5 April 2026), you must register by 5 October 2026.

As per tax rules for UK TikTok creators, key reporting dates:

DeadlineWhat happens
5 OctRegister for self‑assessment if you’ve never filed before.
31 JanSubmit your online tax return and pay any tax due for the previous tax year. The same date also covers the first “payment on account” for the current year.
31 JulPay the second payment on account if required.

Self‑Assessment isn’t just for income tax. It also calculates National Insurance contributions (NICs) for the self‑employed. In 2024/25, compulsory Class 2 NICs will be abolished. For 2025/26, you’ll mainly pay Class 4 NICs, charged at 6% on profits between £12,570 and £50,270, and 2% on profits above £50,270. These NICs are included in your Self‑Assessment bill.

Does HMRC check TikTok?

Yes. HMRC has powers to investigate undeclared income and will increasingly rely on data from platforms. The digital platform reporting rules mean TikTok sends UK earnings data directly to HMRC. HMRC also uses “badges of trade” to decide whether your activity is a hobby or a business, looking at factors like profit motive, regularity of transactions and commercial organisation. If your content generation looks like a business, you must pay tax. Penalties for failing to declare income can include interest and fines.

How TikTok tax is calculated

The amount of tax you pay depends on your taxable profit (income minus allowable expenses) and which tax bands your income falls into. For the 2025/26 tax year, the rates for England, Wales and Northern Ireland are:

BandTaxable incomeIncome‑tax rate
Personal allowanceUp to £12,5700%
Basic rate£12,571–£50,27020%
Higher rate£50,271–£125,14040%
Additional rateOver £125,14045%

Your personal allowance reduces by £1 for every £2 of income over £100,000, so high earners can lose the allowance entirely.

Sample calculations of tax on TikTok earnings

To illustrate, the table below shows simplified examples assuming the creator has no other income and claims actual business expenses. National Insurance is calculated using Class 4 rates (6% between £12,570 and £50,270; 2% above). Figures are rounded.

ExampleTikTok incomeAllowable expensesTaxable profitIncome‑tax dueClass 4 NICsTotal tax & NICs
Modest earner£20,000£5,000£15,000~£486~£146~£632
Growing creator£60,000£10,000£50,000~£7,486~£2,246~£9,732
High earner£120,000£20,000£100,000~£27,432~£3,257~£30,689

** These numbers are indicative only and may change as per your personal circumstances.

How the modest earner’s bill is worked out

Income of £20,000 minus expenses of £5,000 leaves a profit of £15,000. After the personal allowance (£12,570), only £2,430 is taxable. Tax at 20% on that amount is £486, and Class 4 NICs at 6% on the same £2,430 add around £146 (total ~£632). National Insurance stops once your profits fall below £12,570.

The growing creator with profits of £50,000 pays tax on £37,430 after deducting the personal allowance. All of that is in the basic rate band, so the income‑tax bill is about £7,486. Class 4 NICs at 6% on £37,430 add around £2,246 (total ~£9,732). A high earner with profits of £100,000 pays 20% on the first £37,700 and 40% on the rest, resulting in an income‑tax bill of £27,432 and Class 4 NICs of about £3,257, giving a total around £30,689.

These calculations assume all other income falls within the same tax year and that the personal allowance is fully available. In practice, your total tax depends on your overall income, any other reliefs or allowances, and payments on account. Always seek professional advice for complex situations.

TikTok Tax Relief and Deductions

You can reduce your taxable profit by claiming legitimate business expenses. HMRC allows you to deduct actual expenses or claim the £1,000 trading allowance – not both. The allowance is often useful for small creators with minimal costs, but most professionals save more by deducting specific expenses. Common deductions include:

  • Equipment and software: Laptops, cameras, smartphones, lighting, microphones and editing software.
  • Phone and internet bills: Apportion the business use of your mobile or broadband. Only the business proportion is deductible.
  • Home‑office costs: You can claim a proportion of rent, mortgage interest, utilities and council tax, or use HMRC’s simplified flat‑rate method. Beware of capital‑gains‑tax implications if you claim a permanent home office.
  • Props and materials: Clothing, make-up, craft supplies, backdrops and other items used solely for your videos.
  • Travel and subsistence: Transport to shoots, meetings or events, hotel costs and reasonable meals. Keep receipts and apportion journeys that have a personal element.
  • Marketing and subscriptions: Costs of website hosting, paid ads, design software, social‑media management tools and professional training courses.
  • Professional fees: Accountants, photographers, videographers, editors and legal advice.
  • VAT on expenses: If your total taxable turnover exceeds £90,000 (the VAT registration threshold), you must register for VAT. VAT‑registered creators can reclaim input VAT on business purchases.

Remember that mixed‑use items must be split between personal and business use, and you should maintain clear records. Gifts you receive for promotions are taxable income but not deductible as an expense; you cannot claim the cost of free products against tax.

How We Handle Your Tax Matters

At Apex Accountants, we specialise in helping influencers and digital entrepreneurs navigate the tax maze. Our personal tax services include:

  • Self‑Assessment preparation and filing: We handle your tax return, ensuring all TikTok income and allowable expenses are correctly reported.
  • Expense tracking and bookkeeping: We set up robust systems so you can capture income, gifts and receipts without stress. This protects you if HMRC questions your figures.
  • VAT registration and compliance: We assess whether you need to register and manage your quarterly returns.
  • National Insurance and pension planning: We advise on NIC obligations and help you maintain your state pension record.
  • Incorporation advice: If your earnings grow, we can advise on whether switching from sole trader to limited company would reduce your tax bill and protect your assets.
  • Tax planning and forecasting: Using your data, our personal tax services project future liabilities and suggest ways to reduce tax legally, from claiming reliefs to spreading income.

We understand the creative economy and the tax on TikTok earnings. Whether you’re a micro‑influencer or running a full‑time TikTok business, Apex Accountants provides the support you need to stay compliant and maximise your earnings.

FAQs About TikTok Tax in UK

1. Can I be employed and earn money on TikTok?

Yes. You can have a full‑time job under PAYE and still earn money on TikTok. However, PAYE does not cover your TikTok tax. If your side‑hustle income exceeds £1,000, you must register for self‑assessment and file a tax return yourself.

2. Do I need to register as a business?

If your income from TikTok or other freelancing exceeds £1,000, you must register as a sole trader with HMRC and file a tax return. Many creators operate as sole traders, but if your profits are significant, you might benefit from forming a limited company for liability protection and potential tax efficiency. Speak to an accountant to assess your situation.

3. What about VAT and TikTok?

You only need to register for VAT if your taxable turnover (including TikTok Shop sales and sponsorships) exceeds £90,000 in a 12‑month period. Once registered, you must charge VAT on qualifying supplies and submit quarterly VAT returns. Some creators voluntarily register early to reclaim input VAT on equipment.

4. Are gifts taxable?

Yes. Gifts and free services received in exchange for content count as income and must be included at their fair market value. You cannot deduct the value of gifts, but you can claim related expenses (e.g., postage for giveaways).

5. Do I pay tax on money I haven’t withdrawn yet?

UK taxes operate on an accrual basis – you pay tax on income when it is earned, not when you withdraw it. Income credited to your TikTok balance counts as taxable income even if you leave it on the platform. Keep screenshots or statements showing dates and amounts.

6. What records should I keep?

Maintain a spreadsheet or use accounting software to log all income and expenses, including the value of gifts. Create separate categories (e.g., Creator Fund, brand deals, shop sales) and save invoices, contracts and screenshots. HMRC requires you to keep records for at least five years after the 31 January filing deadline.

7. Can I claim the trading allowance and actual expenses together?

No. You must choose either the £1,000 trading allowance or your actual expenses. If your expenses exceed £1,000, it’s usually better to claim actual costs. If your costs are lower, the trading allowance can simplify reporting.

8. Does my income matter if I reinvest everything into the business?

Yes. Reinvesting earnings does not remove your tax liability. You’re taxed on profits after deducting allowable expenses, not on what you withdraw. Good recordkeeping and tax planning can help you optimise cash flow.

9. Does TikTok report creator earnings to HMRC?

Yes. Certain digital platforms have reporting obligations under UK rules introduced from 1 January 2024. Relevant platforms may collect information about sellers and service providers and report details of income and transactions to HMRC. TikTok creators should therefore keep accurate records of Creator Fund or programme payments, TikTok Shop income, gifts, affiliate commissions and brand-deal payments. HMRC can use platform information to cross-check tax returns, although receiving a platform report does not automatically mean that tax is due.

Conclusion

TikTok offers exciting opportunities, but earning money from the platform comes with tax responsibilities. UK creators must report income above the £1,000 trading allowance, keep records of cash and non‑cash payments, and understand that TikTok shares earnings data with HMRC. The amount of tax you pay depends on your profits, tax bands and National Insurance contributions. By claiming legitimate expenses, tracking gifts, and meeting deadlines, you can minimise your bills and avoid penalties. If you’re unsure about your obligations or simply want more time to focus on content, Apex Accountants can help. Contact us today to ensure your TikTok success doesn’t become a tax headache.

Are Schools Closing Because of the Private School VAT Change?

Since the private school VAT change, effective 1 January 2025, private school tuition and boarding in the UK have been subject to 20% VAT, and from 1 April 2025 most charitable schools in England lost business rates relief.

This has shifted the question from “will fees rise?” to “can even larger schools cope?” Pressure is evident across the independent school sector. Pupil numbers in England fell between January 2025 and January 2026, and several schools were removed from the register in 2024. At the same time, new schools continued to open in 2025 and 2026, showing that the sector is both being squeezed and reshaped simultaneously.

How Schools Are Affected by the Private School VAT Change 

ChangeWhen It AppliedWhy It Matters
VAT on private school education and boarding1 January 2025Core tuition and boarding fees are now standard-rated
Prepayments caughtPayments from 29 July 2024 for terms starting on or after 1 Jan 2025Paying early did not always avoid VAT
Loss of charitable business rates relief (England)1 April 2025Many schools lost the 80% mandatory discount unless an exception applied

The business rates change is significant because charitable relief had previously reduced bills by 80%. Schools focused on pupils with EHCPs generally keep this relief.

A key point is that 20% VAT does not automatically mean fees rise by 20%. Schools can reclaim input VAT, leaving an average net VAT cost of about 15% of fee income. Average fee rises of around 10%, though some schools absorb more costs and others pass on more to parents.

Read: Everything About HMRC v Colchester Institute VAT Dispute 

Why Larger Schools Are Now Affected

The pressure isn’t just about one tax. In England, there are 2,474 private schools, of which 1,127 are charities. Around 1,024 of these schools lost charitable rates relief.

  • Average extra business-rates cost: £308 per pupil in 2025/26
  • For schools with over 1,000 pupils, per-pupil increase: £288
  • Total cash impact for large schools: £374,000 per school

Even though smaller schools face higher per-pupil increases, large schools still face significant total costs, especially with staffing, estates, and borrowing commitments.

Most schools will not immediately close. They may first:

  • Use reserves
  • Cut non-essential spending
  • Raise fees

Financial pressure can build over time before a school reaches a breaking point.

Are Larger Private Schools Actually Closing?

Yes, closures are happening, but context matters. 

  • 58 independent school closures in England in 2024
  • 85 closures in 2023
  • 63 closures in 2022

This includes voluntary closures and regulatory removals. VAT alone cannot be blamed. The impact of VAT is difficult to predict in terms of how many additional closures will result.

Since 2000, England has averaged 74 closures and 83 new openings per year, showing a natural turnover. The relationship between VAT and private school closures therefore needs to be viewed alongside this longer-term pattern. 

Larger schools are under more financial pressure, pupil numbers are down, and some bigger schools are no longer shielded from challenges previously felt mostly by smaller schools.

The picture since VAT took effect on 1 January 2025 is becoming clearer. Trade and government data indicate a rise in independent-school closures and mergers in the first VAT year, with around 105 schools closing or being absorbed by January 2026, while news tracking has recorded further closures through summer 2026, including schools that cited VAT alongside falling pupil numbers and other cost pressures. 

However, the government has rejected the idea that the policy has caused a sector-wide pupil exodus, pointing to continued school openings and broader demographic trends. Department for Education figures show that independent-school pupil numbers in England fell by 3.8% to 560,300 in January 2026, the second consecutive annual decline, even as the total number of independent schools has not collapsed. This suggests genuine financial pressure but does not establish VAT as the sole cause of either falling enrolment or individual school closures. 

What Schools and Parents Should Check

Practical steps matter more than headlines.

  • Check fee packaging: Bundled tuition may have one VAT treatment, while extras like meals or transport may be separate.
  • Understand exemptions: Nursery classes made up almost entirely of children under school age remain exempt. Care-based before- or after-school clubs can also stay VAT-exempt.
  • SEND placements: VAT applies to the fee, but local authorities can reclaim it when funding an EHCP placement.
  • Treat VAT recovery technically: Partial exemption and input VAT calculations are required for most schools.
  • Use official tools: Services like “Get Information about Schools” let parents compare school finances and performance.
  • Check registration fees: Application and registration fees are treated like normal tuition for VAT purposes.

Read: Getting Your Business Ready for the Summer’s Temporary VAT Cut 

How We Help Private Schools Deal With VAT

At Apex Accountants, we support independent schools with the practical side of VAT changes:

  • VAT registration reviews and timing checks
  • Partial exemption and input VAT recovery calculations
  • Fee structure reviews for tuition, boarding, meals, clubs, and bursaries
  • Cash-flow and budget modelling for VAT and business rates changes
  • Support on restructuring, mergers, and orderly closure planning

Conclusion

The biggest mistake is to reduce this story to a simple slogan. The evidence around VAT and private school closures shows a more complex picture. VAT and the loss of business rates relief have definitely increased pressure; pupil numbers in England’s independent sector have fallen for two consecutive years, and closures continue, but this does not isolate VAT as the sole cause and does not yet prove a clear wave of private-school closures in the UK. 

A more accurate headline would be this: larger private schools are no longer protected from the same financial pressures that have already hit smaller schools, but the official evidence still points to a sector in costly transition, not a one-line collapse story. 

FAQs on Private-School Closures in UK

When did VAT start on private school fees?

From 1 January 2025, with certain prepayments made from 29 July 2024 also caught if they related to terms starting on or after 1 January 2025. 

Does VAT on fees mean schools had to raise prices by the full 20%?

No. Official estimates point to an average fee rise of around 10%, not a flat 20%, because schools can reclaim input VAT on relevant costs. 

Is the business rates change a UK-wide policy?

No. VAT on fees applies across the UK, but the removal of charitable business rates relief applies in England. 

Are larger schools always hit harder than smaller ones?

Not necessarily on a per-pupil basis: in the matched cohort, schools with more than 1,000 pupils show a lower per-pupil rates increase than very small schools, but their cash increase per school is still large. 

Are nursery classes in private schools still exempt from VAT?

Yes, where they are wholly, or almost wholly, made up of children below compulsory school age. 

What about after-school clubs and holiday clubs?

Educational extracurricular activities are taxable, but childcare-based before- or after-school clubs and holiday clubs that consist of care are exempt. 

Can local authorities reclaim VAT on private school placements?

Yes, where the placement is funded by the local authority and the school is named in the pupil’s EHC plan, the local authority can reclaim the VAT through existing processes. 

Do bursaries remove the VAT charge?

Not usually. Where a separate bursary funds part of a specific child’s fee, VAT still applies to the full fee; only a school funding its own bursary to itself is outside scope. 

Are registration or application fees also charged?

Yes. Application and registration fees that must be paid for a pupil to attend are treated the same as normal school fees for VAT. 

Do official figures prove that VAT is already causing a wave of large private school closures?

No. Official closure data mixes voluntary closures with regulatory removals, and the policy impact note says it is difficult to assess how many extra closures the measure will cause.

How many private schools have closed since the VAT change?

Independent-school closures have risen since the 20% VAT on fees took effect in January 2025, with the sharpest increases among smaller prep schools. By January 2026, around 105 independent schools had closed or merged, with further closures reported during 2026. The government maintains the change has not driven a mass pupil exodus to the state sector, and each closure decision also reflects falling rolls and cost pressures that predate the VAT change. 

When did the 20% VAT on private school fees start?

1 January 2025. Fees paid from 29 July 2024 for terms starting on or after 1 January 2025 were also caught by the anti-forestalling rules, so early payment did not escape the charge.

2026-27 VAT Fuel Scale Charges: Key Changes and What They Mean for Your Business

From 1 May 2026, the UK VAT road fuel scale charges change to cover the period to 30 April 2027. These flat-rate charges apply when a business reclaims VAT on vehicle fuel but a car is used for private travel. In practice, instead of keeping detailed mileage logs, a fixed scale charge is added to the VAT return to account for the private fuel usage. The new charges (VAT-inclusive) are set by CO₂ emission band and by the length of the VAT accounting period (1, 3 or 12 months). Businesses must start using the updated scales in the first VAT period beginning on or after 1 May 2026.

What is a fuel scale charge?

A fuel scale charge is a fixed VAT amount a business pays when it reclaims VAT on fuel that is also used for private journeys. The amount is based on the vehicle’s CO₂ emissions and the length of the VAT accounting period.
Typical 2026/27 charges include:

CO₂ (g/km)12-month charge (£)3-month charge (£)1-month charge (£)
120 or less657.00163.0054.00
1401,182.00294.0098.00
1801,708.00426.00142.00
225 or more2,297.00574.00190.00

Table: Example VAT fuel scale charges for 2026–27 (VAT inclusive).

Read: How Company Car Tax Bands Work and What You Will Pay

Who Must Use Fuel Scale Charges?

VAT-registered businesses may need to use a fuel scale charge where the business pays for fuel, the vehicle is also used privately and the business reclaims all the VAT on that fuel. The scale charge accounts for output VAT on the private-use element without requiring the business to separate every business and private journey.

Businesses can instead reclaim VAT only on fuel used for business journeys, provided they keep detailed mileage records. They can also choose not to reclaim VAT on vehicle fuel, although HMRC rules apply consistently across vehicles where this option is used.

If an employee or director pays for private fuel from personal funds and the business only reimburses or reclaims VAT relating to business mileage, a fuel scale charge will generally not be required.

If you are unsure whether reclaiming all fuel VAT and applying the scale charge is appropriate, our VAT services can help review your fuel arrangements, VAT recovery and reporting position.

Key Changes for 2026–27 VAT Road Fuel Scale Charges

The 2026–27 rates are slightly lower than in 2025–26, following official adjustments. For instance, the top band (225+ g/km) charge fell from £2,314 to £2,297 per year, and the lowest band (≤120 g/km) fell from £661 to £657 per year. All businesses using the fuel scale must switch to these new figures for any VAT period starting 1 May 2026 or later. The published guidance makes clear that “the VAT road fuel scale charges are amended with effect from 1 May 2026” and must be used from that date onwards.

How to Calculate Your Fuel Scale Charge

Identify the car’s CO₂ emission band

Check the official CO₂ figure from the vehicle logbook, the DVLA database, or the manufacturer’s certificate. If the exact figure isn’t a multiple of 5 g, round it down to the nearest 5 (e.g. 143 g becomes 140 g). If the vehicle has more than one CO₂ figure (e.g. separate figures for petrol and hybrid modes), use the lowest or the combined rating as advised.

Special case – older cars: 

Cars registered before 1997 may lack a CO₂ figure. In that case, use engine size to pick a band: up to 1,400 cc = 140 g/km band; 1,401–1,999 cc = 175 g/km band; 2,000 cc or more = 225 g/km band.

Choose period and charge:

Determine your VAT accounting period (1, 3 or 12 months). Then look up the corresponding charge for your CO₂ band. For example, a car at 125 g/km is in the 125 band, giving a charge of £246 for 3 months or £81 for 1 month (see table above).

Pro-rate if needed: 

If the vehicle was used privately for only part of the VAT period, pro‑rate the charge. Calculate the percentage of the period during which the car was used, and apply that to the scale charge. For example, if the accounting period is 12 months but the car was used only 6 months, a 50% adjustment applies. This approach is confirmed in the guidance: “record [the percentage] of the accounting period. Apply this percentage to each road fuel scale charge to get a total figure”.

Include on the VAT return

The fuel scale charge (which already contains VAT) is added to the VAT return as output tax owing on fuel. In other words, businesses reclaim input VAT on fuel normally, then add the flat scale charge to Box 1 of the VAT return for the period.

Also Read: VAT on Car Hire in the UK – What Businesses Need to Know

Worked Example: Fuel Scale Charge and Net VAT Position

Suppose a VAT-registered business has a petrol company car with CO₂ emissions of 145 g/km and submits VAT returns quarterly. Under the 2026/27 HMRC table, the three-month fuel scale charge is £311, including £51.83 of output VAT.

Assume the business also buys £900 of fuel, including VAT, during the quarter and is entitled to reclaim the full VAT of £150.

Vehicle3-month scale chargeOutput VATInput VAT reclaimedNet fuel VAT position
Petrol car, 145 g/km CO₂£311.00£51.83£150.00£98.17 net input VAT

The business therefore reclaims £150 of input VAT on the fuel but accounts for £51.83 of output VAT through the fuel scale charge, leaving a £98.17 net VAT recovery in this example.

The fuel scale charge is separate from the Benefit in Kind rules that can apply to company vehicles. Businesses assessing whether a company car remains tax-efficient can use our guide to company car tax bands and what you will pay to compare the wider tax costs before making or reviewing a vehicle decision.

Applying the Scale Charge

  • One driver per car: 

The scale charge is applied per person-car combination. Each employee or director using a company car privately incurs one charge for that vehicle. If more than one person uses the same car, each must be treated separately.

  • Multiple cars: 

Where an individual has multiple cars, apply the same steps to each vehicle. If two cars happen to fall in the same CO₂ band for the same person, HMRC notes they “should be treated as if they were one car” when calculating percentages. In practice, this rarely affects the outcome compared to treating them separately.

  • Record-keeping: 

Keep records of how each charge was calculated (CO₂ figure sources, period length, and any percentage used). This protects you in case of a VAT inspection.

  • Electric/hybrid vehicles: 

A fully electric car does not use VATable fuel, so the fuel scale does not apply. For plug-in hybrids or conventional hybrids, use the petrol/diesel CO₂ band as above.

How We Can Help You Deal with VAT on Automobiles 

  • VAT Return Support: We help businesses apply the correct fuel scale charges on each VAT return. Our team will ensure the right CO₂ band and period are used, so the fuel VAT is calculated correctly.
  • Company Car and Expenses Advice: Our experts can advise on company car tax and benefit rules. We explain the fuel scale method and alternatives (like mileage logs) so you choose the best option.
  • Record-Keeping and Compliance: We can set up simple spreadsheets or software entries to track usage percentages and keep evidence of CO₂ figures. This ensures your accounting is robust for HMRC review.
  • Proactive Updates: Tax rules change frequently. We monitor official updates (such as the new 2026/27 rates) and notify our clients promptly. You can rely on Apex Accountants to keep you compliant without surprises.

Our dedicated advisers stay current with all HMRC rules and can guide you through the fuel scale process. If you provide cars or fuel to staff, our firm can take the stress out of calculating and reporting these VAT charges correctly.

For more details or personalised support, get in touch with the Apex Accountants team. We can help you implement the new VAT fuel scale charges smoothly and ensure your VAT returns are accurate.

FAQs About Fuel Scale Charges in UK

What if fuel is paid by personal funds? 

The scale charge only applies when the company reclaims fuel VAT. If an employee buys personal fuel with no VAT reclaimed, no output tax is due.

How to find a car’s CO₂ figure? 

Check the car’s V5C logbook, or use the DVLA online vehicle checker or the manufacturer’s data. Use certificates if needed.

Q: Where do I find my car’s CO₂ figure for the scale charge table?

A: Use the figure on the car’s V5C registration certificate or the manufacturer’s official combined CO₂ emissions figure. The scale charge band is set by that figure, so an error here means the wrong output tax.

VAT on Vouchers: Single-Purpose vs Multi-Purpose Rules in the UK

Vouchers (such as gift cards, book tokens or phone top-ups) are widely used by businesses to attract and retain customers, but the rules around VAT on vouchers can be complex. Since 1 January 2019, the UK has aligned its legislation with EU rules to clarify when VAT becomes due. Under these rules, a voucher, whether physical or digital, is treated as an instrument that can be accepted as payment for goods or services up to a specified face value. However, it is important to note that money-off coupons or discount vouchers are not treated as face-value vouchers for VAT purposes. 

The key to applying the correct treatment lies in understanding whether a voucher is classified as a single-purpose voucher (SPV) or a multi-purpose voucher (MPV), as each category determines when VAT must be accounted for and how it impacts your business.

Defining Vouchers and VAT Scope

What counts as a voucher? 

A voucher gives the holder a right to redeem it for identifiable goods or services up to its face value. For VAT, this includes gift cards or e-vouchers you pay for in advance and later exchange for specific products or services. It excludes things like “money off” coupons, loyalty points, debit cards or stored-value cards without a specified redemption item.

Face-value voucher (old law): 

Previously, UK law called vouchers “face-value vouchers,” defined as tokens or stamps entitling the bearer to goods or services of the value stated. Under current law, the focus is on when the underlying supply takes place.

VAT on Single-Purpose vs Multi-Purpose Vouchers

Value-added-tax law now classifies a voucher as either single-purpose (SPV) or multi-purpose (MPV):

VAT on Single-Purpose Voucher (SPV): 

At the time the voucher is issued, the place of supply and VAT rate of the underlying goods/services are known. In other words, an SPV is tied to a specific supply at a single VAT rate. 

For example, a gift card redeemable only for standard-rated books or a phone top-up card usable only for telecom services (if those services have one rate) would be SPVs. VAT is charged immediately when the voucher is sold (issued) and on each subsequent transfer of the voucher. This means the seller accounts for VAT on the voucher’s face value upfront. If the voucher is never redeemed, the VAT still stays due – the issuer cannot escape the tax by non-redemption.

For a simple worked example, if a business sells a £60 digital voucher that can only be used for a UK service subject to 20% VAT, it would be treated as an SPV. The VAT would be £10 (£60 ÷ 6) and would be accounted for when the voucher is sold. HMRC guidance confirms that qualifying electronic vouchers can also fall within the SPV rules. 

For businesses dealing with VAT on single-purpose voucher schemes, confirming the classification before issuing or transferring vouchers can help avoid incorrect VAT reporting and unexpected liabilities.

VAT on Multi-Purpose Voucher (MPV): 

If either the place of supply or VAT rate is unknown at issue, the voucher is multi-purpose. MPVs give the customer flexibility (e.g., a tourism pass or a voucher valid at many outlets with different VAT rates). Because the eventual use is uncertain, VAT is only due when the voucher is actually redeemed for specific goods or services. 

All prior sales or transfers of the MPV are not taxable supplies, and no VAT is charged or invoice issued until redemption. For example, a “city sightseeing pass” offering access to attractions (some exempt, some zero-rated, some standard-rated) was held by a tribunal to be an MPV, so VAT was only payable when the pass was used.

Using the same £60 digital voucher example, if it can instead be redeemed for goods with different VAT treatments, such as standard-rated and zero-rated products, it would be an MPV. No VAT would normally be due when the voucher is sold. VAT would instead be determined when the customer redeems it, based on the goods or services supplied.

Key takeaway: Do you know what the voucher will be used for when it is issued?

If yes, it is a Single Purpose Voucher (SPV), and VAT is due when the voucher is sold. If no, it is a Multi-Purpose Voucher (MPV), and VAT is due when the voucher is redeemed.

When is VAT due?

For VAT on SPVs: 

VAT is due immediately when the voucher is sold (or any time it is transferred), because the VAT on the underlying supply can be determined up front. The issue or sale of the voucher is treated just like selling the actual goods or services. The seller charges VAT on the sale price of the voucher and remits it to HMRC. For example, if a £50 gift voucher for a shop’s standard-rated goods is sold, the seller accounts for £50 of VAT due at that point.

For VAT on MPVs: 

No VAT is due on the sale or transfer of the voucher itself. Instead, the VAT charge is postponed until redemption, when the actual goods/services are supplied. At redemption, the consideration is usually the face value (or last sale price) of the voucher. For example, a £50 tourism voucher (redeemable for various services) incurs VAT when the holder finally uses it to buy a museum ticket or ride a bus; the issuer (redeemer) then accounts for VAT on that £50.

Place of Supply Matters: 

For VAT, we look at where the underlying supply happens – not where the voucher was bought or sold. The HMRC guidance highlights that if a voucher can be used in multiple EU countries (or outside the UK), its place of supply can’t be known at issue, making it an MPV.

No VAT Invoice on MPVs Transfers: 

Since MPVs are not taxed until redemption, any sale or resale of an MPV is outside the scope of VAT – meaning no VAT invoice is issued by the intermediary. This also means businesses cannot claim input VAT on expenses used to buy MPVs that they later resell, because no VAT was charged on those transactions.

  • Gift Vouchers/Gift Cards: 

A gift card valid at one store (all items at one VAT rate) is typically an SPV – VAT at sale. A gift card valid at many stores or for various products/rates is an MPV – VAT at redemption.

  • Prepaid Phone Cards: 

If only used for telecom services at a known rate, it’s an SPV (VAT when sold). If it also buys transport tickets or other services at different rates, it becomes an MPV.

  • Tourist Pass (Go City Ltd): 

The Go City Ltd case (FTT Aug 2024) involved London attraction passes. The tribunal ruled these were multi-purpose vouchers because users could choose among attractions with different VAT treatments. Therefore, VAT was only due on redemption.

  • Cross-Border Digital Vouchers (M‑GbR vs Finanzamt O): 

The EU’s Court of Justice (Apr 2024, C-68/23) decided on German video content vouchers (redeemable only in Germany but sold elsewhere). It held they were SPVs (use limited to one country), so VAT was due on each resale of the voucher. This highlights that even cross-border sales are taxed as SPVs if their actual use was fixed.

Key Points for Businesses

  • Classify correctly: 

Misclassifying an SPV as an MPV (or vice versa) can lead to under- or over-paying VAT. Always check what goods/services the voucher can buy and where they’ll be supplied.

  • Tax point and accounting: 

For SPVs, account for VAT at sale; for MPVs, only at redemption. This affects invoices, bookkeeping and cash flow.

  • VAT recovery: 

Only supplies that incur VAT allow the seller to reclaim input tax. Since MPV transfers are VAT-free, the seller cannot recover VAT on those transactions.

  • Multi-country or multi-rate vouchers: 

If a voucher can be spent in different countries or on items with different VAT rates, it’s very likely an MPV. For example, vouchers accepted in several EU member states are MPVs because the place of supply was not known at issue.

  • Review schemes regularly: 

The VAT rules on vouchers are complex and have evolved with recent cases. Businesses should review any voucher schemes (especially new ones) and seek expert advice if unsure.

How We Help Businesses Deal With VAT on Vouchers

The rules in Schedule 10B of the VAT Act 1994 determine how qualifying vouchers are treated for VAT purposes. If your business issues digital vouchers, gift cards or vouchers covering different products or locations, our VAT specialists can review the arrangement and help determine the correct SPV or MPV treatment before VAT returns are submitted. 

At Apex Accountants, we help businesses navigate VAT rules on vouchers and beyond. Our VAT specialists can:

  • Advise on SPV vs MPV classification for your voucher schemes.
  • Ensure you apply the correct VAT treatment and timing.
  • Assist with invoicing and bookkeeping entries for voucher transactions.
  • Review cross-border voucher sales and place-of-supply implications.
  • Help recover VAT correctly and plan cash flow.

We provide VAT compliance and advisory services tailored to your business, including international and digital services VAT. Our team stays up-to-date on the latest legislation and cases, so you can focus on your business.

Conclusion

Voucher schemes are a useful marketing tool, but the VAT rules are intricate. Since 2019, UK law has followed EU principles: single-purpose vouchers (known final supply) trigger VAT on issue, whereas multi-purpose vouchers (uncertain use) only incur VAT on redemption. Recent tribunal and CJEU cases reinforce these principles. To avoid errors, businesses should carefully assess their vouchers’ characteristics and get specialist guidance.

If you’re using or planning voucher-based promotions, speak to our VAT experts at Apex Accountants. We can clarify the rules, assess your setup, and ensure your VAT treatment is spot-on.

FAQs: VAT Treatment of Vouchers in the UK

1. How does VAT work on vouchers?

VAT depends on the type of voucher. Single-purpose vouchers are taxed when issued, since VAT treatment is already known. Multi-purpose vouchers are taxed only when redeemed because the final supply and VAT rate are not determined earlier.

2. Can you claim VAT back on a gift voucher?

It depends on the voucher type. For multi-purpose vouchers, no VAT is charged on purchase, so there is nothing to reclaim. For single-purpose vouchers, input VAT may be recoverable if the underlying expense qualifies under normal VAT rules.

3. Are vouchers tax exempt?

Vouchers are not automatically tax exempt. Their VAT treatment depends on how they are structured. Some transactions may be outside the scope of VAT initially, but VAT will usually apply either at issue or redemption, depending on the voucher type.

4. Are vouchers goods or services?

For VAT purposes, vouchers are not treated as goods or services. Instead, they represent a right to receive goods or services in the future. VAT is applied to the underlying supply, not to the voucher itself in most cases.

5. What is HMRC’s approach to VAT on gift vouchers?

HMRC classifies vouchers into single-purpose and multi-purpose categories. The key factor is whether the VAT rate and place of supply are known at issue. This classification determines when VAT must be accounted for under UK legislation.

6. Do digital gift vouchers follow the same VAT rules as physical vouchers?

Yes. Qualifying digital and electronic vouchers generally follow the same VAT rules as physical vouchers. Their treatment depends on whether they meet the conditions for a single-purpose voucher or multi-purpose voucher, rather than whether they are issued digitally or on paper.

7. Are gift vouchers VAT exempt or zero-rated?

Gift vouchers are usually neither exempt nor zero-rated. Their treatment depends on whether they are single-purpose or multi-purpose. VAT may be due at issue or redemption, rather than applying a specific exemption or zero rate.

8. How does VAT apply to gift vouchers for employees?

Employers usually cannot reclaim VAT on multi-purpose vouchers, since no VAT is charged at purchase. For single-purpose vouchers, recovery may be possible, but business gift rules may require output VAT if values exceed £50 per person annually.

9. What is a single-purpose voucher for VAT?

A single-purpose voucher is one where the place of supply and VAT rate are known when issued. VAT is charged at the point of sale and on each transfer, with no additional VAT due when it is redeemed.

10. What are multi-purpose vouchers for VAT?

Multi-purpose vouchers are those where the VAT rate or place of supply is unknown at issue. VAT is not charged when sold. Instead, VAT is accounted for when the voucher is redeemed for goods or services.

11. How is VAT applied to discounts and vouchers?

Where vouchers are used as payment, VAT is usually calculated on the amount actually paid or redeemed. If a voucher is sold at a discount, VAT is often based on the discounted value when goods or services are supplied.

12. What happens to VAT if a voucher is never redeemed?

For a single-purpose voucher, VAT is generally accounted for when the voucher is issued or transferred, so non-redemption does not normally remove the VAT already due. For a multi-purpose voucher, VAT is generally due only when it is redeemed, meaning an unused MPV would not normally trigger VAT on the underlying supply.

Book a Free Consultation