Is the UK Tax System Too Complex for Small Businesses in 2026?

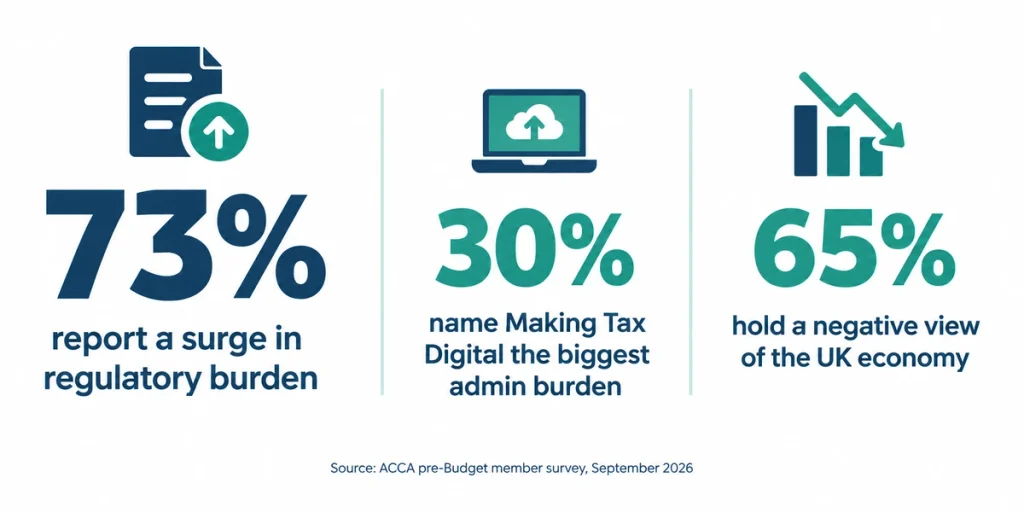
For many small businesses, keeping up with tax now means managing several filing cycles, digital reporting requirements and separate payment deadlines at the same time. A September 2026 member survey by ACCA, which represents more than 100,000 UK members, found that 73% of respondents said their regulatory requirements had surged over the previous 12 months. Making Tax Digital (MTD) was named the single biggest negative administrative burden by 30%.

The survey does not change any tax rules. However, it highlights a wider issue for small businesses: tax complexity carries a practical cost in time, systems and the risk of missed obligations.

Key Takeaways:

  • 73% of ACCA respondents said regulatory requirements had increased sharply over the previous 12 months.
  • Making Tax Digital was the biggest single administrative concern, cited by 30%, followed by reporting duplication at 10% and wider regulatory complexity at 8%.
  • MTD for Income Tax became mandatory from April 2026 for qualifying sole traders and landlords with income above £50,000.
  • There is currently no planned MTD for Corporation Tax rollout. Corporation Tax is being modernised separately.
  • A central compliance calendar, accurate digital records and suitable accounting software can reduce the risk of deadlines being overlooked.

What Did the ACCA Survey Find?

ACCA surveyed its UK members ahead of the next Budget to understand the pressures affecting businesses and the profession.

Alongside the 73% reporting increased regulatory requirements, 65% of respondents held a negative view of the UK economy, while only 4% were positive. The comparable positive figure was 29% in 2023.

When respondents were asked about administrative burdens, 30% selected Making Tax Digital as the biggest negative burden with little end-user benefit. General reporting duplication followed at 10%, systemic regulatory complexity at 8%, upcoming employment law changes at 7%, and Companies House verification processes at 7%.

There was some improvement in attitudes towards HMRC service levels. In August 2024, 89% of respondents said HMRC service problems negatively affected their organisation’s productivity and efficiency. By August 2026, that figure had fallen to 54%, although it still represented more than half of respondents.

ACCA has called for a wider review of the tax system and argued that simplifying tax administration could reduce errors and compliance costs while giving businesses greater certainty. These are recommendations to the government rather than confirmed changes to the rules businesses currently follow.

Why Is the UK Tax System So Complex for Small Businesses?

One reason is that businesses rarely deal with a single tax obligation.

A limited company may need to manage Corporation Tax, VAT, PAYE, National Insurance, benefits in kind, Companies House filings and, depending on the director’s circumstances, personal Self Assessment. Sole traders can face their own combination of trading income, property income, VAT and Self Assessment requirements.

Each regime also works to a different timetable. Understanding whether you need to register for Self Assessment is only one part of the picture, while limited companies must separately keep track of their Corporation Tax payment and filing deadlines.

Employers add another reporting cycle because payroll information generally has to be reported to HMRC on or before employees are paid. For businesses without an internal payroll function, outsourcing payroll administration can also reduce the number of recurring compliance tasks handled by the owner.

The difficulty is therefore not necessarily one individual deadline. It is keeping several different systems, dates and reporting requirements aligned throughout the year.
How Does Making Tax Digital Add to the Burden?

Making Tax Digital requires affected taxpayers to maintain digital records and use compatible software to make specified submissions.

MTD for VAT has applied to VAT-registered businesses for several years. MTD for Income Tax entered its mandatory phase on 6 April 2026 for sole traders and landlords whose qualifying income from self-employment and property exceeded £50,000 on their 2024/25 tax return.

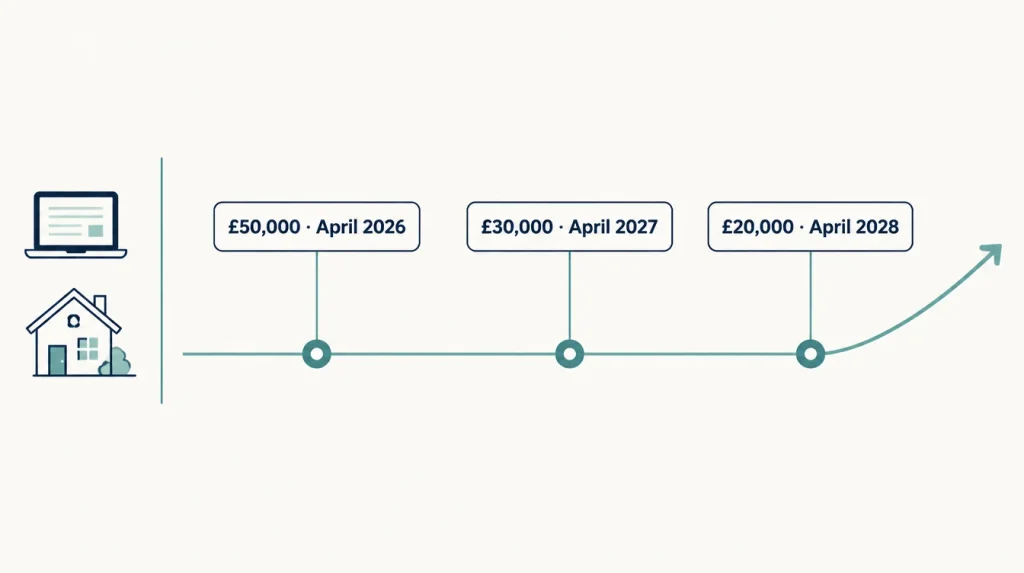
Under the current MTD for Income Tax timetable, the threshold falls to more than £30,000 from April 2027 and more than £20,000 from April 2028.

For taxpayers who entered MTD for Income Tax in April 2026, the quarterly submission deadlines for the 2026/27 tax year are:

  • 7 August 2026
  • 7 November 2026
  • 7 February 2027
  • 7 May 2027

The first MTD quarterly update therefore had a fixed deadline of 7 August 2026 rather than a date individually set when a taxpayer joined.

HMRC has also confirmed that penalty points will not be applied for late quarterly updates during the 2026/27 tax year. Quarterly updates must still be submitted before the taxpayer can complete their annual tax return.

Importantly, businesses should not assume the same MTD model is being extended to Corporation Tax. HMRC’s current transformation programme says MTD will not be introduced for Corporation Tax. Instead, the Corporation Tax system and company tax return process are being modernised separately.

What Tax Deadlines Does a Small Business Face?

A typical small business can deal with several different deadlines during the same year.

ObligationTypical DeadlineFrequency
Self Assessment online return and balancing payment31 JanuaryAnnual
VAT return and paymentUsually 1 month and 7 days after the VAT period endsUsually quarterly
Corporation Tax paymentUsually 9 months and 1 day after the accounting period endsAnnual
Company Tax ReturnUsually 12 months after the accounting period endsAnnual
Private company accounts to Companies HouseUsually 9 months after the company year endAnnual
PAYE reportingOn or before each paydayEach pay run
PAYE and NIC payment to HMRCUsually by the 22nd of the following month when paying electronicallyMonthly or quarterly
MTD for Income Tax quarterly update7 Aug, 7 Nov, 7 Feb and 7 May for 2026/27Quarterly
P60Given to eligible employees by 31 MayAnnual
P11D, where applicable6 July following the end of the tax yearAnnual

The exact dates can vary according to the business and its circumstances. The broader problem is that several obligations can overlap, particularly for businesses that are VAT registered, employ staff and operate through a limited company.

What Happens If You Get It Wrong?

Different taxes have different penalty regimes, so it is important not to treat them as interchangeable.

Under the current Self Assessment late-filing rules, an online return filed after its deadline normally attracts an initial £100 penalty. If it remains outstanding for more than three months, additional daily penalties of £10 can apply for up to 90 days. Further penalties can arise after six and 12 months.

VAT operates differently. A late VAT return normally results in a penalty point. Once the relevant points threshold is reached, a £200 financial penalty can apply, with additional £200 penalties for subsequent late submissions while the business remains at the threshold.

Late private-company accounts filed at Companies House can attract a £150 penalty when they are up to one month late, with the amount increasing the longer the delay continues. Corporation Tax, VAT and other late tax payments can also attract interest and, depending on the regime, additional late-payment penalties.

For MTD for Income Tax, the position is different again. HMRC has introduced a points-based system, but it has confirmed that late quarterly updates will not receive penalty points during the 2026/27 tax year.

How Can Small Business Owners Cut the Admin Burden?

You cannot control the number of UK tax rules, but you can make your own compliance process easier to manage.

  1. Keep one compliance calendar. Put your VAT, Corporation Tax, Companies House, payroll, Self Assessment and MTD dates in the same system rather than monitoring them separately.
  2. Use compatible accounting software. Keeping records digitally throughout the year is much easier than reconstructing transactions immediately before a reporting deadline.
  3. Review obligations before thresholds are crossed. VAT registration, MTD and other requirements can change as turnover or qualifying income grows.
  4. Keep business and personal records separate. A dedicated business account and consistent bookkeeping make transactions easier to classify and reconcile.
  5. Decide which tasks should stay in-house. Some businesses can manage straightforward bookkeeping themselves, while others may find that outsourcing accounting work makes more sense once VAT, payroll, company filings and tax returns begin to overlap.

Frequently Asked Questions

Is the UK tax system too complicated for small businesses?

There is no single objective measure of whether a tax system is “too complicated”, but ACCA’s September 2026 survey shows significant concern among accountancy professionals. Some 73% of respondents reported a surge in regulatory requirements, while MTD, duplicated reporting and wider regulatory complexity were among the most commonly cited administrative burdens.

What is the biggest admin burden for small businesses?

In ACCA’s survey, Making Tax Digital was the most frequently selected negative administrative burden, cited by 30% of respondents. Reporting duplication followed at 10% and wider regulatory complexity at 8%.

Do small businesses have to use Making Tax Digital?

MTD for VAT applies to VAT-registered businesses unless an exemption applies. MTD for Income Tax is being phased in according to qualifying income from self-employment and property. It became mandatory from April 2026 for qualifying income above £50,000, with thresholds of more than £30,000 from April 2027 and more than £20,000 from April 2028.

Can I reduce tax admin without hiring an accountant?

Yes. Good bookkeeping, compatible software, a central deadline calendar and regular reconciliations can significantly reduce routine administration. Professional support may become more useful where several taxes overlap, the business is growing, or decisions require tax judgement rather than simple data entry.

What happens if I miss a Self Assessment deadline?

Under the ordinary Self Assessment late-filing rules, the initial penalty is normally £100. Additional daily penalties can begin after three months, with further charges after six and 12 months. Filing the outstanding return and paying any tax due as soon as possible can prevent further penalties and interest from accumulating.

How Apex Can Help

Managing several tax obligations at once can take attention away from running your business. Our outsourced accounting support can bring bookkeeping, VAT, payroll, year-end accounts and tax compliance into a more coordinated process.

If Making Tax Digital is creating additional work, we can help set up compatible cloud accounting, maintain digital records and keep quarterly submissions organised throughout the year.

Compliance is only one side of the picture. Effective business tax planning can also help you make appropriate use of available allowances and reliefs while keeping your approach within current UK tax rules.

If you have already missed a deadline or received a penalty, we can review the position, identify any available grounds for an appeal and help bring outstanding filings back up to date.

Book a free consultation, and we can map your business’s main tax and filing deadlines into one practical compliance plan.
Payrolling Benefits in Kind: What Employers Must Do by 2027

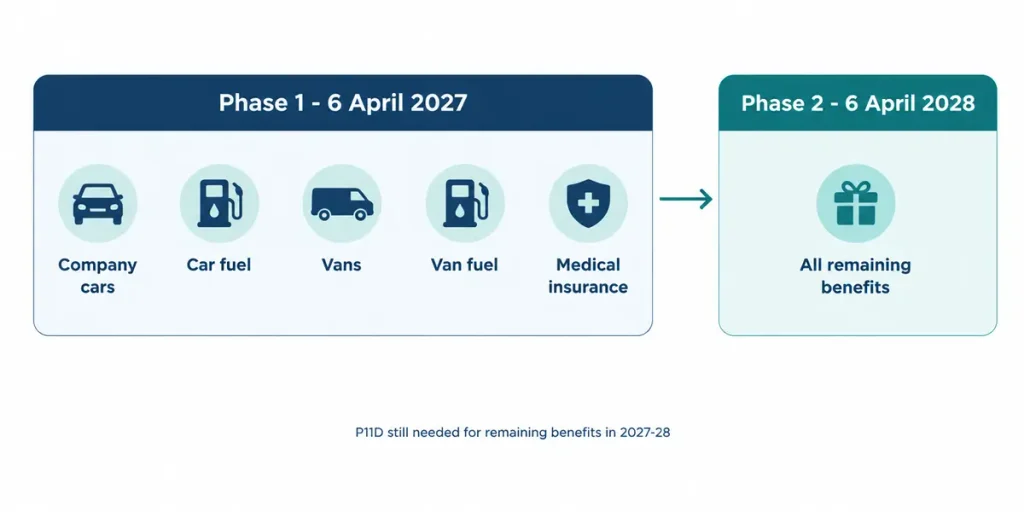
From 6 April 2027, the way UK employers report some benefits in kind will change significantly. Company cars, car fuel, vans, van fuel and employer-provided medical benefits will have to be reported through payroll in real time rather than through the usual year-end P11D process.

Most other benefits will follow from April 2028. However, employment-related loans and accommodation are currently excluded from mandatory payrolling and will remain voluntary until the government confirms otherwise.

For businesses providing taxable benefits to employees, preparation should start well before April 2027.

Key takeaways

  • Mandatory payrolling starts on 6 April 2027 for company cars, car fuel, vans, van fuel and employer-provided medical benefits.
  • Most other benefits in kind become mandatory from April 2028.
  • Employment-related loans and accommodation remain outside mandatory payrolling for now.
  • Both Income Tax and employer Class 1A National Insurance contributions will be reported in real time for mandatorily payrolled benefits.
  • P11Ds will still be required for benefits that remain outside mandatory payrolling.
  • Employers do not need to register for the benefits that become mandatory in April 2027.
  • HMRC plans to remove affected benefits from employees’ tax codes before mandatory payrolling begins.

What is payrolling of benefits in kind?

Payrolling benefits in kind means including the taxable value of an employee’s benefit in each payroll run instead of relying on year-end reporting.

For example, if an employee receives a medical benefit worth £600 for the year, the employer would normally include £50 of taxable benefit in each monthly payroll period. That amount is added for Income Tax purposes rather than being additional cash paid to the employee.

HMRC’s current mandatory payrolling guidance confirms that employers will report affected benefits through payroll software using Real Time Information.

Employers have been able to payroll certain benefits voluntarily for several years. From April 2027, however, payrolling becomes compulsory for the first group of benefits.

What changes from 6 April 2027?

The original mandatory payrolling start date was April 2026, but the government delayed implementation to provide employers, agents and payroll software developers with more time to prepare.

From 6 April 2027, mandatory payrolling applies to:

  1. Company cars
  2. Car fuel
  3. Vans
  4. Van fuel
  5. Employer-provided medical benefits, including relevant private medical cover

These benefits must be reported through the employer’s Full Payment Submission. HMRC’s reporting requirements confirm that the taxable benefit and associated Income Tax and Class 1A National Insurance contributions will be reported in real time.

Employers operating company car schemes should pay particular attention to data quality. The taxable benefit can depend on factors including the car’s list price, CO₂ emissions, fuel type and availability. Our guide to company car tax bands explains how the taxable value is calculated.

What happens from April 2028?

From April 2028, mandatory payrolling is expected to extend to most remaining benefits in kind.

There is an important exception. Employment-related loans and accommodation are not currently scheduled to become mandatory in April 2028. HMRC says these benefits will remain available for voluntary payrolling, with any future mandatory date to be confirmed separately.

Employers should therefore avoid treating April 2028 as the complete abolition of the P11D system.

Timeline of mandatory payrolling: Phase 1 from 6 April 2027 covers company cars, car fuel, vans, van fuel and medical insurance; Phase 2 from 6 April 2028 covers all remaining benefits; P11D still needed for remaining benefits in 2027-28

What happens to P11D forms?

P11Ds will not disappear in April 2027.

For the 2027/28 tax year, benefits outside phase one will generally still need to be reported under the existing year-end arrangements unless they are voluntarily payrolled.

This means a business providing company cars and private medical benefits alongside another non-mandatory benefit could payroll the cars and medical benefits throughout 2027/28 while continuing to report the other benefit after the tax year.

Even after April 2028, P11D and P11D(b) reporting can continue to be relevant for benefits such as loans and accommodation that have not been voluntarily payrolled, as well as certain excluded cases.

Class 1A National Insurance also changes. The employer remains responsible for the contribution, but for mandatorily payrolled benefits it will be calculated, reported and paid through the real-time process rather than solely through the traditional year-end P11D(b) route.

What employers should do now

1. Review and clean benefit data

Benefit records should be checked well before the first mandatory payroll run.

For company cars, make sure information such as list price, registration details, CO₂ emissions, fuel type, employee availability dates and changes during the year is accurate.

For medical benefits, employers need reliable information about the taxable cost attributable to each employee.

Incorrect data can lead directly to incorrect payroll calculations.

2. Do not register for mandatory benefits

Employers do not need to register to payroll company cars, car fuel, vans, van fuel or medical benefits from April 2027.

HMRC’s preparation guidance states that these benefits will enter mandatory payrolling automatically.

A voluntary registration service is instead due to open in November 2026 for employers wishing to payroll benefits that are not mandatory during phase one. The registration deadline for the 2027/28 tax year is 5 April 2027.

3. Check your payroll software

Employers should confirm that their software provider will support the additional benefit-in-kind information required through RTI.

HMRC expects updated technical specifications to be available to software providers in autumn 2026. Businesses using outsourced payroll services should also confirm how their provider will collect benefit information and handle changes during the tax year.

4. Brief employees before April

Employees may notice the tax on benefits more clearly through their regular payslips once payrolling becomes mandatory.

Explaining the change beforehand can reduce queries, particularly for employees receiving company cars or medical benefits.

HMRC has said it will automatically remove mandatorily payrolled benefits from affected employees’ tax codes for the start of the 2027/28 tax year, helping prevent the same benefit being taxed through both the code and payroll.

5. Prepare for changes during the year

Benefits do not always remain unchanged for 12 months.

A company car may be replaced, an employee may join or leave midway through the year, or the taxable cost of a medical benefit may change. HMRC’s real-time approach allows the annual taxable value to be recalculated and the remaining amount spread across the remaining pay periods.

Employers should establish a process for passing these changes to payroll quickly.

6. Plan for the Class 1A NIC cash-flow overlap

There is also a one-off cash-flow consideration in 2027.

Employers may still have Class 1A National Insurance to pay in July 2027 for benefits provided during 2026/27, while simultaneously starting to pay Class 1A NIC in real time on benefits provided during 2027/28.

Businesses should account for this overlap when planning payroll-related cash flow.

A worked example: payrolling a company car

Assume a director has a company car with an annual taxable benefit of £6,000.

Under mandatory payrolling, the employer would normally spread that amount across 12 monthly pay periods:

£6,000 ÷ 12 = £500 taxable benefit per month

If the employee pays Income Tax at 20%, the additional tax attributable to the benefit would be £100 per month. At a 40% Income Tax rate, it would be £200 per month.

The £500 is not additional salary paid to the director. It is included in the payroll calculation so the appropriate tax can be collected as the benefit is provided.

If the car changes during the year and the annual taxable value changes, the employer recalculates the benefit, deducts the amount already payrolled and spreads the remaining taxable amount over the remaining pay periods.

Does this change business expenses?

Ordinary business expenses that are paid or reimbursed and qualify fully for tax relief remain exempt and normally do not need to be reported as benefits in kind.

Different rules can apply where an expense is taxable or does not qualify fully for relief. Employers should therefore distinguish between genuine business expenses and taxable employee benefits rather than treating all expense payments in the same way.

Employees may also be able to claim tax relief on qualifying work-related expenses where the relevant conditions are met.

FAQ

Is the P11D being abolished?

Not completely.

P11Ds will stop being the normal reporting method for benefits brought into mandatory payrolling, but they will continue to have a role for benefits and circumstances that remain outside the mandatory regime.

Loans and accommodation, for example, are currently expected to remain voluntary even after April 2028.

Can I start payrolling before it becomes mandatory?

Existing voluntary arrangements can continue where an employer registered in time for the 2026/27 tax year.

For 2027/28, HMRC plans to reopen voluntary registration in November 2026 for benefits that are not part of the mandatory phase-one group.

There is no need to register company cars, car fuel, vans, van fuel or medical benefits for April 2027 because those categories become mandatory automatically.

What happens if I do nothing before April 2027?

Employers providing benefits covered by phase one will still be required to report them through payroll from 6 April 2027.

HMRC has announced a first-year easement for certain non-deliberate inaccuracies in mandatory RTI reporting during 2027/28. However, deliberate non-compliance is not protected, and normal late-filing, late-payment and statutory interest rules can still apply.

Businesses should therefore use the remaining preparation period to review their records, software and payroll procedures.

Will employees be taxed twice?

HMRC says it intends to remove the mandatorily payrolled benefits from affected employees’ tax codes before 6 April 2027.

Employers should nevertheless make sure benefit information is accurate and encourage employees to check their tax codes and payslips when the new system begins.

How Apex can help

Moving benefits into real-time reporting affects much more than a single payroll field. Employers need accurate benefit records, suitable software, reliable employee data and processes for handling changes throughout the year.

Apex Accountants & Tax Advisors provides payroll services for UK businesses, including PAYE calculations, RTI submissions, payroll records, workplace pension administration and ongoing payroll compliance.

We can also help businesses review their benefit data, prepare payroll processes for the April 2027 transition and coordinate benefit reporting with wider payroll obligations.

With mandatory payrolling approaching, preparing the data and process early can make the first real-time reporting year considerably easier.

Self Assessment Registration Deadline: What to Do Before 5 October 2026

We’re increasingly asked by clients who started trading during 2025/26: “Do I need to register for Self Assessment?” It’s a question that catches people out because the registration deadline arrives months before the January filing deadline most people know about.

If you became self-employed, started renting out property, or received untaxed income for the first time in the 2025/26 tax year (6 April 2025 to 5 April 2026), you may need to tell HMRC by 5 October 2026. The exact requirement depends on your income and circumstances, so it is worth using HMRC’s Self Assessment checker if you are unsure.

Key Takeaways:

  • 5 October 2026 is the deadline to tell HMRC you need to file a Self Assessment return for the 2025/26 tax year
  • You must register if you earned more than £1,000 as a sole trader, were a partner in a business partnership, owed Capital Gains Tax, or meet certain other Self Assessment criteria
  • Late registration can trigger a “failure to notify” penalty based on tax still unpaid after 31 January 2027
  • Online tax return and payment deadline: 31 January 2027
  • Paper tax return deadline: 31 October 2026

What is the Self Assessment registration deadline?

The Self Assessment registration deadline is 5 October 2026 for the 2025/26 tax year. This is the date by which you must tell HMRC that you need to complete a tax return if you have never filed one before, or if you registered previously but did not need to send one for the 2024/25 tax year.

This deadline applies specifically to registration, not filing. Your actual tax return is not normally due until 31 January 2027 for online returns or 31 October 2026 for paper returns.

People who need to file for the first time must register for Self Assessment before they can complete their return. HMRC launched an improved individual online registration service in September 2026. Customers using the new service can receive their Unique Taxpayer Reference (UTR) in their online account within 72 hours, although other registration routes may take longer.

Who needs to register for Self Assessment by 5 October 2026?

You must register if, during the 2025/26 tax year (6 April 2025 to 5 April 2026), you need to complete a Self Assessment return and are not already registered.

SituationRegistration Required?
Self-employed sole trader earning more than £1,000 grossYes
Partner in a business partnershipYes
Sold or disposed of an asset and owe Capital Gains TaxYes
Liable for the High Income Child Benefit Charge and not paying it through PAYEYes
Off-payroll worker repaying a student or postgraduate loanYes
Rental income from property or landDepends on the amount and circumstances
Tips, commission or other untaxed incomeMay be required
Taxable foreign income as a UK residentUsually, although exceptions apply

Property income needs particular care. The first £1,000 of qualifying property income may be covered by the property allowance. If your annual rental income is above £1,000 but no more than £2,500, HMRC says you should contact them. You will generally need to report property income through Self Assessment if it exceeds the relevant HMRC thresholds.

If you are unsure whether you need to send a return, use HMRC’s online Self Assessment checker.

If you earned £1,000 or less from self-employment, you will usually not need to register solely because of that income. However, there are exceptions. For example, you may choose to file voluntarily to prove self-employment for certain benefits or to pay voluntary Class 2 National Insurance contributions.

How do you register for Self Assessment?

You can register for Self Assessment through GOV.UK. The process depends on your circumstances.

Sole traders will generally need details including:

  • Your National Insurance number
  • Your business start date
  • Your business name, or your own name if trading as yourself
  • The nature of your business

Partners may also need details of the partnership, including its UTR where one has already been issued.

If you are not self-employed but need to complete Self Assessment because of another source of income or tax liability, you should use the relevant non-self-employed registration route.

Once registered, HMRC issues you a 10-digit UTR number. Under HMRC’s new individual online registration service, this can appear in your online account within 72 hours, allowing you to start preparing your return.

What happens if you miss the 5 October registration deadline?

If you register after 5 October 2026 and do not pay all the tax you owe by 31 January 2027, you may face a “failure to notify” penalty. The penalty is based on the amount of tax left unpaid as a result of the failure to notify.

It is not a fixed fine. The percentage depends on the circumstances, including whether the failure was deliberate and whether you disclosed the issue voluntarily or after HMRC contacted you.

You could also face standard late filing penalties if you miss the filing deadline that applies to you:

StageLate Filing Penalty
1 day lateInitial £100
3 months late£10 per day, up to £900
6 months late5% of tax due or £300, whichever is greater
12 months lateFurther 5% of tax due or £300, whichever is greater

For the 2025/26 Self Assessment return, late payment penalties are generally 5% of the unpaid tax at 30 days, 6 months and 12 months, plus interest on the outstanding amount. You can check the current Self Assessment penalty rules on GOV.UK.

The practical risk of registering late is that it delays your ability to complete your return while the payment deadline remains fixed. Even if HMRC gives you a later filing deadline after late registration, any tax due must still generally be paid by 31 January 2027.

What are the full Self Assessment deadlines for 2025/26?

The 2025/26 tax year runs from 6 April 2025 to 5 April 2026. Here is the main deadline schedule:

DeadlineWhat’s Due
5 October 2026Register for Self Assessment if required and you have not filed before, or did not need to file for 2024/25
31 October 2026Paper tax return must reach HMRC
30 December 2026Online return deadline if you want eligible tax collected through your PAYE tax code
31 January 2027Online tax return deadline and payment deadline
31 July 2027Second payment on account, if applicable

One important detail is that if you register after 5 October 2026, HMRC will send you a letter or email with a different filing deadline. This will normally be 3 months from the date of that letter or email. However, you must still pay any tax you owe by 31 January 2027.

If you are eligible and want your Self Assessment bill collected through your PAYE tax code rather than paying it separately, you need to submit your online return by 30 December 2026.

How does the £1,000 trading allowance affect registration?

The £1,000 trading allowance means that if your annual gross trading income is £1,000 or less, you will usually not need to tell HMRC about that income. This is the gross figure before deducting expenses.

There are exceptions, including situations where you choose to complete a return to claim certain reliefs, pay voluntary National Insurance contributions or demonstrate self-employment for qualifying purposes.

If your gross trading income exceeds £1,000, you generally need to register for Self Assessment even if your eventual taxable profit is below the Personal Allowance and no Income Tax is ultimately due.

Worked example: Sarah started selling handmade goods on Etsy in August 2025. By 5 April 2026, her gross trading income was £2,400. Even though her profit after materials and fees might be minimal, she generally needs to register for Self Assessment by 5 October 2026 because her gross trading income exceeds £1,000.

Worked example: James did odd jobs for neighbours and earned £750 between June 2025 and March 2026. His trading income is below the £1,000 allowance, so he will usually not need to register solely because of that income. He may still choose to file voluntarily in certain circumstances.

You can read HMRC’s detailed guidance on the trading and property allowances.

What should you do after registering for Self Assessment?

Once you have your UTR number, the next steps are straightforward:

  1. Make sure you can access your HMRC online account and Self Assessment service
  2. Gather your records, including income statements, expense receipts, P60 or P45 documents if you also had employment income, interest records, dividend information and rental income details where relevant
  3. File your return early. You can submit your 2025/26 return any time after 6 April 2026 and do not have to wait until January
  4. Pay your tax bill by 31 January 2027. If you are eligible to have the bill collected through your PAYE tax code, submit your online return by 30 December 2026

Filing early has real advantages. You know your tax bill sooner, which gives you more time to budget for the payment, and you avoid the January rush.

It is also worth checking the top mistakes to avoid on your Self Assessment tax return before submitting.

Frequently Asked Questions

How long does HMRC take to send a UTR number after registration?

HMRC’s improved individual registration service launched in September 2026 allows customers using the new online service to receive their UTR in their online account within 72 hours. Other registration methods, including some agent or postal processes, may take longer.

Can I still file online if I register after 5 October?

Yes. If you register after 5 October 2026, HMRC will normally give you a revised filing deadline of 3 months from the date of its letter or email.

However, the tax payment deadline does not move with it. You must still pay the tax you owe by 31 January 2027 to avoid late payment consequences.

Do I need to register if I only had a small amount of untaxed income?

It depends on the type and amount of income.

If your gross trading income from self-employment is £1,000 or less, you will usually not need to register solely because of that income, although exceptions apply.

Different rules apply to property income, savings, dividends, foreign income and other untaxed income. HMRC’s Self Assessment checker is the safest way to confirm whether you need to file.

How much does an accountant charge for a Self Assessment tax return?

Accountancy fees vary depending on the complexity of the return, the number and type of income sources, and whether additional calculations or tax advice are required.

At Apex Accountants, we provide a fixed-fee quote upfront based on your specific circumstances, so you know the cost before the work begins.

What if I was self-employed for only part of the 2025/26 tax year?

You still generally need to register by 5 October 2026 if your gross self-employment income for the period exceeded £1,000.

Your tax return covers the full tax year from 6 April 2025 to 5 April 2026, but you report the income and expenses relating to the period during which you were trading. Trading for only part of the year does not change the registration deadline.

Do landlords need to register for Self Assessment separately from Making Tax Digital?

Making Tax Digital for Income Tax and Self Assessment registration are related but separate requirements.

The first £1,000 of qualifying property income may be covered by the property allowance. If your rental income exceeds that amount, whether you need to register for Self Assessment depends on your level of income and circumstances. HMRC advises people with property income above £1,000 but up to £2,500 to contact them, while higher amounts may need to be reported through Self Assessment.

Making Tax Digital for Income Tax began applying from 6 April 2026 to qualifying individuals with self-employment and/or property income who meet HMRC’s conditions, including the relevant qualifying-income threshold. MTD changes how qualifying taxpayers keep records and submit information to HMRC, but it does not remove the requirement to submit the relevant annual tax return.

How Apex Accountants Can Help

If you are unsure whether you need to register, or you want help getting your Self Assessment right the first time, that is exactly what we do. Our tax services cover support with tax registration, returns, compliance and payment planning.

We can check whether you need to register, handle the process for you, prepare your return and make sure relevant allowances and reliefs are considered so you do not pay more tax than necessary.

Book a consultation and we will talk through your situation and explain what needs to happen and by when.

R&D Tax Relief 2026: New HMRC Rules and How to Claim Successfully

We’re seeing more companies come to us after having their R&D tax relief claims questioned, returned, or rejected by HMRC. The landscape has changed significantly since the previous SME and RDEC regimes were replaced for accounting periods beginning on or after 1 April 2024. Compliance requirements have also tightened, meaning businesses need to pay closer attention to eligibility, supporting evidence and filing requirements.

The good news is that genuine innovation can still generate meaningful tax relief. However, companies now need to be more precise when documenting their R&D activities and identifying qualifying expenditure.

Key Takeaways:

  • The merged RDEC scheme offers a 20% taxable expenditure credit on qualifying R&D spend. Loss-making R&D-intensive SMEs may instead qualify for Enhanced R&D Intensive Support (ERIS).
  • HMRC received an estimated 46,950 R&D claims for 2023/24, a 26% decline from the previous year.
  • The Additional Information Form (AIF) is mandatory and must be submitted before, or on the same day as, the Company Tax Return containing the R&D claim.
  • A Claim Notification Form is required only for certain companies, including first-time claimants and some businesses without a sufficiently recent R&D claim.
  • HMRC introduced a targeted Advance Assurance pilot in 2026 to provide eligible SMEs with greater certainty on specific complex or high-risk areas of a proposed claim.

What is R&D tax relief in 2026?

R&D tax relief is a government incentive that allows eligible UK companies to obtain Corporation Tax relief or an expenditure credit for qualifying research and development. For accounting periods beginning on or after 1 April 2024, the merged R&D expenditure credit scheme and Enhanced R&D Intensive Support form the current framework.

To qualify, a project must seek an advance in science or technology by attempting to resolve scientific or technological uncertainty. The advance must not be something that a competent professional in the relevant field could readily work out.

Work in the arts, humanities or social sciences does not qualify simply because it is innovative. However, companies operating in creative industries can still qualify where their projects involve genuine scientific or technological uncertainty. This distinction is particularly important for creative businesses undertaking technical R&D.

SchemeWho can claimRatePotential benefit
Merged RDECCompanies with qualifying R&D expenditure20% taxable expenditure creditApproximately 15% to 16.2% net depending on Corporation Tax treatment
ERISLoss-making R&D-intensive SMEs meeting the intensity condition86% additional deduction, producing 186% enhanced expenditure, with a 14.5% payable credit on surrenderable lossUp to approximately 26.97% of qualifying expenditure where sufficient surrenderable loss is available

The merged RDEC credit is taxable and is dealt with through a series of statutory payment steps. Depending on the company’s tax position, it can offset Corporation Tax and other liabilities, with an amount potentially becoming payable after the relevant restrictions are applied.

How does the merged RDEC scheme work for your company?

The merged RDEC scheme provides a taxable expenditure credit equal to 20% of qualifying R&D expenditure.

For a company spending £100,000 on qualifying R&D, the gross credit would be £20,000. Because the credit is taxable, a company subject to Corporation Tax at 25% would generally retain a net benefit of approximately £15,000. At a 19% Corporation Tax rate, the equivalent net benefit would be approximately £16,200.

There is also a PAYE cap on the amount that can ultimately be paid to a company in an accounting period unless an exemption applies. Broadly, the cap is £20,000 plus 300% of the company’s relevant PAYE and National Insurance contribution liabilities for that period. For shorter accounting periods, the £20,000 element is proportionately reduced.

Qualifying expenditure can include staff costs, consumable materials, software, data and cloud computing costs, externally provided workers and certain payments to contractors, subject to the relevant conditions and restrictions.

These rules can be particularly important in technically complex industries such as M&E engineering, where development projects may involve qualifying design, testing and technical problem-solving.

Restrictions also apply to certain overseas contractor and externally provided worker costs.

Who qualifies for Enhanced R&D Intensive Support (ERIS)?

ERIS is available to loss-making SMEs whose qualifying R&D expenditure meets the R&D intensity condition.

For accounting periods beginning on or after 1 April 2024, qualifying R&D expenditure generally needs to represent at least 30% of the company’s relevant total expenditure, subject to the detailed rules, including the intensity-condition grace period.

A qualifying company can claim an additional deduction equal to 86% of its qualifying R&D expenditure. This means £100,000 of qualifying expenditure can produce enhanced expenditure of £186,000.

The payable credit is then calculated at 14.5% of the amount surrendered. The surrenderable loss is the lower of:

  • the enhanced expenditure; or
  • the company’s relevant trading loss after the additional R&D deduction.

Therefore, a loss-making R&D-intensive SME with £100,000 of qualifying expenditure and sufficient surrenderable losses could receive a maximum payable credit of approximately £26,970.

The actual benefit may be lower where the company’s available surrenderable loss is below £186,000.

A company that qualifies for ERIS can choose to claim under the merged RDEC scheme instead, but it cannot claim under both schemes for the same expenditure.

What is the Additional Information Form and why does it matter?

The Additional Information Form is mandatory for R&D claims and must be submitted before, or on the same day as, the Company Tax Return containing the claim.

Where the AIF and CT600 are filed on the same day, the AIF should be submitted first. Filing the Company Tax Return before completing this requirement can result in the R&D claim being removed.

The AIF requires detailed information including:

  • the company’s UTR, employer PAYE reference and VAT registration details where applicable
  • details of the main senior internal person responsible for the R&D claim
  • details of agents involved in preparing or advising on the claim
  • the relevant accounting period
  • qualifying expenditure details
  • project-by-project information about the R&D activities
  • explanations of the scientific or technological advances and uncertainties involved

Companies should make sure the accounting period information matches the Company Tax Return exactly.

A separate Claim Notification Form may also be required for accounting periods beginning on or after 1 April 2023. However, this requirement does not apply to every company.

It generally applies to first-time R&D claimants and companies whose previous claim falls outside the relevant three-year look-back period. Where notification is required, the claim notification period generally ends six months after the end of the relevant period of account.

Missing a required notification deadline can make the subsequent R&D claim invalid, so businesses should establish whether the requirement applies before filing.

How likely is an HMRC enquiry into my R&D claim?

HMRC has increased compliance activity around R&D tax relief significantly in recent years. This includes additional compliance staff and specialist work aimed at tackling error and abuse.

However, there is no single current published enquiry percentage that can reliably predict whether an individual R&D claim will be investigated.

What the latest figures clearly demonstrate is a substantial decline in claim volumes. The September 2025 R&D tax relief statistics estimate that there were 46,950 claims for 2023/24, down 26% from the previous year.

SME scheme claims declined more sharply, falling by approximately 31%.

Metric2023/24
Total R&D claims46,950
SME scheme claims36,885
RDEC claims10,065
Total relief claimed£7.6bn
Change in total claims-26%
Change in SME claims-31%

The total amount of relief claimed remained substantial at approximately £7.6 billion, only around 2% lower than the previous year’s estimate.

The reduction in smaller-company claims reflects the wider compliance and procedural changes affecting businesses across the country. Similar pressures have been seen among SMEs dealing with falling R&D tax relief claim volumes.

For businesses, the practical lesson is straightforward: prepare every claim on the assumption that HMRC may ask for supporting evidence.

What penalties apply if HMRC rejects my R&D claim?

An HMRC enquiry or rejected claim does not automatically mean that a penalty will apply. Penalties generally depend on whether an inaccuracy caused potential lost revenue and the behaviour that led to it.

For standard onshore inaccuracies, maximum penalties can include:

  • Careless inaccuracies: up to 30% of the potential lost revenue
  • Deliberate but not concealed inaccuracies: up to 70%
  • Deliberate and concealed inaccuracies: up to 100%

The actual percentage can be reduced depending on factors including disclosure and cooperation.

Late payment interest can also apply where additional Corporation Tax becomes payable. The current HMRC late payment interest rate is 7.75% per annum, effective from 9 January 2026.

For example, if an inaccurate R&D claim causes £50,000 of potential lost revenue, a careless inaccuracy could carry a maximum standard penalty of £15,000. A deliberate but not concealed inaccuracy could carry a maximum penalty of £35,000, while a deliberate and concealed inaccuracy could reach £50,000.

Actual penalties may be lower depending on the circumstances and the quality of disclosure.

A further development in 2026 is a proposed criminal offence relating to reckless untrue statements or declarations involving direct tax. The consultation closed on 16 August 2026. The proposal is not currently law, so companies should not treat the potential criminal sanction as an existing penalty.

What is the new R&D Advance Assurance pilot?

HMRC launched a targeted R&D Advance Assurance pilot in May 2026 for eligible SMEs.

Unlike full-claim Advance Assurance, the targeted pilot does not amount to approval of an entire R&D claim. Instead, eligible companies can seek greater certainty on specific complex or high-risk areas before filing.

This can be useful where a company faces uncertainty over issues such as whether particular activity qualifies as R&D, overseas expenditure, contracted-out R&D or the PAYE cap.

A separate full-claim Advance Assurance service also remains available to qualifying SMEs making their first R&D tax relief claim.

Advance Assurance does not replace the actual R&D claim or the other filing requirements. It gives eligible businesses greater clarity before the claim is submitted.

How can UK companies strengthen their R&D claim?

Strengthening an R&D claim begins with documenting the scientific or technological uncertainty the project sought to resolve, rather than simply compiling costs at the end of the accounting period.

A strong technical explanation should make clear:

  • the existing level of science or technology
  • the advance the project sought to achieve
  • the scientific or technological uncertainty encountered
  • why that uncertainty could not readily be resolved by a competent professional
  • how the project attempted to overcome the uncertainty

Practical steps include:

  • Keep contemporaneous technical records such as project plans, experiment logs, design iterations and test results.
  • Complete the AIF using specific project-level explanations rather than generic descriptions.
  • Check whether a Claim Notification Form is required and submit it within the relevant deadline where necessary.
  • Identify the senior internal person responsible for the claim.
  • Disclose the agents involved where required.
  • Separate qualifying R&D expenditure clearly from routine business activity.
  • Review contractor and overseas expenditure carefully before including it.

Strong technical evidence is particularly important in sectors where innovative commercial work and qualifying R&D can overlap. For example, motion graphics studios developing technically challenging production methods need to distinguish ordinary creative work from projects involving genuine technological uncertainty.

The same distinction matters when developing AI security systems that involve genuine technical challenges or undertaking innovation within wearable technology, smart textiles and sensor development.

Good documentation does not guarantee that HMRC will not open an enquiry, but it puts the company in a stronger position to explain and support the basis of its claim.

Frequently Asked Questions

Can I still claim R&D tax relief if my company is profitable?

Yes. Eligible profitable companies can generally claim under the merged RDEC scheme for accounting periods beginning on or after 1 April 2024.

The scheme provides a taxable expenditure credit equal to 20% of qualifying expenditure. The credit passes through statutory payment steps and can offset Corporation Tax or other liabilities, with an amount potentially becoming payable depending on the company’s circumstances.

Loss-making R&D-intensive SMEs may instead qualify for ERIS where they satisfy the relevant conditions.

How much does it cost to use an accountant for an R&D claim?

The cost varies between advisers and depends on the size and complexity of the claim.

Advisers may use fixed fees, hourly rates, contingent fees or a combination of different fee structures. Businesses should understand exactly what the quoted fee covers, including eligibility assessment, technical documentation, preparation of the AIF, tax calculations and support if HMRC later opens an enquiry.

Price should therefore be considered alongside the adviser’s technical expertise, sector experience and approach to compliance.

What happens if I miss the Claim Notification Form deadline?

First establish whether your company was actually required to submit a Claim Notification Form.

Not every claimant needs to complete one. The requirement generally applies to first-time claimants and certain companies without a sufficiently recent qualifying R&D claim.

If notification was required and the deadline has passed, the subsequent R&D claim may be invalid for that accounting period. Businesses should therefore review their previous claim history and obtain advice before assuming either that notification is required or that relief has been lost.

Does software development qualify for R&D tax relief?

Software development can qualify where a project seeks an advance in technology and involves technological uncertainty that a competent professional could not readily resolve.

Examples may include developing new algorithms, overcoming significant performance constraints or creating technically novel systems where existing solutions cannot achieve the required outcome.

Routine website development, standard app configuration or the implementation of off-the-shelf software does not automatically qualify.

What is the difference between the old SME scheme and ERIS?

The previous SME scheme changed over time, so one historic rate should not be applied to every old SME claim.

Before the April 2023 changes, the SME scheme generally provided a 130% additional deduction, producing total enhanced expenditure of 230%, alongside a 14.5% payable credit rate on qualifying surrenderable losses.

The rules changed for expenditure incurred from April 2023, including enhanced support for qualifying R&D-intensive SMEs.

For accounting periods beginning on or after 1 April 2024, ERIS provides qualifying loss-making R&D-intensive SMEs with an 86% additional deduction, producing enhanced expenditure of 186%, and a payable credit equal to 14.5% of the surrenderable loss.

Companies that do not qualify for ERIS generally use the merged RDEC scheme where otherwise eligible.

Can I claim R&D tax relief for work done overseas?

Overseas contractor and externally provided worker expenditure is more restricted under the current merged scheme and ERIS rules.

In general, expenditure relating to R&D activity undertaken outside the UK may be excluded. Limited exceptions can apply where conditions necessary for the R&D are not present in the UK, are present overseas and it would be wholly unreasonable to replicate those conditions in the UK.

Relevant circumstances may include particular geographical, environmental or regulatory requirements. Lower labour costs or greater availability of overseas workers alone are not sufficient.

Special rules may also apply to certain Northern Ireland companies claiming ERIS.

Businesses using overseas developers, engineers or specialist contractors should therefore review the location and contractual arrangements carefully before including the expenditure.

How Apex Accountants Can Help

If your company is investing in innovation, whether through new software, engineering solutions, digital systems or technically challenging products, R&D tax relief can provide valuable support where the eligibility requirements are met.

Apex Accountants supports research and development projects across a wide range of industries, helping businesses identify qualifying activity, prepare technical evidence, calculate eligible expenditure and complete the required documentation.

Our R&D tax team can support you with:

  • assessing whether projects meet the scientific or technological advance test
  • identifying qualifying expenditure
  • preparing the Additional Information Form
  • checking whether Claim Notification is required
  • calculating relief under the merged RDEC scheme or ERIS
  • reviewing contractor and overseas expenditure
  • supporting responses where HMRC opens an enquiry
  • assessing whether Advance Assurance may be appropriate

The rules have become more detailed, but eligible businesses can still access valuable relief where claims are carefully prepared and properly supported.

Book a free consultation to discuss your R&D activities with our team. We can review your projects, explain the relevant relief route and outline the compliance steps needed to prepare a robust claim.

HMRC Auto-Registration for MTD: What Happens If You Don’t Sign Up First

Sole traders and landlords are increasingly asking what happens if they do not respond to Making Tax Digital sign-up letters. From September 2026, HMRC is beginning a new phase of the rollout by signing up people who need to use MTD for Income Tax for 2026/27 but have not already done so themselves.

This change forms part of the wider MTD for Income Tax requirements for 2026, which include digital record-keeping, quarterly updates and an annual tax return through compatible software.

The main concern is not simply that HMRC may sign you up first. Automatic sign-up relies on information HMRC already holds, so recent changes to your self-employment or property income may not be reflected. Signing up yourself gives you more opportunity to check that your details are correct before quarterly reporting begins.

HMRC reported in August 2026 that more than 570,000 customers had signed up and more than 436,000 had already submitted their first quarterly update.

Key Takeaways

  • From September 2026, HMRC is beginning to sign up people who need MTD for Income Tax for 2026/27 but have not signed up themselves.
  • The £50,000 threshold is based on qualifying income shown on your 2024/25 Self Assessment return. Qualifying income means gross self-employment and property income before expenses, not profit.
  • 11 September 2026 is not a legal sign-up deadline. However, the MTD sign-up service will be unavailable from 5pm on 11 September until 1pm on 15 September for planned maintenance.
  • No penalty points will be issued for late quarterly updates during 2026/27, although the updates are still required.
  • If your circumstances have changed since your last tax return, checking your details before HMRC completes the sign-up can prevent additional work later.

What is MTD for Income Tax auto-registration?

MTD for Income Tax auto-registration refers to HMRC signing up taxpayers who are required to use Making Tax Digital but have not completed the process themselves.

Making Tax Digital for Income Tax became mandatory from 6 April 2026 for qualifying sole traders and landlords with more than £50,000 of qualifying income.

The underlying obligation has therefore not changed. What has changed is HMRC’s approach to people who remain outside the system despite meeting the criteria.

According to HMRC’s August 2026 MTD update, automatic sign-up will take place in stages over the coming months.

Who gets auto-registered for MTD?

For the 2026/27 tax year, MTD applies to sole traders and landlords whose qualifying income for 2024/25 was more than £50,000.

HMRC’s qualifying income rules confirm that this is based on gross income before expenses rather than taxable profit.

Tax return usedQualifying incomeMTD starts
2024/25More than £50,0006 April 2026
2025/26More than £30,0006 April 2027
2026/27More than £20,0006 April 2028

For sole traders, this means Making Tax Digital affects more than the way tax is ultimately calculated. It changes how business records are maintained, how income and expenses are reported and how frequently information is submitted to HMRC.

Timeline of MTD for Income Tax qualifying income thresholds: £50,000 from April 2026, £30,000 from April 2027, £20,000 from April 2028

What counts as qualifying income?

Qualifying income generally includes:

  • Gross self-employment income before expenses
  • Gross property income before expenses
  • Income from multiple self-employment or property sources added together
  • Certain income from a source that has since ceased, where another qualifying source continues

What does not normally count?

The following income is not included when calculating the MTD qualifying-income threshold:

  • Employment income through PAYE
  • Dividends
  • State Pension or private pension income
  • An individual’s share of partnership profit

For example, if you received £27,000 from self-employment and £25,000 in gross rental income during 2024/25, your qualifying income would be £52,000.

You would therefore fall above the £50,000 threshold even if your expenses reduced your taxable profit considerably.

What are the risks of waiting for HMRC to sign you up?

Automatic sign-up does not remove your responsibility to ensure the information held by HMRC is correct.

The biggest issue is that HMRC may be working from your previous Self Assessment return rather than your current circumstances.

Ceased income sources

If you stopped a self-employment activity or ceased receiving income from a property after submitting your previous return, HMRC’s records may still show the old source.

Closing one source does not necessarily mean you are outside MTD if another qualifying source continues.

New income sources

You may also have started a new business or begun receiving rental income since your previous tax return.

If HMRC does not yet hold that information, you may need to add the new source yourself.

All qualifying income has ceased

If you have stopped all self-employment and property activities, contact HMRC rather than assuming an automatic MTD registration can simply be ignored.

HMRC may need to update its records and confirm whether you are still required to use the service.

Software still needs to be arranged

Being signed up by HMRC does not automatically configure accounting software for you.

You still need compatible software, appropriate digital records and a process for submitting quarterly updates.

How do you sign up for MTD for Income Tax yourself?

HMRC’s MTD sign-up guidance explains the information needed to complete the process.

You generally need to be registered for Self Assessment and to have submitted a tax return within the previous two years.

If you sign up yourself, you use the Government Gateway account associated with your Self Assessment record.

Before completing the process, check that you can:

  • Confirm the tax year from which MTD applies to you
  • Review your self-employment and property income sources
  • Add any sources that are missing
  • Provide the relevant business or property start dates
  • Confirm your business details where required
  • Choose suitable MTD-compatible software

If an accountant or tax agent handles the process, they use their own Agent Services Account and the relevant HMRC authorisation rather than your personal Government Gateway password.

What is the MTD service downtime in September 2026?

HMRC has scheduled maintenance for the MTD for Income Tax service from 5pm on Friday 11 September until 1pm on Tuesday 15 September 2026.

This means the service will temporarily be unavailable, but 11 September is not a statutory MTD registration deadline.

HMRC’s current MTD service availability information also lists another maintenance period from 7pm on Saturday 26 September until 9am on Monday 28 September 2026.

If you want to complete your registration before the first maintenance window, you should therefore do so before 5pm on 11 September.

If you have not registered by then, the service is scheduled to reopen on 15 September. The important question is whether HMRC has already completed the automatic sign-up by that point.

What happens if you are late with quarterly updates?

HMRC will not issue penalty points for late quarterly updates during the first mandatory MTD tax year, 2026/27.

That does not mean quarterly updates are optional. Outstanding submissions still need to be dealt with, and separate penalties can apply to late annual tax returns and late tax payments.

From 2027/28, HMRC’s MTD penalty system begins applying to quarterly updates.

PositionPenalty
Each missed quarterly deadline1 penalty point
4 points accumulated£200 penalty
Further missed deadline while at thresholdAdditional £200 penalty

If you remain below the four-point threshold, a penalty point normally expires 24 months after the missed deadline.

Once the threshold is reached, however, the points do not simply disappear after two years. You generally need to complete a period of compliance and bring outstanding submissions up to date before the points are reset.

If you missed the first quarterly update in August 2026, dealing with it early is preferable to allowing reporting problems to accumulate. This may involve correcting your MTD records and checking that your bookkeeping is ready for the next submission.

Are there exemptions from MTD for Income Tax?

Yes. Some taxpayers may be exempt from Making Tax Digital.

One important category is digital exclusion. This can apply where it is not reasonably practical for someone to use digital tools because of factors such as:

  • Age
  • Disability
  • Health conditions
  • Religious beliefs
  • Lack of suitable internet access
  • Other circumstances making digital reporting unreasonable

HMRC’s MTD exemption guidance explains who may qualify and how applications are considered.

Being exempt from MTD does not mean the underlying income no longer needs to be reported. You must still meet your normal Self Assessment obligations.

If you are already using MTD and your qualifying income later falls below the threshold, one lower-income year will not usually remove you from the system immediately.

HMRC generally requires qualifying income to remain below the relevant threshold for three consecutive tax years before you can choose to leave MTD, subject to the circumstances applying to you.

How should sole traders and landlords prepare for the next thresholds?

MTD will expand further over the next two years.

From 6 April 2027, individuals with qualifying income above £30,000 will be brought into the system based on their 2025/26 tax return.

From 6 April 2028, the threshold will fall again to more than £20,000 based on qualifying income for 2026/27.

If your income falls into these ranges, preparation should start before the mandatory date.

Practical steps include:

  • Checking your gross self-employment and property income
  • Making sure all relevant income sources appear correctly on your Self Assessment return
  • Choosing compatible software in advance
  • Keeping business and property records digitally
  • Reconciling records regularly rather than waiting until a quarterly deadline
  • Confirming your MTD start date with your accountant

Consistent digital bookkeeping can make this easier by keeping income, expenses and supporting records organised throughout the year.

This becomes especially important because errors made during routine record-keeping can carry through into quarterly updates and ultimately affect the annual tax return.

Voluntary MTD sign-up is also available before your mandatory start date, but it should not be treated simply as a consequence-free trial. Once you enter the system, you need to understand the digital record-keeping and reporting obligations that apply.

Frequently Asked Questions

What if HMRC auto-registers me with the wrong details?

Check your MTD account as soon as you receive confirmation that HMRC has signed you up.

Automatic registration relies on information HMRC already holds, so changes made since your most recent tax return may not appear immediately.

Some details can be updated through the service, while more significant changes may require you to contact HMRC.

Do I still need to file a Self Assessment tax return under MTD?

Yes.

Quarterly updates do not replace your annual tax return. MTD users still complete an annual Self Assessment tax return through compatible software.

Other income, gains, allowances and reliefs that are not included in the quarterly updates are dealt with before the final return is submitted.

Can my accountant sign me up for MTD?

Yes.

An authorised accountant or tax agent can complete the registration process on your behalf using HMRC’s agent services.

They can also check that your income sources are correctly listed, connect suitable software and manage ongoing quarterly reporting.

How much does MTD-compatible software cost?

Costs vary depending on the provider and the features you need.

Some platforms are designed for straightforward sole-trader bookkeeping, while others include invoicing, bank feeds, receipt capture, property management and more advanced accounting features.

The important point is that the software must be compatible with MTD for Income Tax and suitable for the records you need to maintain.

What happens if I miss the 11 September sign-up date?

Nothing automatically happens simply because 11 September passes.

It is not a legal MTD sign-up deadline.

The significance of the date is that HMRC’s sign-up service is scheduled to become unavailable from 5pm on 11 September until 1pm on 15 September.

When the service reopens, you can still sign up if HMRC has not already completed the process on your behalf.

Will MTD for Income Tax apply to limited companies?

No.

MTD for Income Tax applies to individuals with qualifying self-employment or property income, including sole traders and landlords.

Limited companies have separate Corporation Tax and VAT obligations.

However, a company director may still fall within MTD personally if they also receive sufficient qualifying self-employment or property income.

How Apex Accountants Can Help

If you are unsure whether HMRC has already signed you up, whether your income sources are correct or whether your records are ready for quarterly reporting, our Making Tax Digital accountants can help with registration, software setup and ongoing submissions.

MTD should also be considered alongside your wider personal tax position, particularly where you receive income from several sources or have additional Self Assessment obligations.

If you want to confirm where you stand before HMRC completes an automatic sign-up or before the next quarterly deadline, you can book a consultation to review your qualifying income, current registration position and MTD setup.

Inheritance Tax Planning: A Practical UK Guide for 2026

A couple in their late sixties own a home worth £750,000 and have £700,000 in savings and investments. Their combined estate is worth £1.45 million. If the full transferable nil-rate band and residence nil-rate band are available, and the home passes to direct descendants, up to £1 million could potentially pass free of inheritance tax. That would leave £450,000 taxable at 40%, producing a potential bill of £180,000 before considering any other exemptions or reliefs.

This is why inheritance tax planning matters even for families who do not consider themselves exceptionally wealthy. HMRC’s latest annual receipts data shows that inheritance tax receipts rose from £3.5 billion in 2006/07 to £8.5 billion in 2025/26. Frozen thresholds, rising asset values and changing rules mean more families need to understand their potential exposure before a death occurs.

Key Takeaways

  • The nil-rate band is £325,000 and the residence nil-rate band is £175,000. Both are frozen through the 2030/31 tax year.
  • A qualifying married couple or civil partnership may be able to pass on up to £1 million free of inheritance tax if unused allowances transfer and a qualifying home passes to direct descendants.
  • From 6 April 2026, the 100% Agricultural Property Relief and Business Property Relief allowance is £2.5 million across qualifying agricultural and business property. Qualifying value above the allowance generally receives 50% relief.
  • From 6 April 2027, most unused pension funds and pension death benefits will be brought into the estate for inheritance tax purposes, subject to specific exclusions.
  • Under the 7-year gift rule, outright gifts to individuals can become fully exempt if the donor survives for seven years. Taper relief can reduce tax on certain gifts made more than three years before death.

What is inheritance tax and when does it apply?

Inheritance tax, or IHT, is generally charged at 40% on the taxable value of an estate above the available tax-free thresholds. An estate can include property, cash, investments, business interests and life insurance owned personally. Life insurance placed into an appropriate trust may be treated differently, so the ownership and trust terms need to be considered carefully.

Under the current inheritance tax rules, the standard nil-rate band is £325,000. Amounts left to a spouse or civil partner are generally exempt. However, special rules can apply where one spouse is a long-term UK resident and the other is not, making HMRC’s long-term UK residence guidance relevant for some cross-border families.

Gifts to qualifying charities are also exempt. Where at least 10% of the relevant net estate is left to charity, the IHT rate applying to the qualifying part of the estate can fall from 40% to 36%.

How much is the inheritance tax threshold in 2026?

The nil-rate band has been fixed at £325,000 since the 2009/10 tax year. The current IHT threshold rules keep the nil-rate band, residence nil-rate band and £2 million residence nil-rate band taper threshold at their present levels through 2030/31.

ThresholdAmountCurrent position
Nil-rate band (NRB)£325,000Frozen through 2030/31
Residence nil-rate band (RNRB)£175,000Frozen through 2030/31
Potential combined allowance for a qualifying coupleUp to £1,000,000Subject to transfer and RNRB conditions

For a single person with an estate worth £600,000, no qualifying residence nil-rate band and no other reliefs, the simplified calculation would be:

ElementAmount
Estate value£600,000
Nil-rate band£325,000
Taxable amount£275,000
IHT at 40%£110,000

Actual calculations may differ where an estate includes lifetime gifts, trusts, debts, reliefs, jointly owned assets or overseas property. Our inheritance tax calculation UK guide explains how these different allowances and estate components can affect the final liability.

What is the residence nil-rate band and how does it work?

The residence nil-rate band can add up to £175,000 to an individual’s available threshold when a qualifying residence passes to direct descendants. HMRC’s residence nil-rate band guidance explains the qualifying conditions.

For one person, the nil-rate band and full residence nil-rate band can provide a potential total threshold of £500,000. Where unused allowances can be transferred between spouses or civil partners, the surviving person’s qualifying estate may have up to £650,000 of nil-rate band and £350,000 of residence nil-rate band, giving a possible combined total of £1 million.

The residence nil-rate band is tapered for estates worth more than £2 million. It falls by £1 for every £2 by which the estate exceeds that threshold. For an estate entitled only to one £175,000 RNRB, the allowance is fully tapered away at £2.35 million.

Estate valueIndividual RNRB before other adjustments
Up to £2,000,000£175,000
£2,100,000£125,000
£2,200,000£75,000
£2,350,000£0

Where a full transferred RNRB is available, the amount being tapered may be higher. A transferable percentage can also potentially be claimed where the first spouse or civil partner died before the RNRB was introduced on 6 April 2017.

How does the 7-year gift rule reduce inheritance tax?

Most outright lifetime gifts to individuals are potentially exempt transfers. Under HMRC’s inheritance tax rules for gifts, a gift can become fully exempt if the donor survives for seven years after making it.

If the donor dies within seven years, the gift can become chargeable and may use some or all of the available nil-rate band. Taper relief can reduce the tax charged on a taxable gift, rather than reducing the value of the gift itself, where more than three years have passed.

Time between gift and deathEffective rate on taxable gift where taper applies
Less than 3 years40%
3 to 4 years32%
4 to 5 years24%
5 to 6 years16%
6 to 7 years8%
7 years or more0%

Taper relief generally becomes relevant only where chargeable gifts exceed the available nil-rate band.

Several exemptions can also support inheritance tax planning:

  • Annual exemption: up to £3,000 per tax year, with an unused amount potentially carried forward for one tax year.
  • Small gifts: up to £250 per person per tax year, subject to HMRC’s conditions.
  • Wedding or civil partnership gifts: up to £5,000 to a child, £2,500 to a grandchild or great-grandchild, and £1,000 to another person.
  • Normal expenditure out of income: qualifying regular gifts can be exempt where they are made from income and leave the donor able to maintain their normal standard of living.
  • Gifts between spouses or civil partners: generally exempt, subject to relevant residence-based rules.

A gift with reservation of benefit is different. If you give an asset away but continue to benefit from it, HMRC may still treat it as part of your estate. Giving a home to children while continuing to live there rent-free is a common example.

What changed for Business Property Relief and Agricultural Property Relief in April 2026?

From 6 April 2026, the inheritance tax treatment of qualifying agricultural and business property changed. Under the current Agricultural Property Relief and Business Property Relief rules, the combined allowance for 100% relief is £2.5 million.

Under the new rules:

  • The first £2.5 million of qualifying agricultural and business property can receive 100% relief.
  • Qualifying value above the allowance generally receives 50% relief.
  • An unused allowance can be transferred between spouses or civil partners, potentially increasing the survivor’s 100% relief allowance to as much as £5 million.
  • Business property must still satisfy the underlying qualifying conditions. The business or relevant asset generally needs to have been owned for at least two years, and investment businesses may not qualify.

For example, if a qualifying trading business is worth £4 million and an individual has the full £2.5 million allowance, the remaining £1.5 million receives 50% relief. This leaves £750,000 within the chargeable estate before the ordinary nil-rate band or other available reliefs are considered. At 40%, that represents a maximum IHT exposure of £300,000 on the excess before those further allowances are applied.

Business owners should therefore review ownership, succession plans, qualifying status and liquidity rather than assume that historic 100% relief will continue to cover the entire business.

How will pensions be taxed under the new inheritance tax rules from April 2027?

From 6 April 2027, most unused pension funds and pension death benefits will be included in a deceased person’s estate for inheritance tax purposes. HMRC’s August 2026 technical update on IHT and pensions confirms that the reform was legislated for in Finance Act 2026 and applies to deaths on or after 6 April 2027.

This does not mean every pension death benefit will automatically face IHT. Specific exclusions remain, including registered pension death-in-service benefits and certain dependant scheme pensions. Income tax rules applying to pension benefits also remain a separate consideration.

For families that have deliberately preserved pension wealth to pass to the next generation, the reform is significant. Pension arrangements should therefore be considered alongside the rest of the estate rather than as a separate planning exercise. The treatment can also vary depending on the pension type, the member’s age at death and how benefits are paid, which we cover in more detail in our inheritance tax and pensions guide.

What are the most effective inheritance tax planning strategies?

Effective inheritance tax planning normally combines several methods depending on the family’s finances, objectives and wider tax position.

1. Use lifetime gift exemptions.
Annual, small gift and wedding or civil partnership exemptions can gradually reduce an estate without subjecting the exempt amount to the seven-year rule.

2. Make larger gifts early enough for the seven-year period to run.
Larger outright gifts can be useful, but affordability, capital gains tax, control of the asset and the consequences of dying within seven years all need to be considered.

3. Consider normal expenditure out of income.
For people with regular surplus income, this can be particularly valuable because qualifying gifts do not have a seven-year waiting period. Keeping evidence of income, expenditure and the gifting pattern is important.

4. Review qualifying business assets.
Family business owners should confirm whether assets meet Business Property Relief conditions, how the £2.5 million allowance applies and whether an unused allowance from a spouse or civil partner is available.

5. Review pension planning before April 2027.
Drawing pension funds purely to reduce IHT can create income tax and investment consequences. Any change should therefore be considered as part of the wider retirement and estate plan.

6. Consider appropriately structured life insurance.
Where a policy is properly written in trust, it may provide funds outside the estate to help beneficiaries meet an IHT liability without forcing the sale of other assets.

7. Use trusts only where they fit the wider objective.
Trusts can provide control and asset protection, but transfers into trust can themselves create inheritance tax charges. Relevant property trusts can also face periodic and exit charges, so they are not a simple way to remove IHT.

What happens if you get inheritance tax planning wrong?

Poor planning can create unexpected tax liabilities, cash-flow problems and disputes. For a qualifying couple with a £1.5 million estate and a full £1 million combined threshold, the simplified IHT bill on the remaining £500,000 would be £200,000 before other reliefs or adjustments.

Common risks include:

  • Gifts with reservation: an asset may remain in the taxable estate where the donor continues to benefit from it.
  • Failed seven-year planning: gifts made less than seven years before death can use the nil-rate band and, where sufficiently large, may create a tax liability for the recipient.
  • Missed reliefs: Business Property Relief and Agricultural Property Relief must be properly claimed and supported.
  • Late payment: HMRC’s inheritance tax payment rules generally require IHT to be paid by the end of the sixth month after death. Interest can run after the due date, although instalment arrangements are available for certain assets.
  • Incorrect valuations or returns: penalties depend on the behaviour that produced the inaccuracy. Under HMRC’s penalty framework, deliberate and concealed inaccuracies can attract penalties of up to 100% of the potential lost revenue, while careless mistakes are treated differently.

The 2026 Court of Appeal decision in Elborne & Ors v HMRC [2026] EWCA Civ 894 demonstrates how complex inheritance tax arrangements can become. The Court dismissed HMRC’s appeal and held that the historic home-loan scheme used in that particular case worked under the legislation applicable to the arrangements.

The judgment should not be read as a general endorsement of similar schemes today. It instead illustrates how highly technical arrangements can lead to years of litigation, making accurate implementation and professional advice important even where a planning structure appears effective.

Frequently Asked Questions

Do I need an accountant for inheritance tax planning?

Professional advice can be particularly valuable where an estate is near or above the available IHT thresholds or includes a business, trusts, overseas assets, significant lifetime gifts or a large pension. A tax adviser can calculate potential exposure and identify relevant exemptions and reliefs. Legal advice may also be required for wills, trusts and property transfers.

How much does inheritance tax planning cost?

There is no reliable one-size-fits-all price. Costs depend on the value and complexity of the estate, the work required and whether legal or specialist valuation advice is needed. Apex Accountants scopes the required work and pricing based on the client’s circumstances rather than applying a generic estimate.

What happens if I do not plan for inheritance tax?

Your estate may pay 40% on the taxable amount above the available thresholds after exemptions and reliefs are considered. In many cases, some inheritance tax must be paid before a grant of representation can be obtained, which can create liquidity problems where an estate contains valuable property or business assets but limited cash.

Can I give my house to my children and still live in it?

You can transfer ownership, but continuing to live in the property without paying a full market rent can create a gift with reservation of benefit. The property may therefore remain within your estate for IHT purposes.

There is no simple trust workaround. A property transfer can also have capital gains tax, stamp duty, care-fee and wider legal consequences, so specialist advice should be taken before ownership is transferred.

When should I start inheritance tax planning?

Earlier planning usually creates more options. The 7-year gift rule needs time to run, Business Property Relief depends on qualifying conditions and ownership periods, and the pension IHT changes take effect from 6 April 2027.

An estate plan should also be reviewed after major changes such as marriage, divorce, receiving an inheritance, selling a business or experiencing a significant increase in asset values.

Is inheritance tax planning the same as tax avoidance?

No. Sensible inheritance tax planning uses statutory exemptions, allowances and reliefs in the way the law permits. Artificial arrangements designed primarily to exploit technical gaps may attract HMRC scrutiny and can fail if the relevant legal conditions are not satisfied.

Apex Accountants’ View

Apex Accountants has supported UK individuals, families and business owners with tax and estate planning since 2006. Our ACCA and ICAEW-qualified team considers the estate as a whole, including property, savings, investments, business interests, pensions, life insurance, lifetime gifts and existing estate-planning arrangements.

The April 2026 changes to Business Property Relief and Agricultural Property Relief, followed by the pension reforms from April 2027, mean plans prepared several years ago may no longer produce the same outcome.

Our estate planning services cover inheritance tax calculations, gifting strategies, trusts, business succession and probate support, while our personal tax services can help where estate planning interacts with an individual’s wider tax position.

The aim is not to force every estate into the same structure. A family business owner, a retiree with investment property and a household with a large pension pot can face very different IHT risks and planning priorities.

If you want to understand your current exposure before making gifts, changing pension arrangements or restructuring business ownership, contact our team for an initial assessment of the options available.

Accountant for Community Pharmacy UK: VAT and Tax Guide

A pharmacy can look profitable on paper while still facing tight cash flow. NHS income, retail sales, dispensing margins, staff costs, stock movements and VAT liabilities can be recognised at different times and require different accounting treatment.

That is why an accountant for community pharmacy UK businesses rely on should understand how a pharmacy operates, not simply submit a year-end return. The immediate priorities are usually accurate community pharmacy VAT treatment, reliable branch-level reporting, payroll control, stock accounting, pharmacy bookkeeping and tax planning that reflects how the business actually trades.

Key takeaways

  • Community pharmacies can make a mixture of zero-rated, exempt, standard-rated and, in some cases, outside-the-scope supplies. The VAT treatment depends on the underlying goods or services and the relevant conditions.
  • HMRC’s VAT Notice 701/57 and VAT Health manual explain important rules for pharmacists and dispensed medicines.
  • England’s 2026–27 Community Pharmacy Contractual Framework provides total funding of £3.636 billion. This is sector funding, not a guaranteed amount for an individual pharmacy.
  • Good pharmacy bookkeeping should reconcile NHS remittances, dispensing data, retail tills, stock, payroll and supplier statements.
  • A specialist review can be particularly useful before a VAT compliance check, acquisition, restructuring or major funding change.

Why does a community pharmacy need specialist accounting support?

A community pharmacy has several revenue streams and cost patterns that can make generic small-business bookkeeping unreliable. NHS dispensing, private prescriptions, over-the-counter medicines, consultations, vaccinations, delivery charges and retail products do not necessarily share the same VAT treatment.

The accounts also need to explain operational performance. A single sales total can hide weak margins in one branch, stock losses, rising locum costs or a funding payment posted to the wrong accounting period.

A specialist pharmacy tax accountant should connect the bookkeeping to practical decisions, including:

  • branch profitability and cash generation;
  • staffing, locum and overtime costs;
  • stock movements, expiries and gross margins;
  • acquisition funding and deal structure; and
  • owner salary, dividend and pension decisions.

Apex’s healthcare sector accountants can support pharmacy owners who need accounting, payroll, VAT and tax advice to work together rather than sit in separate files.

How does VAT work for a UK community pharmacy?

VAT treatment in a pharmacy is transaction-specific. It is not safe to assume that every medicine is zero-rated, every clinical service is exempt or every NHS-related payment has one automatic VAT outcome.

HMRC’s VAT Notice 701/57 explains the VAT treatment of goods and services provided by registered health professionals, including pharmacists. It also covers VAT recovery for VAT-registered health professionals and the rules applying to pharmaceutical goods.

HMRC’s VAT Health guidance on dispensing by a pharmacist confirms that most dispensing in a traditional community pharmacy is zero-rated where the relevant statutory conditions or NHS prescription concessions are met. The precise facts still need to be checked.

Pharmacy activityWhy the VAT treatment needs checking
Qualifying prescription dispensingZero-rating can apply when the relevant conditions are met.
Over-the-counter medicines and toiletriesMany retail supplies are standard-rated, while some products can have a different treatment.
Vaccination or other clinical servicesExemption can apply to qualifying medical care, but not every service is automatically exempt.
NHS or commissioner-funded servicesThe underlying supply, contractual terms and payment must be considered together.
Management or administration chargesThese can have a different liability from the medicines or care element.
Purchases and overheadsInput VAT recovery can be restricted where costs relate to exempt or non-business activities.

The legislation underpinning zero-rating includes Schedule 8 to the Value Added Tax Act 1994. HMRC guidance should be read alongside the legislation and the facts of each transaction.

A specialist VAT review can test till setup, product coding, invoice wording, NHS remittance entries and partial-exemption calculations. For a pharmacy with mixed activities, a periodic community pharmacy VAT review can also confirm that output VAT and input VAT recovery remain consistent with current trading.

What changed for NHS pharmacy funding in 2026–27?

For England, the Community Pharmacy Contractual Framework for 2026 to 2027 states that total funding will be £3.636 billion, representing a 10.3% increase compared with 2025–26. GOV.UK also confirms an agreement not to recover up to £239 million of historic over-paid funding from the sector.

These are national NHS pharmacy funding figures for England. They do not predict a particular pharmacy’s income, profit or cash receipts. An individual pharmacy’s position depends on its services, dispensing volume, reimbursement, clawbacks, staffing and other costs.

The framework also covers independent prescribing, the Pharmacy Quality Scheme and regulatory changes. These developments can create accounting questions around the timing, classification and evidence for income and expenditure.

A pharmacy should therefore reconcile each service or activity to:

  1. the remittance or payment received;
  2. the accounting period to which it relates; and
  3. any deduction, adjustment, clawback or repayment.

This provides a stronger basis for cash-flow forecasting and for answering questions from HMRC, lenders or a potential buyer. As NHS pharmacy funding arrangements change, the records should distinguish recurring, activity-based, one-off and adjustable income.

Which records should a pharmacy accountant review every month?

Monthly reporting should show what is happening before the annual accounts deadline. At a minimum, the review should cover bank reconciliations, supplier balances, payroll, VAT control accounts, stock and NHS or commissioner remittances.

Useful monthly controls include:

  • comparing dispensing and retail revenue with the till and pharmacy system;
  • reconciling NHS payments to claims or remittance statements;
  • reviewing negative or unusually high gross margins;
  • checking stock purchases, write-offs, expiries and shrinkage;
  • separating owner drawings, wages, dividends and business expenses;
  • checking locum invoices and employment-status treatment where necessary; and
  • reviewing aged creditors before supplier pressure affects cash flow.

For multi-branch operators, management accounts should show branch-level sales, gross margin, payroll, occupancy, locum costs and contribution. Strong pharmacy bookkeeping should create a reliable link between operational activity, cash movements and management reporting.

Apex’s accounting services can be combined with pharmacy-specific controls to produce management information that supports decisions as well as compliance.

How should pharmacy owners approach corporation tax and payroll?

A limited company pharmacy normally needs statutory accounts and a Company Tax Return, with corporation tax calculated from adjusted taxable profits. Taxable profit can differ from management profit because of capital allowances, disallowable expenses, timing rules and other tax adjustments.

For pharmacy corporation tax planning, owners should look beyond the year-end liability. Equipment investment, acquisition costs, remuneration decisions and the timing of significant expenditure can affect both tax and cash flow.

The company should also keep payroll and dividends distinct. Salary and employer costs run through payroll, while dividends must be supported by available profits and appropriate company records. Treating every payment to an owner as a dividend can create tax and accounting problems.

Pharmacy employers should review PAYE, pension duties, holiday pay, overtime, locum arrangements and benefits. Staff costs are often one of the largest controllable expenses, so errors can affect both compliance and profitability.

Where a pharmacy is buying another branch or company, advice should begin before the deal is agreed. The review may cover stock valuation, goodwill, fixtures, property, debt, VAT history, employees and the structure of the purchase.

A specialist corporation tax adviser can model these consequences, especially where pharmacy corporation tax planning overlaps with an acquisition, restructuring or change in ownership.

What is a simple pharmacy VAT error example?

Suppose a pharmacy codes every sale as standard-rated because it sells both retail goods and prescription medicines. This could overstate output VAT on qualifying zero-rated supplies. The opposite error is also possible if zero-rating is applied to goods or services that do not meet the relevant conditions.

The pharmacy would need to identify the affected transactions, inspect the supporting records, check the applicable HMRC guidance and determine whether previously submitted VAT returns need correcting.

Real pharmacies can also have mixed supplies, NHS payments, private work and shared overheads, so the correct treatment may require a broader review of VAT liability and input tax recovery.

Do community pharmacies need a VAT partial-exemption review?

They may. Partial exemption can become relevant when a VAT-registered pharmacy makes both taxable and exempt supplies and incurs VAT on costs relating to those activities.

A pharmacy should not assume that every amount of input VAT is recoverable simply because the business is VAT-registered. It should document the link between costs and supplies, apply the appropriate method and retain evidence supporting the figures reported.

How can a pharmacy prepare for an HMRC VAT compliance check?

Start with a clean audit trail. HMRC should be able to follow a sample transaction from the till, dispensing system or service contract through the ledger, VAT code, VAT return and bank or remittance reconciliation.

Before a compliance check, review:

  • VAT registration details and return periods;
  • product and service VAT codes;
  • NHS and commissioner remittances;
  • private prescription and retail sales;
  • input VAT on stock, rent, equipment and professional costs;
  • partial-exemption calculations, where relevant; and
  • prior corrections, disclosures and correspondence.

If an error is identified, quantify it, preserve the working papers and obtain advice on the correct amendment or disclosure route.

Frequently Asked Questions

Is a pharmacy accountant more expensive than a general accountant?

Fees depend on branch count, transaction volume, payroll, VAT complexity and the level of reporting required. Specialist work can cost more than basic compliance, but it may also identify recurring VAT, stock or payroll errors.

Can a pharmacy accountant help with buying another pharmacy?

Yes. An accountant can assess management accounts, stock, goodwill, VAT history, payroll, funding, cash flow and the tax effects of different deal structures. Advice is most useful before heads of terms or a purchase agreement is finalised.

Does NHS pharmacy income automatically have no VAT?

No. The VAT treatment depends on the underlying supply, the relevant conditions and how the payment relates to the goods or service. NHS dispensing income and other service funding should be analysed rather than placed into one automatic VAT category.

What happens if a pharmacy has used the wrong VAT code?

The business should identify the affected transactions, calculate the net error and check whether previously submitted VAT returns need correcting. The underlying coding should also be fixed so the problem does not continue.

What does a pharmacy accountant need from the owner?

Usually, the accountant needs sales and dispensing reports, NHS remittances, bank feeds, supplier statements, stock information, payroll data, VAT returns and details of unusual transactions.

Can Apex support a pharmacy outside England?

Apex can provide UK accounting, tax, payroll and VAT support, but the England-specific funding reference in this article should not be assumed to apply in the same way across Scotland, Wales or Northern Ireland. The relevant devolved arrangements and contracts should be checked for the pharmacy’s location.

Apex Accountants’ View

Community pharmacy owners need financial information that reflects how the business actually operates. A year-end profit figure cannot show whether a branch is losing margin through stock expiry, whether locum spending is rising or whether an NHS payment has been posted to the wrong period.

At Apex, we advise UK businesses on bookkeeping, VAT, payroll, corporation tax and management reporting. For pharmacies, that means connecting the ledger to dispensing activity, retail sales, remittances, stock and staff costs. A specialist pharmacy tax accountant should help maintain defensible records while making cash flow, margins and profitability easier to understand.

Apex Accountants has supported UK businesses since 2006. The sensible starting point is a review of current records, VAT treatment and reporting needs so the accounting process reflects the pharmacy’s services, funding arrangements and growth plans.

HMRC’s First Cryptoasset Statistics Show Why Records Matter

Capital Gains Tax is becoming increasingly important for UK crypto investors as HMRC gains access to more detailed information about cryptoasset activity. An investor who sold Bitcoin, swapped tokens or used cryptoassets to pay for goods may already have a reporting obligation, while staking, mining or lending rewards can create separate Income Tax issues.

On 27 August 2026, HMRC published its first official statistics on taxable cryptoasset gains. The figures show that 17,600 individuals made Capital Gains Tax-liable cryptoasset disposals in 2024/25. Collectively, they reported £13.8 billion of disposal proceeds and £1.38 billion of gains.

These are official statistics based on reported taxable activity. They are not an estimate of the total number of UK crypto investors or the tax liability of every cryptoasset holder.

For a broader explanation of how UK tax rules apply to disposals, income and undeclared liabilities, see Apex Accountants’ guide to tax liabilities from cryptoassets.

Key Takeaways

  • 17,600 individuals made Capital Gains Tax-liable cryptoasset disposals in 2024/25.
  • Those taxpayers reported £13.8 billion of disposal proceeds and £1.38 billion of gains.
  • 240 people reported more than £1 million of cryptoasset capital gains, accounting for £717 million of gains between them.
  • The UK’s Cryptoasset Reporting Framework rules began from 1 January 2026, with the first provider reports due by 31 May 2027.
  • HMRC says it will start receiving cryptoasset provider data from 2027.
  • For the 2025/26 tax year, the Self Assessment filing and payment deadline is 31 January 2027 where a return is required.

What Did HMRC’s New Cryptoasset Data Actually Show?

HMRC’s 2026 release is the first annual Capital Gains Tax statistics publication to include a specific cryptoasset breakdown. The supporting Capital Gains Tax statistics now include a dedicated Table 10 covering cryptoasset gains and disposal proceeds.

HMRC reported that the 17,600 individuals with Capital Gains Tax-liable cryptoasset disposals had average gains of approximately £78,000 each. However, that average is affected by taxpayers with particularly large gains. HMRC also reported that around 87% of individuals reporting cryptoasset gains were male and around 13% were female.

The £13.8 billion figure relates to disposal proceeds, not taxable profit. A disposal can arise without money being withdrawn to a UK bank account. HMRC’s guidance on selling and disposing of cryptoassets explains that relevant disposals can include selling tokens, exchanging one cryptoasset for another, using cryptoassets to buy goods or services, and giving cryptoassets away in circumstances where no exemption applies.

The figures are rounded and may not sum precisely.

When Does Crypto Activity Create Capital Gains Tax?

Capital Gains Tax may arise when an individual disposes of cryptoassets and the disposal produces a chargeable gain. In broad terms, the gain is calculated by comparing the disposal value with the allowable acquisition cost and other allowable costs, while applying the relevant matching and pooling rules.

Common cryptoasset disposal events include:

  • selling Bitcoin, Ethereum or another token for pounds or another currency;
  • exchanging one cryptoasset for another;
  • using cryptoassets to pay for goods or services; and
  • giving cryptoassets away, except where an exemption or relief applies, such as certain transfers to a spouse or civil partner.

A transfer between wallets that you beneficially own is generally not a disposal simply because the cryptoasset has moved. HMRC’s Cryptoassets Manual on disposals confirms that there is no disposal where the individual retains beneficial ownership throughout the transfer.

The calculation becomes more difficult where an investor has made repeated purchases and disposals at different prices. Exchange statements can help, but HMRC warns that platform reports are not themselves UK tax calculations and may not track pooled costs.

An increase in the market value of a cryptoasset does not by itself create Capital Gains Tax. A tax point generally arises on a disposal. However, cryptoassets received through employment, mining, staking, lending or business activity can have different treatment. HMRC’s Cryptoassets Manual explains when Income Tax, National Insurance or Capital Gains Tax may apply depending on the facts.

For taxpayers who need help determining the correct treatment of disposals and gains, Apex Accountants’ Capital Gains Tax services cover cryptoassets as well as other investments and assets.

What Does CARF Mean for UK Crypto Investors?

The Cryptoasset Reporting Framework, or CARF, is an international reporting standard designed to improve tax transparency and the exchange of cryptoasset information between tax authorities.

The UK’s CARF rules commenced on 1 January 2026. Reporting cryptoasset service providers must collect relevant user and transaction information, carry out due diligence and retain the records required under the framework.

HMRC’s CARF reporting guidance for cryptoasset service providers states that the first reports must be submitted between 1 January and 31 May 2027, covering the calendar year from 1 January to 31 December 2026. HMRC therefore expects to start receiving this provider data from 2027.

CARF does not introduce a new tax on cryptoassets. It changes the amount of information available to HMRC and other participating tax authorities. Providers will report user details and summaries of relevant transactions. HMRC says a provider that fails to follow the reporting rules may face penalties of up to £300 per user.

UK cryptoasset users are also required to provide accurate identifying information to service providers. HMRC’s guidance for cryptoasset users explains what information may be requested and how it can be shared between participating tax authorities.

The practical point for investors is that provider data may not tell the whole story. A transfer between two wallets owned by the same person can look very different from a taxable disposal unless records connect both sides of the transaction. The taxpayer therefore still needs a complete and coherent audit trail.

What Records Should UK Crypto Investors Keep?

HMRC places responsibility on taxpayers to keep their own cryptoasset records. Exchanges may retain transaction data for only a limited period, and a platform may no longer exist when a tax return or HMRC enquiry is dealt with.

HMRC’s cryptoasset record-keeping guidance says records should include information such as:

  • the type of cryptoasset;
  • the date of each transaction;
  • whether the cryptoasset was bought or sold;
  • the number of units involved;
  • the sterling value of the transaction at the transaction date;
  • the cumulative number of investment units held;
  • relevant bank statements; and
  • wallet addresses where needed.

It is also sensible to retain exchange exports, transaction IDs, fee information and evidence showing transfers between wallets or platforms.

Cryptoasset values must be calculated in pounds sterling for UK tax purposes. Where an exchange does not provide a sterling value, HMRC expects an appropriate exchange rate and a consistent valuation method. Keep evidence of the method used.

Investors should separate at least four broad types of activity:

  • purchases and sales;
  • token-to-token exchanges;
  • transfers between wallets or accounts; and
  • income events such as staking, mining, employment rewards or lending returns.

Do not assume a platform’s annual summary is a complete UK tax calculation. It may omit activity held elsewhere, misclassify transfers or fail to apply the UK pooling rules correctly.

What Is the Deadline for Declaring Crypto Income or Gains?

For the 2025/26 tax year, the normal online Self Assessment filing deadline is 31 January 2027, and tax due through Self Assessment is generally payable by the same date.

For Capital Gains Tax, the annual exempt amount for individuals is £3,000 for 2025/26. HMRC’s Capital Gains Tax rates and allowances confirm that amount.

The reporting position is not determined by the £3,000 allowance alone. If you are already registered for Self Assessment, GOV.UK says you must report your gains on the return if the total amount for which you disposed of chargeable assets is more than £50,000, even if your gains are below the annual exempt amount.

Cryptoasset income is different from capital gains and may need to be reported under the appropriate Income Tax provisions. HMRC’s 27 August 2026 release notes that there is a dedicated Self Assessment section for cryptoasset capital gains, but no equivalent dedicated cryptoasset income box for activities such as mining or staking.

If you have unpaid cryptoasset tax from older tax years, HMRC’s Cryptoasset Disclosure Service may be relevant. However, HMRC says income or gains from the current or previous tax year should normally be reported through the Self Assessment tax return rather than the disclosure service.

What Should Someone Do If Their Crypto Records Are Incomplete?

Start by listing every exchange, wallet and protocol used during the relevant tax years. Download available transaction histories and identify missing periods, duplicated entries, transfers and transactions recorded in different currencies.

Next, classify each transaction correctly. A token sale or token-to-token exchange may be a capital disposal. Staking rewards may be taxable as income when received, depending on the facts, and a later disposal of the same tokens can create a separate Capital Gains Tax calculation.

Where records cannot be fully reconciled, keep a written audit trail of the assumptions, source data and valuation methods used. A documented reconstruction is more defensible than unexplained figures copied from a single exchange summary.

If earlier tax returns may contain omissions, it is sensible to establish the correct figures and disclosure route before contacting HMRC. Where an HMRC enquiry or compliance check has already begun, specialist HMRC tax investigation support may help with the response and supporting evidence.

How Could HMRC’s New Data Affect Taxpayers?

The new statistics give HMRC a clearer baseline for understanding the cryptoasset gains already being reported through Self Assessment. CARF will add another source of information from cryptoasset service providers.

This does not mean every investor will receive an enquiry, and provider information does not by itself prove that tax has been underpaid. It does mean that discrepancies between a taxpayer’s return, exchange data and banking records may become easier for HMRC to identify.

HMRC also reported that its cryptoasset education and compliance activity generated an estimated additional £168 million of Capital Gains Tax in 2024/25. HMRC describes this as an estimate of the tax generated as a direct result of its compliance and education activity, not an estimate of any individual investor’s liability.

What Should Crypto Investors Do Before 31 January 2027?

A practical review should include five steps:

  1. List every exchange, wallet and protocol used.
  2. Download and preserve complete transaction data.
  3. Separate taxable disposals from transfers and income receipts.
  4. Calculate gains, losses and income using UK tax rules and sterling values.
  5. Reconcile the resulting figures to bank movements and the Self Assessment return.

Investors should also review earlier years for unreported income or gains. If an omission is found, check whether it should be corrected through Self Assessment or HMRC’s Cryptoasset Disclosure Service before making a submission.

Frequently Asked Questions

Do I Pay Tax When I Swap One Cryptoasset for Another?

A token-to-token exchange can be a disposal for UK Capital Gains Tax purposes. The calculation requires a sterling value at the time of the exchange and the allowable cost of the cryptoasset disposed of.

Does Moving Crypto Between My Own Wallets Create a Gain?

Generally, no. HMRC says there is no disposal where you retain beneficial ownership of the cryptoasset throughout the transfer. Records should still connect the sending and receiving wallets so the movement can be distinguished from a sale or transfer to another person.

Are Staking Rewards Taxed as Capital Gains?

Not necessarily. HMRC says staking rewards can be taxable as income when received. Whether the activity amounts to a trade depends on the facts. If you retain the rewarded tokens and later dispose of them, that later disposal can create a separate Capital Gains Tax gain or loss.

Will HMRC Automatically Tax Me When an Exchange Reports My Details?

No. CARF provider data does not itself calculate your tax liability. HMRC can use the information to compare reported activity with tax records, but the taxpayer remains responsible for declaring the correct income and gains.

Can an Accountant Help If I Have Used Several Exchanges?

Yes. An adviser can help consolidate transaction histories, distinguish transfers from disposals, calculate pooled costs and gains, review income events and prepare the relevant Self Assessment or disclosure figures. The reliability of the result still depends on the quality and completeness of the underlying records.

Apex Accountants’ View

HMRC’s new statistics are best treated as a prompt to review records rather than a reason for panic. The important question is not simply how many transactions appear on an exchange statement, but what each transaction represents under UK tax rules.

Apex Accountants supports individuals and businesses with cryptoasset tax calculations, Capital Gains Tax reporting, income treatment and HMRC compliance. Where records span several exchanges, wallets or tax years, the work can include reconstructing activity and documenting the assumptions behind the calculation.

Apex Accountants has more than 20 years of UK accounting and tax experience, with professionals connected to recognised bodies including ACCA, ICAEW and ATT. The aim is to produce an evidence-led tax position that can be explained if HMRC later asks how the figures were prepared.

Making Tax Digital for Income Tax 2026: What to Do Now

A sole trader may have completed the first MTD quarterly update without realising that the next deadline is already approaching. A landlord with a second income stream may also be above the threshold once both sources are combined. Making Tax Digital for Income Tax 2026 is no longer a distant reform: for the first mandatory group, the rules began on 6 April 2026.

This guide explains who is in scope, what has changed, which deadlines matter, and what to do if your records or software are not ready. It is based on current HMRC guidance checked on 28 August 2026. If you want professional support with setup and ongoing reporting, Apex Accountants’ Making Tax Digital accountants can help you prepare and manage the process.

Key Takeaways

  • Sole traders and landlords with qualifying income over £50,000 for 2024–25 should have started using MTD from 6 April 2026.
  • The next start dates are 6 April 2027 for qualifying income over £30,000 in 2025–26 and 6 April 2028 for qualifying income over £20,000 in 2026–27.
  • Quarterly updates are sent through compatible software and are cumulative. They do not replace the annual Self Assessment tax return.
  • HMRC will not apply penalty points for late quarterly updates during 2026–27, but digital records and quarterly updates are still required.
  • From September 2026, HMRC will start signing up people who need to use MTD for 2026–27 but have not already signed up, with enrolment taking place in stages.

What Is Making Tax Digital for Income Tax 2026?

Making Tax Digital for Income Tax requires qualifying sole traders and landlords to keep digital records and send quarterly updates to HMRC using compatible software. The updates provide HMRC with totals of self-employment and property income and expenses during the year, while the taxpayer still submits one annual Self Assessment tax return.

The obligation applies to people registered for Self Assessment who receive income from self-employment, property, or both and whose qualifying income exceeds the relevant threshold. HMRC’s official MTD eligibility guidance explains who needs to use the service and when.

MTD does not mean paying Income Tax four times a year. Quarterly updates are reporting obligations, not tax returns or payment demands. The normal Self Assessment payment timetable remains in place, with the full tax bill generally due by 31 January following the end of the tax year.

Who Must Use MTD for Income Tax and When?

You need to use MTD if you are a sole trader or landlord registered for Self Assessment, receive self-employment or property income, and your qualifying income is more than the relevant threshold for the tax year.

Qualifying income used by HMRCMTD start datePractical position
More than £50,000 in 2024–256 April 2026The first mandatory group should already be using MTD
More than £30,000 in 2025–266 April 2027Preparation should begin before the 2027–28 tax year
More than £20,000 in 2026–276 April 2028The threshold widens the MTD population further

Qualifying income is your total gross income from self-employment and property before expenses. If you have more than one relevant income source, those amounts are normally combined. HMRC explains the calculation in its guidance on working out qualifying income for MTD. You can also read Apex Accountants’ guide to Making Tax Digital income thresholds for a practical explanation of how the thresholds operate.

Partnerships do not currently need to use MTD for Income Tax as partnerships. HMRC says it will set out their timetable at a later date. A partner’s share of partnership profit also does not count towards that individual’s qualifying income, although their separate personal self-employment or property income may still bring them into scope.

Once you have started using MTD, falling below the threshold for one year does not automatically remove the obligation. HMRC says you can choose to opt out if your qualifying income remains below the relevant threshold for three tax years in a row. Different rules can apply if all self-employment or property income sources cease, so your position should be checked rather than assumed.

How Do Quarterly Updates Work for Sole Traders and Landlords?

Quarterly updates are totals of your self-employment and property income and expenses created from your digital records. HMRC’s current rules make these updates cumulative, meaning each update covers from the start of the tax year to the end of that update period. If you correct your digital records, the correction can flow through a later cumulative update without having to resend every earlier update.

For taxpayers using standard tax-year update periods, HMRC lists the following dates for 2026–27:

Cumulative period coveredQuarterly update deadline
6 April to 5 July 20267 August 2026
6 April to 5 October 20267 November 2026
6 April 2026 to 5 January 20277 February 2027
6 April 2026 to 5 April 20277 May 2027

You can check the full rules, including calendar update periods, in HMRC’s quarterly update guidance.

A quarterly update is only an in-year report. It does not complete your Self Assessment. After the end of the tax year, you still need to check the full-year information, make any necessary adjustments, add other income or gains, claim relevant reliefs and allowances, and submit your tax return through compatible software. For the 2026–27 tax year, the tax return and tax payment are due by 31 January 2028.

What Records and Software Do You Need?

You need digital records for the self-employment and property income and expenses covered by MTD. HMRC requires each digital income or expense record to include the:

  • amount
  • date the income was received or the expense was incurred
  • relevant income or expense category

You must also continue keeping the supporting records you normally retain for Self Assessment, such as invoices and bank statements. HMRC’s guidance on creating digital records for MTD explains the detailed record-keeping requirements.

If you use more than one software product, the products used to create your digital records and make submissions must be digitally linked. If you use a single product for the whole process, no separate digital link between products is needed.

HMRC does not provide the bookkeeping software itself. You or your agent must use software that works with MTD for Income Tax to create and store records, send quarterly updates, and submit the annual tax return. You can review HMRC’s guidance on choosing MTD-compatible software or use its MTD software finder.

You can continue using spreadsheets, but a spreadsheet on its own cannot submit the required information to HMRC. You will need compatible bridging software or another compatible product that connects to the spreadsheet. If keeping digital records accurately is becoming difficult, Apex Accountants’ bookkeeping services can help keep income and expenses organised throughout the year.

What Happens If You Miss an MTD Deadline in 2026–27?

HMRC has confirmed that it will not apply penalty points for late quarterly updates during the 2026–27 tax year. You still need to keep digital records and send any outstanding quarterly updates before you can submit your tax return.

This temporary treatment only applies to quarterly update penalties. Penalty points can still apply to a late tax return, and separate late-payment rules apply if tax is not paid on time. HMRC’s MTD penalty guidance confirms that late-payment interest runs from the first day a payment is late.

For your first year under the new late-payment penalty regime, HMRC gives you 30 days from the payment due date to either pay in full or contact HMRC to arrange a payment plan before late-payment penalties start. This 30-day period is available only once; after the first year, the initial period reduces to 15 days.

For tax years after 2026–27, missed quarterly update deadlines can generate late-submission penalty points. The threshold for mandatory MTD quarterly obligations is four points. Reaching four points triggers a £200 penalty, and each further missed submission deadline while at the threshold can trigger another £200 penalty.

What Should You Do If You Are Not Ready for MTD?

If you are already in the first mandatory group:

  1. Check your qualifying income against the correct tax year.
  2. Confirm that your Self Assessment details and income sources are up to date.
  3. Choose compatible software or appoint an authorised tax agent.
  4. Reconcile bank transactions, self-employment income, rental income and expenses.
  5. Correct any inaccurate digital records and keep a clear audit trail.
  6. Send any outstanding quarterly update as soon as possible.
  7. Prepare for the next quarterly deadline rather than waiting until the filing date.

From September 2026, HMRC will start signing up people who need to use MTD for the 2026–27 tax year but have not already signed up. HMRC says this will happen in stages. If HMRC enrols you, its guidance explains what to do after HMRC has signed you up for MTD.

Even if you have not received a letter, you remain responsible for checking whether the rules apply to you.

Some taxpayers are exempt. This includes certain people who are digitally excluded, as well as a number of automatic and temporary exemption categories. HMRC’s MTD exemption guidance explains the current rules. Being exempt from MTD does not remove the requirement to report taxable income and gains through Self Assessment.

How Can an Accountant Help With MTD for Income Tax?

An accountant can check the threshold calculation, review mixed self-employment and property income, recommend suitable software, and create a process for keeping records and meeting each quarterly deadline.

This can be particularly useful where you have several income sources, jointly owned property, changing business activities, or records spread across different bank accounts and systems. A regular review can identify missing expenses, duplicated transactions and income assigned to the wrong activity before the figures reach HMRC.

Professional support can also help keep quarterly updates consistent with the final Self Assessment tax return and make sure adjustments and reliefs are dealt with at the correct stage.

How Apex Accountants Help

If you are a sole trader or landlord affected by Making Tax Digital for Income Tax 2026, the immediate priorities are confirming your threshold, setting up a compliant digital record-keeping process and preparing your next quarterly update.

Apex Accountants can help with:

  • checking whether and when MTD applies to you
  • software selection and setup
  • digital record keeping and bookkeeping
  • quarterly update preparation
  • Self Assessment tax-return preparation
  • ongoing deadline and compliance support

If you are unsure whether your current setup is ready, you can book a free consultation to review your position with Apex Accountants.

The Sensible Next Step

If you are a sole trader or landlord affected by Making Tax Digital for Income Tax 2026, confirm your qualifying income, check that your software and digital records meet HMRC requirements, and prepare for the next quarterly deadline now.

If you have missed an update or are unsure whether your records are accurate, deal with the issue while the 2026–27 quarterly-update penalty easement is still in place rather than allowing problems to build up before the next tax year.

Frequently Asked Questions

Can I Still Sign Up for MTD If I Missed the First Quarterly Deadline?

Yes. If you are required to use MTD and have not signed up yet, you should sign up and catch up with your digital records and quarterly updates as soon as possible. HMRC will not apply penalty points for late quarterly updates during 2026–27, but the reporting requirement still applies.

Does MTD Replace My Self Assessment Tax Return?

No. Quarterly updates are summaries, not tax returns. You still submit one Self Assessment tax return each tax year. Once you are using MTD, the return must be completed and submitted through compatible software by 31 January following the end of the relevant tax year.

Do Landlords With One Property Need MTD Software?

Possibly. The number of properties is not the test. A landlord may need MTD if their total qualifying income from property and self-employment exceeds the relevant threshold and the other conditions are met.

For UK property, HMRC generally treats one or more UK properties as a single UK property business for MTD record-keeping purposes.

What If My Income Is Close to £50,000?

Use your actual qualifying income rather than profit or a rounded monthly estimate. Qualifying income is generally the gross amount from self-employment and property before expenses, based on the relevant Self Assessment tax return. Include the relevant sources together when checking whether you exceed the threshold.

Do I Need an Accountant for Making Tax Digital for Income Tax 2026?

No. An accountant is not legally required. However, you do need compatible software and must meet the digital record-keeping, quarterly update and annual tax-return requirements if MTD applies to you. An accountant can help reduce the risk of software setup errors, incorrect categorisation and missed reporting obligations.

What Happens If I Get the Figures Wrong?

You should correct inaccurate digital records as soon as you identify the error. Because quarterly updates are cumulative, corrected records can be reflected in a later update without resending every earlier quarterly update. Before submitting your annual tax return, you should check that the full-year figures are correct and make any required adjustments.

Book a Free Consultation