Autumn Budget 2026 Date Confirmed for 28 October

The Chancellor, John Healey, will deliver the Autumn Budget 2026 on Wednesday, 28 October, HM Treasury has confirmed. The confirmed budget date ends months of speculation about timing, and for directors and owners of UK limited companies, it is the single most important fiscal event of the year: one statement sets the tax arithmetic for the year ahead, at a moment when public finances are unusually tight and speculation about what the budget might change is running well ahead of the facts.

Key takeaways

  • The Budget 2026 takes place on Wednesday, 28 October, with fresh forecasts from the Office for Budget Responsibility on the same day.
  • Only the date is confirmed so far; the government has declined to preview any tax measures.
  • Four areas matter most to limited companies: fuel duty, threshold freezes, corporation tax and making tax digital.
  • A little preparation in October beats a January surprise.

What has been confirmed

The date itself. Updated forecasts from the Office for Budget Responsibility will accompany the Budget, and most commentators expect them to look gloomier than the set issued alongside the Spring Statement in March. 

Headroom against the government’s fiscal rules was already wafer-thin earlier in the year, and the Institute for Government notes that whatever the Chancellor announces must set the course for the rest of the parliament, reassure the markets and fund the government’s priorities all at once.

For company directors, the confirmed Autumn Budget 2026 date gives businesses a clear deadline to review cash flow, investment plans and tax exposure before any new measures are announced.

The government has put growth at the centre of its agenda, with more investment, more innovation and more jobs, and it has signalled that it intends to build on existing fiscal discipline rather than shake the financial markets. Beyond that, ministers have declined to preview any measures on the basis that responding to speculation only creates more of it. The budget itself will lay out the plans.

Measures already announced before the budget

The government has already introduced a handful of smaller measures designed, in its words, to give people and businesses “a little breathing space”:

  • VAT has come off household electricity bills from 1 October 2026 until at least March 2027, a saving of around £3.75 a month for the average household. 
  • Business rates relief now applies to pubs, social clubs and live music venues.
  • The £2 cap on single bus fares is back in place for the whole of 2027.

None of these directly change the tax position of a typical limited company, but they set the tone: the government wants visible cost relief where it can find the money, funded by reprioritising existing budgets rather than new borrowing.
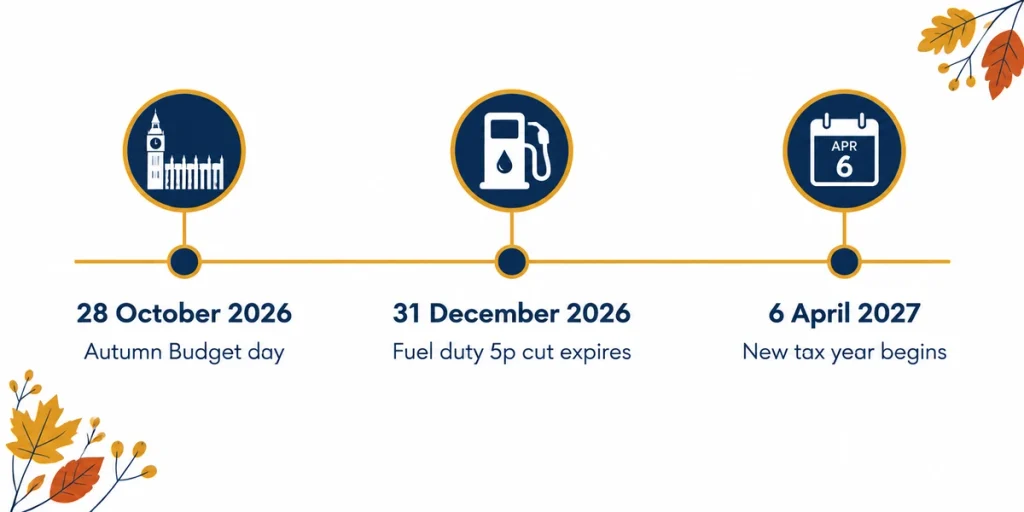
Autumn Budget 2026 timeline showing 28 October Budget day, 31 December fuel duty cut expiry and the 6 April new tax year

What the Autumn Budget 2026 could change for business owners

Several autumn budget 2026 predictions could affect companies and their directors, making it sensible to review current tax, investment and remuneration plans before 28 October. 

Fuel Duty 

Fuel duty will be an important area to watch at the autumn budget 2026. The current 5p-per-litre reduction is due to remain in place until 31 December 2026, after which the government will need to set the rates that apply from January 2027.

For businesses that depend heavily on vehicles, including those operating vans, delivery fleets, company cars or field-based teams, any change to fuel duty could have a direct impact on running costs. Companies may therefore want to factor possible changes into their transport budgets and cash-flow forecasts before making decisions for 2027.

Tax thresholds and allowances

Tax thresholds and allowances are the other quiet lever. Successive freezes to income tax and National Insurance thresholds have pulled more income into higher bands over time, and any extension of those freezes, or a fresh freeze on the personal allowance, would hit owner-managers who pay themselves through a combination of salary and dividends.Directors can check the current UK tax rules and allowances before reviewing how changes may affect their remuneration strategy.

While our expert self-assessment specialists can handle the filing side for directors, helping review salary and dividend income, check available allowances and ensure the return reflects the director’s wider personal tax position accurately.

Corporation Tax planning support

The corporation tax main rate is another area businesses should keep under review, particularly for companies above £250,000, where the 25% main rate applies.

For 2026/27, profits over £250,000 are taxed at 25%, while profits of £50,000 or less pay 19%, with marginal relief applying in between. The government has confirmed it will maintain these rates and thresholds for the financial year beginning 1 April 2027, subject to any future budget changes.

Our corporation tax planning helps directors understand how the current rate affects taxable profits and profit extraction. We also support companies with corporation tax calculations, return preparation, relief reviews and year-end planning to keep their tax position accurate and well managed.

Wider tax reform

Wider tax reform is another area businesses should watch closely. The Budget could provide an opportunity for changes affecting property and business taxation, although no specific measures have been confirmed. Company owners should therefore focus on announced policy rather than speculation and be ready to review their tax planning once the final measures are published.

Making tax digital 

Finally, digital tax reporting keeps rolling forward, regardless of the budget day headlines. Making Tax Digital for Income Tax continues its phased rollout, and company directors who also have self-employment or property income should already check whether their bookkeeping will meet the quarterly reporting requirements. For those within scope, MTD requires compatible software to keep digital records and submit quarterly updates to HMRC.

Our cloud accounting team can set up MTD-ready bookkeeping systems, connect compatible software and help ensure records are organised correctly before quarterly reporting begins.

Four practical steps to take before 28 October

  • Review your profit extraction strategy for the current tax year, including salary, dividends and pension contributions, so you can adjust quickly if thresholds or rates change.
  • Time to make major purchases sensibly. If you weigh up equipment, vehicles or IT investment, know whether any change to capital allowances could make acting before or after the Budget more efficient. A budgets and forecasting session maps the options on your numbers. 
  • Check your VAT position, particularly if you trade with the EU or sell digital services, as indirect tax tweaks are a common Budget feature. Our VAT team reviews your exposure before deadlines move. 
  • Book a review with your accountant in November. Budgets change the arithmetic of everything from dividend timing to payroll, and a post-Budget check of your numbers for the new tax year costs far less than a surprise in January.

How Apex can help

Apex Accountants will publish a full response to the Autumn Budget 2026 on the day, with a simple breakdown of every change that affects limited companies and their directors. Before then, our corporation tax and self-assessment specialists can review your current extraction strategy so you know exactly which budget decisions would affect you. If you would like a personal review of how the budget affects your business, book a consultation today! 

The bottom line

The 28 October budget will shape tax policy for the rest of this parliament. For limited company owners, the best approach is to stay calm: understand the confirmed facts, separate reliable information from Autumn Budget 2026 predictions, and have a plan ready for the changes that would actually affect your numbers. 

Director Tax Return 2025/26: New Self Assessment Rules for Close Company Directors

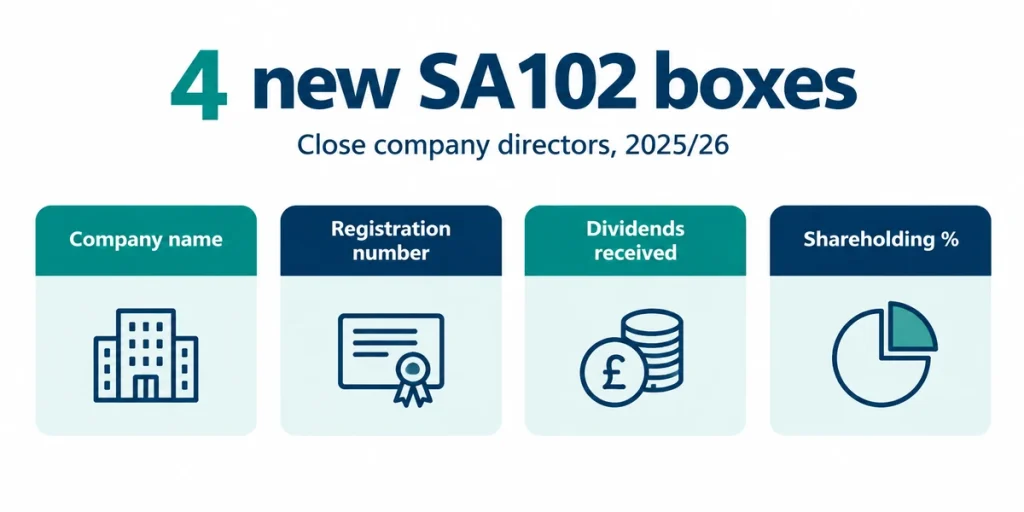
If you run an owner-managed or family company, your director tax return 2025/26 asks for more information than ever before. From the 2025/26 tax year, HMRC requires company directors to report the company name, its registration number, the dividends they received from that company and their highest shareholding percentage. The tax you pay does not change, but every missing item can cost £60, and the details you provide now let HMRC cross-check your return against your company’s accounts. The return is due by 31 January 2027 online. Here is exactly who the rules catch, what to report and what to do before you file.

Key takeaways

  • Company directors must complete new mandatory boxes on the employment pages from the 2025/26 return.
  • For each company you direct, report the company name, Companies House registration number, dividends received from it (enter 0 if none) and your peak shareholding percentage.
  • You need a separate employment page for every directorship you held during the year.
  • File online by 31 January 2027 (31 October 2026 on paper).

Who Do the New Rules Apply To?

The rules apply to directors of close companies who already complete a Self Assessment return. If HMRC already expects a return from you and you direct a close company, the new boxes apply to you. Any director in that position, paid or unpaid, is caught by the new reporting.

A close company, in simple terms, is a UK company controlled by five or fewer participators, or by any number of participators who are also directors. Participators include shareholders and anyone with a share in the company’s capital or income, including people entitled to distributions or benefits from it. That definition covers most owner-managed, family-owned and privately held businesses in the UK, so the vast majority of owner-managed companies fall inside it.

The rules reach further than directors formally registered at Companies House. They can also apply to people who act as directors without being formally appointed, including those falling within the relevant definition of a shadow director. Even unpaid directors of dormant close companies must complete the new boxes if they are already required to file a Self Assessment return. 

What Exactly Changed on the Director Tax Return SA102 Pages?

Before this year, the pages asked optional questions about directorships.From the 2025/26 return, close company questions carry mandatory additional information requirements. For each close company where you held a directorship at any point during the tax year, you must report four things on your director tax return:

  1. The company’s full name (box 7.1).
  2. Its Companies House registration number (box 7.2).
  3. The dividends you received from that company during the year (box 7.3), including nil. If you took nothing out, you enter 0, not a blank. This figure must match the dividend income on your main return.
  4. Your highest percentage of ordinary share capital at any point in the year (box 7.4). If your shareholding changed, report the peak, not the end-of-year figure.

Alongside these new reporting requirements, directors should also review their salary and dividend planning for 2026/27 to structure future withdrawals efficiently and consider the wider impact on both their personal and company tax position. 

You also complete a separate page for each directorship, so a director with two companies files two sets of employment pages. Dividends from close companies are now separated from your other UK dividend income on the main SA100 return, which makes the cross-check between your company accounts and your personal return automatic.

Infographic of the 4 new SA102 boxes for close company directors 2025/26: company name, registration number, dividends received and shareholding percentage.

Worked Example: Two Companies, One Return

Priya is a director of two close companies. She holds 60% of A Ltd and took £40,000 in dividends from it during 2025/26. She holds 25% of B Ltd and took nothing from it.

Her Self Assessment return requires a separate employment page for each directorship. For A Ltd, she enters the company name and registration number, £40,000 in dividends and a 60% shareholding. For B Ltd, she enters the company name and registration number, £0 in the dividend box and a 25% shareholding.

On her main return, the £40,000 sits in the dividend income section, and the 2025/26 dividend tax rules apply to it. Directors should consider reviewing how dividends interact with salary, allowances and their wider personal tax position. After the £500 Dividend Allowance, £39,500 of her dividend income remains taxable:

2025/26 tax bandDividend tax rate
Dividend allowance (first £500)0%
Basic rate8.75%
Higher rate33.75%
Additional rate39.35%

If her other taxable income has already used all of her basic-rate band, and the full £39,500 of dividends above the £500 Dividend Allowance falls within the higher-rate band, she owes approximately £13,331.25 in dividend amount of tax (£39,500 × 33.75%). 

What Should Close Company Directors Do Before Filing?

Four preparations make the new reporting straightforward:

  1. Gather every dividend voucher and board minute for each company you direct, so the dividend figure you report matches your records.
  2. Confirm your shareholding percentage for the year, including the peak if you transferred or issued shares mid-year. Alphabet shares and mid-year changes need careful calculation of the highest holding.
  3. Complete your Companies House identity verification so a mismatch does not delay your return.
  4. Reconcile your personal return against your company accounts before filing. The whole point of the new boxes is that HMRC can now compare the two automatically, so they must agree.

What Happens If You Get the New Boxes Wrong?

The new reporting requirement does not carry a separate filing charge, although taxpayers may incur software or professional-adviser costs. HMRC may charge a £60 penalty for failure to comply with the additional information requirement, regardless of the number of directorships or missing items. Standard accuracy penalties may also apply where an inaccurate return results in tax being understated and the relevant penalty conditions are met.

The context matters too. HMRC links the change to the tax gap, where small businesses account for a large share of missing revenue, and to transactions between companies and their owners. Because every close director in the company now discloses company-level details, HMRC can spot undeclared dividends and inconsistent records immediately. The professional bodies agree on the substance: the ICAEW and the ATT have both published member guidance on the new requirements.

When Are the 2025/26 Deadlines?

The 2025/26 return covers income from 6 April 2025 to 5 April 2026.Directors who still need to register should also check the Self Assessment registration deadline before preparing their return. 

 Key dates:

  • 31 October 2026: paper return deadline.
  • 31 January 2027: online return deadline.
  • 31 January 2027: payment of any tax due.

Directors who prepare dividend paperwork and shareholding records now avoid a January scramble with the new boxes.

Frequently Asked Questions

Do I complete the new boxes if I received no dividends? 

Yes. You enter 0 in the dividend box for each close company you direct. Leaving it blank counts as a missing item.

I am an unpaid director of a dormant close company. Do the rules apply to me?

Yes, if you already complete a Self Assessment return. Director status, not income, triggers the reporting.

Does every directorship need its own employment page? 

Yes. Each directorship you held at any point in the year requires a separate set of employment pages.

Does this change the dividend on tax I pay? 

No. The rules change what you report, not what you owe. Your tax on divident and other liabilities follow the existing 2025/26 rates.

What if my shareholding changed during the year? 

You report the highest percentage you held at any point in the tax year in box 7.4.

How Apex Accountants Can Help

We prepare proper Self Assessment returns for directors every January, and the new close company boxes are now a standard part of that service. Our team cross-checks your personal return against your company accounts so the dividend figures, shareholding percentages and registration numbers agree before anything reaches HMRC. 

We maintain your dividend vouchers and board minutes through our bookkeeping and company accounts services, handle salary and dividend planning for the 2026/27 year ahead, and manage multiple directorships in one place. If you direct a close company and want the 2025/26 return handled properly, contact Apex Accountants and we will take the paperwork off your desk.

Taking Money Out of Your Company: 2026 Rule Changes Explained

On 14 September 2026, HMRC closed its consultation on modernising the taxation of distributions and repayments of capital from companies. For owner-managed businesses, the consultation is directly relevant to taking money out of your company. In simple terms, the review examines the rules used to determine how payments and other value extracted by individual or trust shareholders are taxed, including dividends, certain reductions or repayments of share capital, share buybacks and the interaction between distributions and loans to participators. Some of these rules have remained largely unchanged since 1965. 

Nothing has changed yet. These are proposals, not law, and any reform would require future legislation, potentially through a Finance Act. However, the direction of travel is clear: HMRC wants economically similar payments to receive more consistent tax treatment, which could reduce the distinction between income and capital treatment that some owner-managed companies currently consider when planning shareholder extractions.

Key Takeaways

  • HMRC consulted from 23 June to 14 September 2026 on modernising the distributions framework, parts of which date back to 1965. The consultation is now closed, and responses are being considered. Nothing has been confirmed.
  • The consultation covers dividends, certain repayments or reductions of share capital, share buybacks, demergers and the interaction between distributions and loans to participators. These areas are central to company distribution rules UK guidance for individual and trust shareholders. Its main focus is payments and value transfers involving individual or trust shareholders; corporate shareholders are not the primary focus. 
  • The central aim is to give economically similar payments more consistent tax treatment. At present, qualifying capital gains are generally taxed at 18% or 24%, while dividend income above the dividend allowance is taxed at 10.75%, 35.75% or 39.35%, depending on the taxpayer’s band.
  • No new rule currently forces shareholders or companies to take action. However, extraction planning that relies on the difference between income and capital treatment should be reviewed, particularly where a transaction is planned but has not yet been implemented.
  • A sensible practical step is to discuss the intended salary and dividend mix with your accountant and retain evidence of the commercial rationale and relevant documentation for any proposed capital extraction. This is prudent planning advice, not a new HMRC requirement.

Rules for Taking Money Out of Your Company in 2026 

Most owner-managed directors use four routes: a salary through PAYE, dividends from accumulated profits, a director’s loan, or a capital distribution, such as a reduction of share capital or a final distribution when a company closes. If you are considering how to pay yourself from a limited company, these are the main routes under the current rules. The standard combination for a UK owner-director is a modest salary plus dividends. Our guide to balancing the best salary and dividend split for directors explains the usual mix in detail.

Current Tax Rates for Company Extractions

For anyone reviewing capital distribution tax UK guidance alongside salary and dividends, the headline rates for the 2026/27 tax year are: 

Tax on extraction, 2026/27RateNotes
Salary within the Personal Allowance 0% Income TaxThe standard Personal Allowance is £12,570, subject to restrictions such as tapering above £100,000. Salary is generally deductible for the company, although employer National Insurance and other employment-related costs may apply. 
Dividends: basic rate10.75%Rises to this rate from April 2026, first £500 allowance covers the start of dividend income
Dividends: higher rate35.75%Applies above the basic rate band
Dividends: additional rate39.35%Top rate of dividend tax
Capital distribution (CGT)18% or 24%18% within the basic rate band, 24% above it
Business Asset Disposal Relief18%Applies to qualifying business disposals made on or after 6 April 2026. The lifetime limit is £1 million per individual. It is not an automatic rate for every capital distribution, share buyback or company extraction. 

Note: These are headline individual tax rates for the 2026/27 tax year. The actual outcome depends on the shareholder’s total income, available allowances, the company’s circumstances, the legal form of the extraction and any applicable reliefs or anti-avoidance rules. The rates do not mean that every salary, dividend or capital payment will be taxed at the figure shown.

Read our guide on how dividends are taxed for the full breakdown of allowances and bands.

What Is HMRC’s Distributions Consultation?

The consultation, titled “Modernising the taxation of distributions and repayments of capital from companies”, was published on 23 June 2026 and ran for 12 weeks until 14 September 2026. It was announced as part of Tax Update 2026. The review could eventually affect parts of company distribution rules UK guidance. HMRC says the current rules generally operate well, but the commercial and legal environment has changed significantly. As a result, economically similar payments can sometimes receive different tax treatment depending on the route used. 

What the Consultation Covers

The consultation covers seven areas:

  • Capital on the shares: Whether the rules should be changed where restructuring arrangements allow value that is economically similar to a profit distribution to receive capital treatment and potentially fall within CGT rather than Income Tax.
  • Demergers: Whether the existing relief rules should be modernised and better targeted, particularly if changes restrict some non-statutory capital demerger routes.
  • Non-UK resident companies: Whether the income tax treatment of dividends and other distributions from non-UK resident companies should be aligned more closely with the treatment of distributions from UK-resident companies.
  • Debt and loans: Whether a priority rule should determine when an extraction is taxed under the distributions regime and when it is dealt with under the loans to participators regime.
  • Loans from non-UK companies: Whether a loans regime should apply to loans or advances from non-UK resident companies that would meet the close-company conditions if they were UK residents.
  • Purchase of Own Shares: Whether the existing relief should be clarified and kept focused on the situations in which capital treatment is intended.
  • Transactions in Securities: Whether these anti-avoidance rules should be modernised to address arrangements that produce an unintended tax advantage.

The document contains two important reassurances. The proposals are not intended to affect legitimate commercial restructurings, and they are not intended to affect corporate shareholders directly. The consultation is primarily focused on situations where the shareholder is an individual or trust within the charge to income tax, although some provisions could have wider technical effects.

This remains a proposal stage, not a change in the law. The government will analyse the responses and publish a summary, and it may consult further on particular reforms. Any resulting changes would require legislation.

Which Extraction Routes Could the Reform Affect?

If you are an owner-director planning around the income versus capital gap, three chapters matter most. First, any capital reduction strategy that relies on “capital on the shares” planning is squarely in scope. 

Second, share buybacks under the Purchase of Own Shares rules. 

Third, if your structure includes non-UK resident companies, the alignment proposals could change how dividends from those companies are taxed for UK shareholders.

The director’s loans also feature:

The consultation proposes a priority rule for when the loans to participators regime takes precedence over the distributions rules and considers extending the regime to loans from non-UK resident close companies.

If you use a director’s loan as a temporary extraction, our page on tax-efficient cash extraction strategies covers the current repayment rules and tax traps.

Could You Pay More Tax? A Worked Example

The honest answer is that nobody knows yet because HMRC has announced no replacement rates or final policy. However, the consultation identifies a possible risk for arrangements that rely on the difference between income and capital treatment. This is why capital distribution tax UK guidance remains important when comparing possible extraction routes. 

Here is a simplified illustration, assuming no other income, reliefs, allowable costs or available losses, and assuming the shareholder has sufficient higher-rate band:

A shareholder extracts £50,000 from the company under the current rules.

  • As a dividend: the £500 dividend allowance leaves £49,500 taxable. At 35.75%, the dividend tax is approximately £17,700.
  • As a qualifying capital gain eligible for BADR: at 18%, the tax would be approximately £9,000, assuming the full £50,000 represents a qualifying taxable gain and the relevant BADR conditions are met.
  • As a capital gain taxed at the main CGT rate: at 24%, the tax would be approximately £12,000, on the same simplified assumption.

The difference between the dividend calculation and the BADR calculation illustrates the type of inconsistency the consultation is examining. If future legislation resulted in economically similar extractions being taxed as income, a hypothetical £9,000 liability could move closer to the illustrative £17,700 dividend figure. But that is not a forecast: no such legislation has been enacted, and the final policy could be different.

The example is therefore a reason to review proposed extraction plans—not a reason to assume that the current rules have changed. You can use our dividend tax calculator to model dividend income under the current rates.

What Should Directors and Shareholders Do Now?

Nothing in the consultation imposes a deadline on you today. The sensible moves are preparatory, not reactive:

  1. Review your salary and dividend mix for 2026/27. A salary within the available Personal Allowance followed by dividends remains a commonly considered structure under the current rules, but the consultation does not guarantee that future reforms will leave every extraction strategy unchanged.
  2. If you are considering a capital extraction, company closure or share buyback, take advice on timing. Keep a clear record of the commercial rationale, the proposed transaction and the relevant company-law steps. HMRC has signalled it wants to distinguish genuine commercial transactions from planning that exists only for the tax outcome.
  3. If your group includes non-UK resident companies, look closely at the alignment chapters. The proposed alignment of the treatment of distributions from non-UK resident companies could be particularly relevant for UK-resident individual or trust shareholders with offshore company interests.
  4. Monitor the government’s response to the consultation. HMRC and the government are expected to consider the responses and announce next steps, but no publication date has been confirmed. Any reform would require legislation, potentially through a future Finance Bill. The timing, content and commencement date of any legislation remain unconfirmed.
  5. Do not rush a sale or extraction solely because the consultation has closed. The rules have not changed, and the closing date does not create a statutory deadline. Decisions should be based on the commercial purpose, tax position, legal requirements and the possibility—but not certainty—of future reform. 

BADR already increased from 14% to 18% for qualifying disposals made on or after 6 April 2026. That is an enacted change, separate from the proposals in this consultation.

Key Dates for the HMRC Consultation

DateEvent
23 June 2026Consultation published
14 September 2026Consultation closed; responses under review
To be confirmedGovernment response or summary of consultation responses.
To be confirmedAny draft legislation or further consultation 
To be confirmedAny enacted changes and their commencement date 

Frequently Asked Questions

How do I pay myself from my limited company?
For directors asking how to pay yourself from a limited company, the standard route is a salary through PAYE topped up with dividends from accumulated profits. A salary around the £12,570 personal allowance is tax-efficient for most directors, with dividends above it. Our salary and dividend split guide shows how the mix works in practice.

Can I take money out as a director’s loan?
Yes, as a temporary measure, but the loan must be repaid within nine months and one day after the company’s year-end to avoid the section 455 charge, and it should be documented properly. The consultation proposes a priority rule for when the loans regime applies instead of the distributions rules, so loan-based planning deserves a fresh review once the government responds.

Will dividends be taxed differently after the consultation?
No change has been announced. Dividend tax rates already rose by two percentage points in April 2026, to 10.75% and 35.75%, with the additional rate at 39.35%. The consultation is about the framework that decides whether a payment is income or capital, not about announced rate changes.

Do the proposals affect sole traders?
No. The distributions rules apply to payments from companies to their shareholders. Sole traders draw profits differently, without the company law layer, so this reform does not touch them.

What happens if I already took a capital distribution in 2026?
Existing completed transactions are assessed under the rules in force at the time. The consultation is forward-looking, and the government has said reform would only proceed after responses and impact analysis. If a past extraction was aggressive on the income versus capital boundary, a professional review of the file is sensible while the response is awaited.

How Apex Accountants Can Help

Our team advises owner-managed companies on exactly the areas this consultation touches. We review annual salary and dividend mixes and plan capital reductions and company closures with documented commercial rationale. We also guide share buybacks and demerger structures while monitoring HMRC consultations for changes that could affect your plans. If you are extracting money from your company and want your route stress-tested against the direction of this reform, book a call with us and we will review your structure with you.

Is the UK Tax System Too Complex for Small Businesses in 2026?

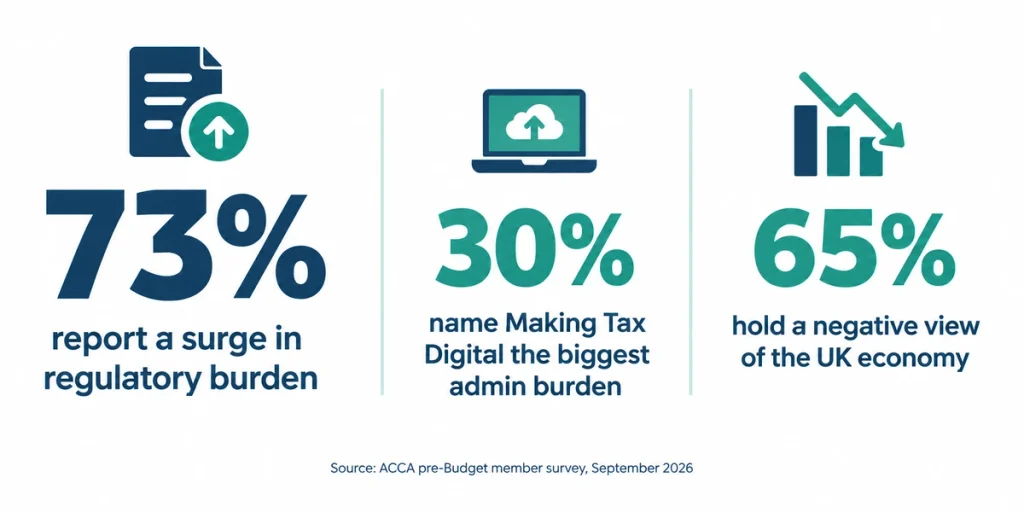
For many small businesses, keeping up with tax now means managing several filing cycles, digital reporting requirements and separate payment deadlines at the same time. A September 2026 member survey by ACCA, which represents more than 100,000 UK members, found that 73% of respondents said their regulatory requirements had surged over the previous 12 months. Making Tax Digital (MTD) was named the single biggest negative administrative burden by 30%.

The survey does not change any tax rules. However, it highlights a wider issue for small businesses: tax complexity carries a practical cost in time, systems and the risk of missed obligations.

Key Takeaways:

  • 73% of ACCA respondents said regulatory requirements had increased sharply over the previous 12 months.
  • Making Tax Digital was the biggest single administrative concern, cited by 30%, followed by reporting duplication at 10% and wider regulatory complexity at 8%.
  • MTD for Income Tax became mandatory from April 2026 for qualifying sole traders and landlords with income above £50,000.
  • There is currently no planned MTD for Corporation Tax rollout. Corporation Tax is being modernised separately.
  • A central compliance calendar, accurate digital records and suitable accounting software can reduce the risk of deadlines being overlooked.

What Did the ACCA Survey Find?

ACCA surveyed its UK members ahead of the next Budget to understand the pressures affecting businesses and the profession.

Alongside the 73% reporting increased regulatory requirements, 65% of respondents held a negative view of the UK economy, while only 4% were positive. The comparable positive figure was 29% in 2023.

When respondents were asked about administrative burdens, 30% selected Making Tax Digital as the biggest negative burden with little end-user benefit. General reporting duplication followed at 10%, systemic regulatory complexity at 8%, upcoming employment law changes at 7%, and Companies House verification processes at 7%.

There was some improvement in attitudes towards HMRC service levels. In August 2024, 89% of respondents said HMRC service problems negatively affected their organisation’s productivity and efficiency. By August 2026, that figure had fallen to 54%, although it still represented more than half of respondents.

ACCA has called for a wider review of the tax system and argued that simplifying tax administration could reduce errors and compliance costs while giving businesses greater certainty. These are recommendations to the government rather than confirmed changes to the rules businesses currently follow.

Why Is the UK Tax System So Complex for Small Businesses?

One reason is that businesses rarely deal with a single tax obligation.

A limited company may need to manage Corporation Tax, VAT, PAYE, National Insurance, benefits in kind, Companies House filings and, depending on the director’s circumstances, personal Self Assessment. Sole traders can face their own combination of trading income, property income, VAT and Self Assessment requirements.

Each regime also works to a different timetable. Understanding whether you need to register for Self Assessment is only one part of the picture, while limited companies must separately keep track of their Corporation Tax payment and filing deadlines.

Employers add another reporting cycle because payroll information generally has to be reported to HMRC on or before employees are paid. For businesses without an internal payroll function, outsourcing payroll administration can also reduce the number of recurring compliance tasks handled by the owner.

The difficulty is therefore not necessarily one individual deadline. It is keeping several different systems, dates and reporting requirements aligned throughout the year.

How Does Making Tax Digital Add to the Burden?

Making Tax Digital requires affected taxpayers to maintain digital records and use compatible software to make specified submissions.

MTD for VAT has applied to VAT-registered businesses for several years. MTD for Income Tax entered its mandatory phase on 6 April 2026 for sole traders and landlords whose qualifying income from self-employment and property exceeded £50,000 on their 2024/25 tax return.

Under the current MTD for Income Tax timetable, the threshold falls to more than £30,000 from April 2027 and more than £20,000 from April 2028.

For taxpayers who entered MTD for Income Tax in April 2026, the quarterly submission deadlines for the 2026/27 tax year are:

  • 7 August 2026
  • 7 November 2026
  • 7 February 2027
  • 7 May 2027

The first MTD quarterly update therefore had a fixed deadline of 7 August 2026 rather than a date individually set when a taxpayer joined.

HMRC has also confirmed that penalty points will not be applied for late quarterly updates during the 2026/27 tax year. Quarterly updates must still be submitted before the taxpayer can complete their annual tax return.

Importantly, businesses should not assume the same MTD model is being extended to Corporation Tax. HMRC’s current transformation programme says MTD will not be introduced for Corporation Tax. Instead, the Corporation Tax system and company tax return process are being modernised separately.

What Tax Deadlines Does a Small Business Face?

A typical small business can deal with several different deadlines during the same year.

ObligationTypical DeadlineFrequency
Self Assessment online return and balancing payment31 JanuaryAnnual
VAT return and paymentUsually 1 month and 7 days after the VAT period endsUsually quarterly
Corporation Tax paymentUsually 9 months and 1 day after the accounting period endsAnnual
Company Tax ReturnUsually 12 months after the accounting period endsAnnual
Private company accounts to Companies HouseUsually 9 months after the company year endAnnual
PAYE reportingOn or before each paydayEach pay run
PAYE and NIC payment to HMRCUsually by the 22nd of the following month when paying electronicallyMonthly or quarterly
MTD for Income Tax quarterly update7 Aug, 7 Nov, 7 Feb and 7 May for 2026/27Quarterly
P60Given to eligible employees by 31 MayAnnual
P11D, where applicable6 July following the end of the tax yearAnnual

The exact dates can vary according to the business and its circumstances. The broader problem is that several obligations can overlap, particularly for businesses that are VAT registered, employ staff and operate through a limited company.

What Happens If You Get It Wrong?

Different taxes have different penalty regimes, so it is important not to treat them as interchangeable.

Under the current Self Assessment late-filing rules, an online return filed after its deadline normally attracts an initial £100 penalty. If it remains outstanding for more than three months, additional daily penalties of £10 can apply for up to 90 days. Further penalties can arise after six and 12 months.

VAT operates differently. A late VAT return normally results in a penalty point. Once the relevant points threshold is reached, a £200 financial penalty can apply, with additional £200 penalties for subsequent late submissions while the business remains at the threshold.

Late private-company accounts filed at Companies House can attract a £150 penalty when they are up to one month late, with the amount increasing the longer the delay continues. Corporation Tax, VAT and other late tax payments can also attract interest and, depending on the regime, additional late-payment penalties.

For MTD for Income Tax, the position is different again. HMRC has introduced a points-based system, but it has confirmed that late quarterly updates will not receive penalty points during the 2026/27 tax year.

How Can Small Business Owners Cut the Admin Burden?

You cannot control the number of UK tax rules, but you can make your own compliance process easier to manage.

  1. Keep one compliance calendar. Put your VAT, Corporation Tax, Companies House, payroll, Self Assessment and MTD dates in the same system rather than monitoring them separately.
  2. Use compatible accounting software. Keeping records digitally throughout the year is much easier than reconstructing transactions immediately before a reporting deadline.
  3. Review obligations before thresholds are crossed. VAT registration, MTD and other requirements can change as turnover or qualifying income grows.
  4. Keep business and personal records separate. A dedicated business account and consistent bookkeeping make transactions easier to classify and reconcile.
  5. Decide which tasks should stay in-house. Some businesses can manage straightforward bookkeeping themselves, while others may find that outsourcing accounting work makes more sense once VAT, payroll, company filings and tax returns begin to overlap.

Frequently Asked Questions

Is the UK tax system too complicated for small businesses?

There is no single objective measure of whether a tax system is “too complicated”, but ACCA’s September 2026 survey shows significant concern among accountancy professionals. Some 73% of respondents reported a surge in regulatory requirements, while MTD, duplicated reporting and wider regulatory complexity were among the most commonly cited administrative burdens.

What is the biggest admin burden for small businesses?

In ACCA’s survey, Making Tax Digital was the most frequently selected negative administrative burden, cited by 30% of respondents. Reporting duplication followed at 10% and wider regulatory complexity at 8%.

Do small businesses have to use Making Tax Digital?

MTD for VAT applies to VAT-registered businesses unless an exemption applies. MTD for Income Tax is being phased in according to qualifying income from self-employment and property. It became mandatory from April 2026 for qualifying income above £50,000, with thresholds of more than £30,000 from April 2027 and more than £20,000 from April 2028.

Can I reduce tax admin without hiring an accountant?

Yes. Good bookkeeping, compatible software, a central deadline calendar and regular reconciliations can significantly reduce routine administration. Professional support may become more useful where several taxes overlap, the business is growing, or decisions require tax judgement rather than simple data entry.

What happens if I miss a Self Assessment deadline?

Under the ordinary Self Assessment late-filing rules, the initial penalty is normally £100. Additional daily penalties can begin after three months, with further charges after six and 12 months. Filing the outstanding return and paying any tax due as soon as possible can prevent further penalties and interest from accumulating.

How Apex Can Help

Managing several tax obligations at once can take attention away from running your business. Our outsourced accounting support can bring bookkeeping, VAT, payroll, year-end accounts and tax compliance into a more coordinated process.

If Making Tax Digital is creating additional work, we can help set up compatible cloud accounting, maintain digital records and keep quarterly submissions organised throughout the year.

Compliance is only one side of the picture. Effective business tax planning can also help you make appropriate use of available allowances and reliefs while keeping your approach within current UK tax rules.

If you have already missed a deadline or received a penalty, we can review the position, identify any available grounds for an appeal and help bring outstanding filings back up to date.

Book a free consultation, and we can map your business’s main tax and filing deadlines into one practical compliance plan.

EPC Tax Relief for Landlords as Agents Call for Tax Breaks

Letting agents and landlord bodies are pressing the government to make EPC tax relief for landlords available as private landlords face significant upfront costs under the confirmed 2030 Energy Performance Certificate (EPC) upgrade requirements. Without fiscal support, they warn, rental supply could shrink further at a time when housing demand is already outstripping availability. 

What the Government Has Confirmed

Following its January 2026 consultation response, the government’s position is now settled. The key rules are:

RequirementDetail
Minimum EPC standardBand C for all privately rented homes in England and Wales
Compliance deadline1 October 2030 — applies to new and existing tenancies
Spending cap£10,000 per property (reduced from the proposed £15,000)
Qualifying spend start dateOctober 2025 — expenditure from this date counts toward the cap
Non-compliance penaltyUp to £30,000 per property per breach
Cost-cap exemptionAvailable where band C cannot be reached after £10,000 is spent; valid for 10 years

The government is also introducing a new assessment framework under the reformed Home Energy Model, covering fabric performance, heating system efficiency, and smart readiness. This change means the compliance target itself is evolving—EPCs assessed under the new methodology, expected from late 2026, may produce different ratings than those issued today.

Industry Pushes Back on Fiscal Imbalance

At the centre of current industry pressure is a structural inequity that agents’ bodies argue the government has not yet resolved: landlords bear the full cost of retrofit works but do not directly benefit. Once improvements are made, tenants see lower energy bills, while property owners do not benefit from the funding.

Propertymark, the professional body for letting and estate agents, has set this out directly in its response to the Warm Homes Fund consultation. The body is calling for:

  • An updated Landlord Energy Saving Allowance that allows retrofit costs to be offset against rental profits
  • Recognition of energy efficiency works for Capital Gains Tax (CGT) purposes
  • Stamp Duty and Council Tax incentives linked to verified EPC improvements
  • Low-interest or government-backed loans for smaller landlords, with repayment terms that reflect the lifespan of retrofit works
  • Eligibility for Warm Homes Fund support to be linked to the property’s EPC rating, rather than the income of the current tenant, so improvements benefit successive occupants

Propertymark warns that without accessible and tailored support, the requirements risk pushing landlords toward selling rather than upgrading, reducing the supply of rental homes and increasing pressure on tenants.

Who Carries the Greatest Risk

The compliance burden is not falling evenly across the sector. Larger portfolio landlords can spread costs across multiple properties and manage cash flow disruption more readily. Smaller operators, particularly those with one or two properties, have far less room to absorb the outlay.

According to NRLA research, there are currently around 2.5 million rental homes in England that require improvements to meet the new standard. Smaller landlords are experiencing an accelerated exit due to the cumulative weight of Section 24 mortgage interest restrictions, rising income tax rates, and now mandatory retrofit costs. These are precisely the operators who supply housing in lower-demand markets where build-to-rent alternatives do not reach.

The 2030 deadline also presents a practical delivery challenge. The government’s own response references a growing shortfall of skilled retrofit tradespeople, meaning landlords who delay risk being unable to source qualified contractors in time, regardless of their willingness to invest.

What support exists for private landlord retrofit tax relief 

Available support is means-tested and variable in reach. The table below summarises the main routes currently open to private landlords:

SchemeWhat It OffersWho Qualifies
Warm Homes: Local GrantUp to £30,000 per property for energy upgrades and low-carbon heatingTenants in EPC D to G properties with household income below £36,000 or on qualifying benefits; landlords receive full funding for one property and 50% thereafter
Boiler Upgrade Scheme (BUS)£7,500 toward an air source or ground source heat pump; £5,000 for biomass boilersProperty owners in England and Wales replacing fossil fuel heating; it is not means-tested
Zero-rated VAT on qualifying measures20% saving on eligible energy-saving materials including insulation and heat pumpsAll landlords undertaking qualifying works

A notable point from the GOV.UK government response: third-party grant funding counts toward the £10,000 MEES cost cap. Landlords who secure grant support may reach the cap before spending their money to the ceiling, potentially unlocking the cost-cap exemption route sooner.

The Landlord Energy Saving Allowance, which once permitted deductions for cavity wall and loft insulation against rental income, was abolished in 2007. No equivalent has been introduced. Its reinstatement, in a form covering a broader range of qualifying measures, is central to demands for tax relief for private landlords undertaking retrofits. 

The Tax Treatment Trap Behind EPC Tax Relief for Landlords 

The absence of a dedicated allowance sits at the heart of the industry’s concern. Under current HMRC rules, how retrofit expenditure is treated for tax depends on the nature of the works:

  • Revenue expenditure (like-for-like repairs or replacements) can be deducted against rental profits in the year of spend, reducing income tax
  • Capital expenditure (improvements that enhance a property beyond its original condition) cannot be deducted against income; instead, it is added to the property’s base cost and reduces CGT only on eventual disposal

Most EPC-qualifying works, including heat pumps, solid wall insulation, and solar panels, are capital in character. They provide no in-year income tax relief. A basic-rate landlord funding a heat pump installation receives no direct tax saving until they sell the property, which may be many years away.

Propertymark’s proposal would treat qualifying energy efficiency expenditure as a deductible revenue expense, regardless of its capital character. This would provide immediate tax relief in the year costs are incurred and materially improve landlord cash flow. This is why EPC tax relief for landlords has become a central issue in the wider debate on funding retrofit works. The NRLA has gone further, calling for finance models that combine private investment with grants and tax incentives, allowing landlords to draw on multiple funding sources at the same time. 

The Supply Consequence

The stakes extend beyond individual landlord finances. The private rented sector provides housing for a substantial proportion of UK households, and the current tax environment is already discouraging new investment. A further contraction, driven by landlords choosing to sell rather than retrofit, would compound an already acute housing shortage.

This is not simply a financial matter. The Warm Homes Plan targets up to five million home upgrades by 2030. If private landlords exit the market rather than upgrade, the government’s own targets become harder to meet, and the households in poorest-quality rented accommodation, often those most vulnerable to fuel poverty, lose out.

Propertymark’s recommendation that eligibility for Warm Homes Fund support be linked to the property rather than the tenant’s income would allow improvements to remain in the housing stock for successive tenancies. Under the current means-tested model, a qualifying upgrade in one tenancy provides no guaranteed benefit to the next occupant.

How landlord EPC upgrade tax advice can help 

The intersection of EPC compliance and UK tax law is more complex than many landlords appreciate. Landlord EPC upgrade tax advice can help clarify whether retrofit expenditure is deductible in the year it is incurred or whether it must be capitalised and set against future gains. Getting the classification wrong can be costly. 

Apex Accountants & Tax Advisors works with private landlords, portfolio investors, and property companies to:

  • Classify retrofit expenditure correctly under HMRC guidelines to maximise available tax relief
  • Structure compliance costs in line with your overall portfolio strategy and cash flow position
  • Advise on the interaction between grant funding, the £10,000 MEES cap, and your income tax position
  • Plan for Making Tax Digital, which from April 2026 applies to landlords with qualifying rental income
  • Review CGT implications where EPC improvements affect the base cost of a property on disposal
  • Monitor legislative developments, including any reinstatement of retrofit allowances or new HMRC guidance

With the 2030 deadline approaching and government support still evolving, proactive tax planning is essential rather than optional.

Contact Apex Accountants today to review your EPC compliance position and ensure your retrofit strategy is as tax-efficient as possible. Book a free consultation with one of our specialist property tax advisers.

Digital Border Checks Expose Holiday Home Owners to Potential UK Holiday Home Tax Advice 

A system designed to count days rather than passports

The European Union’s new Entry/Exit System (EES) quietly changes how border officials record visits by non‑EU nationals, highlighting the need for clear UK holiday home tax advice for property owners. 

Since 12 October 2025, the system has replaced manual passport stamping with a digital record of your arrival and departure. When a UK passport holder enters the Schengen area, biometric data – fingerprints and a photograph – are captured and stored for three years. The rationale is better security and to stop visitors overstaying. For holiday home owners who used to cross borders with few questions asked, the new system means the authorities will know exactly how long they have been in the EU.

EES applies only to Schengen members – a group of 27 continental countries – and does not include the Republic of Ireland or Cyprus. Registration is automatic at the border, costs nothing and takes place on arrival. However, the process can lengthen queues, as travellers must submit fingerprints and have their photograph taken. After completion, the digital record replaces passport stamps and is used each time you enter or exit the Schengen area.

Why counting days matters for UK holiday home tax advice 

EES is a border security tool, but it also makes it easier for tax authorities to police residency rules. Under the Schengen “90‑days in any 180‑day period” rule, UK visitors cannot spend more than three months in the bloc without obtaining a visa. The digital record provides an irrefutable log of days spent in each country and can be cross‑referenced with local tax systems. 

For example, Spain, France and Portugal treat anyone who spends more than half of the year in their territory as a tax resident. Previously, holiday home owners could argue about precise arrival dates when challenged; now, the system holds that information centrally.

For UK tax purposes, the statutory residence test is equally sensitive to day‑counting. HM Revenue & Customs (HMRC) says you are normally UK resident if you spend 183 or more days in the UK during the tax year, or if your only home was in the UK for 91 days or more and you stayed there at least 30 days. 

Conversely, you are usually a non-resident if you spend fewer than 16 days in the UK or if you work abroad full-time and spend fewer than 91 days in the UK. Residency determines whether you pay UK tax on your worldwide income or just on your UK income. EES data will make it harder to argue residency status if your personal records do not align with your digital travel history, emphasising the importance of UK holiday home tax advice. 

Overseas property income is treated separately

UK residents must pay income tax on foreign rental income. HMRC’s property income manual explains that rent and other receipts from properties outside the UK are taxed as the profits of an overseas property business. Profits or losses are calculated like those of a UK property business, but they are taxed separately: losses from one cannot be set against the other. 

The profits are chargeable to income tax only if the business is carried on by a UK resident. Before April 2025 some non‑domiciled individuals could elect to be taxed only on income remitted to the UK, but the Foreign Income and Gains (FIG) regime now generally subjects all UK residents to tax on their worldwide income.

HMRC guidance also notes that while most foreign income is taxed like UK income, there are special rules for pensions, certain employment and rent from property. If you have multiple overseas properties, you can offset losses between them but not against UK properties. 

All foreign rental income must be reported in the foreign section of your Self Assessment tax return, following UK property tax guidance for overseas homes. If you owe tax, you must register for Self Assessment by 5 October following the end of the tax year. The return must include income already taxed abroad if you plan to claim foreign tax credit relief.

Risks for holiday home owners

Holiday home owners in Spain, Portugal or France often spend months at a time enjoying the sun or refurbishing their property. With EES registering each entry and exit, EU authorities can easily check when a visitor has surpassed the 90‑day limit. Some governments are expected to use this data to identify individuals who may be inadvertently meeting their domestic residency thresholds. If you stay in a country for more than 183 days, you may owe income tax there on your worldwide income. EES will also highlight repeated stays that may signal an undeclared holiday letting business.

From a UK perspective, lengthy stays abroad can complicate your residence status. Spending long periods in Spain or France reduces your days in the UK and could result in your becoming non‑resident, which would normally mean you pay UK tax only on your UK income. But even if you become a non‑resident, your overseas property profits may still be taxed in the country where the property is located. Meanwhile, UK‑resident owners must continue to pay UK tax on those profits. Coordinating tax obligations across two jurisdictions becomes more complex, and mistakes can trigger penalties or interest.

Another risk is failing to report the rental income of a foreign holiday home, which is why UK property tax guidance for overseas homes is essential. HMRC’s guidance makes clear that you must include foreign rental income on your tax return and cannot offset losses against your UK property business. The digital record created by EES, combined with data‑sharing agreements across Europe, makes it easier for tax authorities to match property ownership with travel patterns and identify unreported income. Those who have relied on the low visibility of short‑term lets may find themselves subject to scrutiny.

Practical steps and tax planning for holiday home owners 

To reduce the risk of investigation, holiday home owners should do the following:

  • Track time spent in the EU – Keep a personal log of entries and exits that matches the EES record, which supports tax planning for holiday home owners. Plan trips to stay within the 90‑day‑in‑180‑day limit and ensure you do not inadvertently create tax residence in the country where your property is located.
  • Review your UK residency status – Use the statutory residence test as guidance. Remember that 183 days in the UK usually makes you resident, while fewer than 16 days normally means you are non‑resident.
  • Declare all foreign rental income – Register for Self Assessment if you have any foreign income. Use the foreign section of your tax return to report rents, even if tax was deducted overseas.
  • Keep separate accounts for overseas properties – because overseas property profits cannot be netted against UK property profits, you should maintain clear records of income, expenses and any tax paid abroad.
  • Monitor upcoming changes – The EU’s travel authorisation system (ETIAS) is expected to start in late 2026. Check the official guidance and ensure you obtain authorisation when required.

How Apex Accountants can help

Holiday home ownership brings lifestyle rewards and tax complexities. Apex Accountants & Tax Advisors combine expertise in UK tax law with an understanding of EU residency rules. We help clients evaluate how EES data may affect their tax residency, plan their time abroad to stay within the 90‑day rule, and organise their affairs to avoid dual‑taxation pitfalls. Our advisory services include:

  • Residence status reviews – We analyse your travel patterns and family ties to determine your UK tax residence and advise you on the implications.
  • Foreign income reporting – Our team prepares Self Assessment returns, ensuring that we correctly report overseas rental income and claim foreign tax credits where available.
  • Cross‑border tax planning – We work with partner firms in the EU to coordinate tax obligations, so you comply with both UK and local laws and avoid penalties.

Whether you are purchasing a holiday home, already own one, or plan to spend more time abroad in retirement, Apex Accountants can provide tailored advice to help you stay compliant with changing border and tax rules. Contact us today to discuss your circumstances and plan with confidence.

Frequently asked questions

What is the EU Entry/Exit System, and when did it start?
The EU’s Entry/Exit System is a digital border record. From 12 October 2025, UK passport holders are required to provide fingerprints and a photograph at their first entry into the Schengen area. The system replaces passport stamps and stores your travel data for three years.

How long can UK citizens stay in the Schengen area without a visa?
You can stay for up to 90 days in any 180‑day period. The EES makes it easier to enforce this rule, and there is a penalty approach for exceeding it.

Do UK residents pay tax on income from overseas holiday homes?
Yes. If you are a UK resident, you normally pay UK income tax on foreign rental income. The profits from an overseas property business are calculated like a UK property business but taxed separately.

How do I know if I’m a UK resident for tax?
HMRC uses a statutory residence test based on the number of days you spend in the UK. Spending 183 days or more in the UK usually makes you resident, while fewer than 16 days usually makes you non‑resident. Other factors, such as having your only home in the UK or working full time here, can also make you resident.

What steps should I take if I rent my holiday home?
You must register for self-assessment and report your overseas rental income in the foreign section of your tax return. Keep detailed records of rents and expenses and seek advice on claiming any foreign tax credits.

Will the EES information be shared with HMRC?
The EES is operated by the EU for immigration control. While there is no public statement that data will be directly shared with HMRC, tax authorities across Europe are increasingly using digital records to enforce residency rules. Holiday home owners should therefore assume that HMRC may use their travel data to verify tax status.

Disqualified Director Jailed for £3M Insolvency Fraud Funding Lavish Lifestyle

A recent Insolvency Service investigation exposed a £3 million insolvency fraud by former director Tariq Sarwar (59), who syphoned money from the sale of his company’s only asset and hid it through other firms. Sarwar’s scheme left creditors – including HMRC – with over £500,000 unpaid, while he and his family enjoyed a luxury Cheshire lifestyle (even a Rolls-Royce). The fraud involved a network of companies and accounts managed by Sarwar and associate Christopher Francis (40), who laundered funds back to Sarwar. Both men have now been sentenced (see table).

Name (age)OffenceSentence
Tariq Sarwar (59)Insolvency fraud: transferring £3.1m from company sale without paying debts; acting as a director while disqualified4 years’ imprisonment<br>10-year director ban
Christopher Francis (40)Money laundering: helped launder Sarwar’s funds2 years 1 month (suspended 2 years)<br>250 hours unpaid work

Table: Key facts on the fraud and sentences (Insolvency Service press release).

How the £3 Million Fraud Worked

Background of the £3 million Insolvency Fraud Case: 

Sarwar’s company, A Property Management Ltd, owned a Salford business park. In mid-2018, HMRC moved to wind it up for £130,000 unpaid tax. Sarwar knew the company was in trouble. In June 2018 he sold the property for just under £5.1 million.

Money Transfers

Instead of paying creditors, Sarwar ordered the remaining £3.1 million into KYCA Trading Ltd, run by Francis. Within days, the cash was shuffled through a web of six other companies to hide its origin. Investigators later traced hundreds of thousands back to Sarwar’s family business and personal accounts. In one audit trail, £645,000 went to a firm controlled by his relatives, and a further £748,980 went back into his own account.

Cover Story

When questioned, Sarwar denied involvement. Francis claimed (incredibly) that £700,000 was paid as a deposit on five penthouses – a transaction he couldn’t verify with any documents. Investigators found this story unbelievable. Records showed Francis’s own company, KYCA Trading, had just been slapped with a 6-year director ban in 2021 for poor accounts. (He told police his car with all business records had been stolen and burnt out overnight – another unverified excuse.)

Lifestyle Contrast

While creditors got little back (only “a limited return” eventually), Sarwar’s family was living large. He had a six-bedroom Cheshire farmhouse filled with designer goods, and his son appeared on TV show Rich Kids Go Skint in 2019 boasting he’d never been on a bus – the family owned a Rolls-Royce chauffeur for him. This stark contrast helped tip off investigators that something was amiss.

Read: When Director Bans in the UK Are Ignored – Lessons From a Landscaping Tax Case

Roles of the Two Men in the £3 Million Insolvency Fraud

Tariq Sarwar

Former director of the insolvent property firms. He admitted fraud charges: hiding company assets when winding-up was imminent, and illegally acting as a director while disqualified. (Sarwar had already been banned for 11 years in 2013 for siphoning company funds – a ban that ran until late 2024.) In June 2026 he pleaded guilty, receiving 4 years in jail and a 10-year ban from being a director.

Christopher Francis

Business associate and controller of KYCA Trading Ltd. He laundered Sarwar’s money through other companies. Francis was also disqualified in 2021 for accounting failures. He pleaded guilty to money laundering and got 2 years 1 month in prison, suspended for 2 years, plus 250 hours of unpaid work. (Suspended means he only goes to jail if he breaks the law again.)

The Insolvency Service is now pursuing confiscation of Sarwar’s ill-gotten gains to ensure he doesn’t keep what was never rightfully his.

Disqualification and Penalties

A company director disqualification means a person is legally barred from running a company. In the UK this is governed by the Company Directors Disqualification Act 1986 (CDDA). Key points:

  • Disqualification orders (for up to 15 years) are imposed by courts for “unfit conduct” – like fraud or abusing insolvency rules. Sarwar’s 2013 ban was for taking £260k from company funds when creditors were owed £1.6m.
  • While disqualified, a person must not act as a director or manage a company in any way. Breaking this is a criminal offence. Penalties include up to 2 years’ jail and/or a fine. The court can also extend the ban if someone re-offends.
  • Sarwar blatantly broke this rule by controlling companies between 2014–2018, despite his 11-year ban. Francis also breached his 2021 ban. Authorities can even hold enablers (those acting on behalf of a banned director) liable, and impose fresh disqualification periods on top.

In practical terms, disqualified directors are heavily restricted. They cannot form, promote or be involved in any UK company without special court permission. Also, any company debt they incur can be treated as a personal liability if they secretly direct a firm.

Practical Takeaways and Protection Tips

  • Check Director Status

Before doing business, always verify that company directors are not disqualified. The Companies House register shows director names. You can search by name or company to see current officers.

  • Watch for Warning Signs

If a company is sold suddenly at fire-sale prices or large sums move through unexpected accounts, ask questions. Insolvency agents look for unusual money movements and lifestyle clues (like expensive purchases) that conflict with business figures.

  • Record Keeping

Keep clear, independent financial records. The law requires directors to keep accounts and file taxes. Disqualified or unscrupulous directors often fail at this (as Francis did), which itself is a red flag.

  • Use Official Resources

The UK government’s Director Information Hub offers guidance on director duties and the signs of company distress. The Insolvency Service’s Investigations Unit can be contacted if fraud is suspected.

  • Report Suspicious Directors

If you know someone is acting as a director despite a ban, you can report them. The Insolvency Service suggests anonymously tipping off Crimestoppers (0800 555111).

Taking these steps helps protect your business and the wider economy. As experts, we at Apex Accountants emphasise compliance and transparency to avoid such traps.

Also Read: £20 Million VAT Carousel Fraud Case: Lessons for UK Directors and Businesses

How We Help Businesses Stay Compliant 

At Apex Accountants, we specialise in corporate compliance, accounting and insolvency advisory. We help businesses and directors:

  • Maintain proper records: We ensure accounts are up-to-date and filed on time, avoiding penalties and suspicions of wrongdoing.
  • Navigate disputes: If your company faces cash flow trouble or creditor claims, we offer guidance on legal obligations and restructuring options.
  • Perform due diligence: Before mergers, investments, or major transactions, we conduct background checks on all directors and companies involved.
  • Advise on Insolvency: Our team assists with voluntary administrations, liquidations or negotiations with HMRC, ensuring the process follows the law.
  • Provide training: We offer workshops on director duties and early insolvency warning signs, so your management team stays alert to risk.

If you’re concerned about fraud risks, company debt or director misconduct, contact Apex Accountants. Our insolvency advisory services will guide you through UK regulations and help safeguard your business against illegal practices.

Conclusion

This case of £3 million insolvency fraud shows the severe consequences when directors flout the rules. Sarwar and Francis abused corporate structures to hide money, but the Insolvency Service’s investigation led to jail time and bans. It’s a stark reminder that disqualifications are serious. Keeping clear financial practices, performing checks on business partners, and acting lawfully are key. Our firm is dedicated to helping clients stay compliant and protect their assets – so fraudsters can’t exploit them.

FAQ

What is a disqualified director?

    A director is disqualified when a court bans them (often up to 15 years) for misconduct. They legally cannot manage or run any company during that ban.

    What does acting as a director while disqualified mean?

      It means secretly directing or controlling a company despite a court ban. This is a criminal offence, punishable by up to 2 years in prison. In this case, Sarwar did so and received an extra 10-year ban.

      How did Tariq Sarwar commit fraud?

        He sold his company’s property for over £5 million, then diverted £3.1 million through other companies instead of paying creditors. This deprived HMRC and suppliers of funds they were owed.

        Who was Christopher Francis and what did he do?

          Francis ran KYCA Trading Ltd and helped launder Sarwar’s £3m. He admitted money laundering and got a suspended sentence and community service.

          How were the fraud funds traced?

            Investigators followed money through multiple firms. They tracked large sums back into Sarwar’s family companies and personal accounts, proving the scheme.

            What happened to the creditors?

              Creditors (including HMRC) were owed over £500,000 when the fraud emerged. HMRC and others were only later repaid in part after investigations.

              What penalties did Sarwar face?

                He pleaded guilty to fraud and breaching his disqualification. The court jailed him for 4 years and banned him from being a director for 10 years.

                Can wronged companies or creditors get money back?

                  The Insolvency Service is working on confiscation proceedings to recover funds. In similar cases, recovered assets can go to creditors. In this case, HMRC was repaid in full later.

                  How can businesses avoid such fraud?

                    Always verify directors’ credentials on Companies House, keep diligent records, and watch for unusual transactions. Seek professional accounting advice if a partner’s behaviour seems suspicious.

                    What should I do if I suspect a director is behaving illegally?

                      Contact professionals (like our firm) for advice. You can also report suspicions to the Insolvency Service or anonymously via Crimestoppers (0800 555111) if a ban is breached. Acting early can prevent serious losses.

                      HMRC’s AI-Driven Tax System In The UK: Promises, Pressures And The Road To Digital Taxation 

                      HM Revenue & Customs (HMRC) has set itself an ambitious goal: by 2030, 90% of customer interactions should be digital, forming the backbone of its AI-driven tax system UK. That goal underpins a wider transformation plan that includes generative artificial intelligence (AI), enhanced data platforms and the migration of services to cloud infrastructure. In interviews with Microsoft’s UK division, HMRC’s chief artificial intelligence officer said generative AI will help streamline compliance checks and handle mundane queries but that people will always make the final decisions. This article examines how HMRC is building an AI‑driven tax system, why it matters to UK businesses and taxpayers, and what challenges lie ahead.

                      From tax return to AI-driven tax system UK experience 

                      The move toward an AI-driven tax system rests on several pillars. HMRC’s transformation roadmap describes a future in which it will redesign services such as pay‑as‑you‑earn (PAYE), self‑assessment and inheritance tax for online channels. Customers will receive “digital nudges” and pre‑populated data to help them get their tax right. The agency plans to use GOV.UK One Login for authentication, replacing different credentials with biometric verification, and to use digital assistants and generative AI chatbots instead of call centre scripts. The aim is not just convenience but cost efficiency: by 2030 HMRC expects to handle the majority of interactions online, freeing staff to focus on complex cases.

                      Those intentions are more than wishful thinking. HMRC has already used machine learning for years in its compliance programme; its Connect system, built at a cost of £80 million, cross-checks tax returns against more than 55 billion items of third-party data, from banks to property records. In 2023, the agency recorded a tax gap—the difference between the theoretical amount owed and the sum collected—of 5.3% or £46.8 billion, with small businesses accounting for 60% of that shortfall. A more proactive digital regime promises to narrow this gap through targeted interventions. For example, HMRC plans to pre‑populate self‑assessment returns with data from employers and banks and to build an AI‑powered tariff service to help businesses classify goods for customs.

                      Technology and partnerships underpin the shift

                      Executing this vision requires modern IT infrastructure and data governance. HMRC has embarked on a £175 million partnership with Quantexa, a London-based analytics firm, to unify fragmented data and create a “single customer view”. The contract is intended to support sovereign, governed AI that identifies tax at risk and improves customer service. Migrating to a cloud platform also allows HMRC to scale AI models and deploy generative agents securely. Microsoft notes that HMRC is trialling AI tools to summarise customer complaints and queries, predict debt default, and assist call handlers by drafting responses. Such tools reduce time spent on administrative tasks and allow skilled staff to focus on compliance.

                      However, not all AI interventions provide excellent value. Recognising these concerns, the Cabinet Office launched an AI Opportunities Action Plan in early 2025 to ensure evaluation of AI tools for performance, fairness and cost‑benefit. HMRC’s generative AI guidelines also stress that software must be transparent about its sources, avoid hallucinating facts, and be subject to human oversight. Those guidelines prohibit software from pretending to act on behalf of HMRC or exposing sensitive personal data. Ethical design and robust governance are therefore integral to the new tax system.

                      Business impact and AI compliance for small businesses considerations 

                      For employers and companies, the shift to digital will bring both opportunities and obligations. Payroll agents will gain real-time visibility over PAYE liabilities once HMRC’s new employer account goes live, benefiting from AI tax technology for payroll and self-assessment. Digital reminders could help businesses avoid late filing penalties and reduce the administrative load of quarterly reporting. Pre‑populated returns may simplify self-assessment for company directors and partners, while digital inheritance tax services could accelerate probate.

                      Yet the change also demands investment. Firms must ensure their accounting software is compatible with HMRC’s APIs and updated for generative AI features. The agency warns that AI‑powered tools must not misrepresent their outputs as definitive; tax advisers remain responsible for reviewing filings. Businesses will need to invest in cybersecurity and training to protect customer data and to understand AI recommendations, supporting ongoing AI compliance for small businesses. There is also a risk of digital exclusion: HMRC’s research shows that many taxpayers lack digital confidence. Smaller businesses—who already account for the majority of the tax gap—may struggle to adapt without support in AI compliance for small businesses. HMRC has promised to support these groups through assisted digital services and local advice hubs.

                      Risks and ethical considerations

                      AI can amplify biases if trained on skewed data. HMRC’s own systems carry the risk of false positives, particularly when scouring third‑party datasets for mismatches. Taxpayers wrongly flagged for non‑compliance may face unwarranted scrutiny. To mitigate these risks, the government’s evaluation framework emphasises fairness and accuracy. Human oversight is another safeguard: generative AI may draft letters or summary notes, but final decisions on compliance will remain with HMRC staff. Transparency obligations will require HMRC and software developers to explain how they reach AI conclusions and to provide avenues for appeal.

                      How Apex Accountants & Tax Advisors can help

                      As the tax system evolves, businesses need expert guidance to navigate the new landscape. Apex Accountants & Tax Advisors combines technical knowledge of UK tax law with practical experience of digital transformation. Our consultants can help you:

                      • Select and implement accounting software that meets HMRC’s API and security requirements;
                      • Interpret generative AI outputs and ensure that human review safeguards are in place;
                      • Plan for changes to PAYE and self-assessment processes, including the move to pre‑populated data and digital inheritance tax;
                      • Assess the impact of AI on record‑keeping and internal controls.

                      Apex also offers compliance reviews and bespoke advisory services to reduce the risk of penalties and to identify opportunities for tax optimisation. Contact us today to discuss how we can support your business through HMRC’s AI‑driven tax reform.

                      FAQs: AI-driven tax compliance

                      How will HMRC’s AI‑driven tax system affect my small business? Small businesses will see more digital interactions with HMRC, including pre‑populated returns and digital reminders. This could reduce administrative burdens but will require software upgrades and attention to cybersecurity. Since small businesses currently represent 60% of the tax gap, HMRC will likely focus on their compliance.

                      Will AI eliminate the need for human accountants? No, HMRC’s chief AI officer has emphasised that generative AI will assist with routine tasks but that human officials will make the final decisions. Accountants remain essential to interpret complex scenarios and ensure compliance with UK tax law.

                      What are HMRC’s rules on AI tax software? HMRC’s generative AI guidelines require software to be transparent about data sources, avoid hallucinations and provide users with warnings to check outputs. Developers must also ensure strong data protection and ethical design.

                      When will digital PAYE accounts become mandatory? HMRC plans to roll out an online employer account that will eventually replace paper processes. While no statutory deadline has been announced, businesses should prepare for increasing digitalisation well before 2030.

                      How can my company prepare for pre‑populated tax returns? Start by ensuring your payroll and banking data are accurate and integrated, making full use of AI tax technology for payroll and self-assessment for pre-populated returns. Review how your accounting software exchanges data with HMRC and consider engaging a tax adviser to validate AI‑generated entries before submission.

                      How Debt Assignment Is Taxed as Shareholder Income 

                      UK corporate law and HMRC guidance have long recognised that transactions between a company and its shareholders are subject to specific scrutiny. One scenario increasingly under attention is the debt assignment taxed as shareholder income and the tax implications when such a transfer is treated as an income distribution. The consequences extend beyond bookkeeping, potentially triggering significant corporation tax and income tax liabilities.

                      When Debt Becomes Income

                      The fundamental principle is straightforward: a company cannot simply execute a debt assignment taxed as shareholder income without considering the tax treatment. If a company transfers or forgives a debt owed by itself to a shareholder, HMRC may view the transaction as a distribution of value, rather than a mere accounting adjustment. Under UK law, such distributions are generally treated in line with dividend rules. The value of the debt assigned can therefore attract income tax in the hands of the shareholder, at rates corresponding to dividend income, rather than being ignored or classified as capital repayment.

                      This interpretation applies whether the debt is operational, a loan advanced to the company, or arises from accrued but unpaid remuneration, and it highlights the tax implications of shareholder debt in the UK. HMRC’s perspective is driven by the principle that shareholders should not receive tax-free benefits under the guise of intra-company debt arrangements.

                      Implications for Shareholders and Companies

                      For shareholders, the immediate consequence is a potential income tax liability on a transaction that may not have involved cash. This is particularly relevant for small and medium-sized enterprises, where directors often hold both executive and ownership roles. The assignment can lead to unexpected tax bills if the shareholder has not accounted for the assigned value in their self-assessment return.

                      Companies face parallel risks. The act of assigning or forgiving debt can be considered a “deemed distribution”, affecting corporation tax calculations and emphasising the need for UK corporate tax guidance for shareholders. Accounting entries must reflect not only the reduction of receivables but also the recognition of distributions where HMRC guidance applies.

                      Practical Scenarios and Risk Areas

                      Several common circumstances illustrate the risk and underline the tax implications of shareholder debt in the UK: 

                      • Director loans written off: Forgiving a director loan without formal repayment agreements may be classified as income.
                      • Shareholder debt transfers: Assigning corporate liabilities to shareholders can inadvertently create a taxable event.
                      • Settlement in kind: Paying off obligations by transferring debts instead of cash is not exempt from income tax consideration.
                      • Intercompany restructuring: In mergers or internal reorganisations, assigning debt may trigger both corporate and personal tax obligations if structured incorrectly.

                      The recurring theme is that HMRC evaluates the economic reality over the form. Taxable distributions can arise even when no money changes hands, particularly if the shareholder derives personal benefit.

                      Apex Accountants & Tax Advisors: Guidance in Action

                      For companies navigating these complex waters, expert advice is crucial. Apex Accountants & Tax Advisors can assist in several ways:

                      • Tax planning: Advising on structuring debt assignments to minimise the risk of creating taxable distributions.
                      • Compliance review: Ensuring all intercompany loans and shareholder transactions meet HMRC standards.
                      • Reporting support: Preparing accurate accounts that clearly distinguish between genuine capital repayments and deemed income distributions.
                      • Risk mitigation: Identifying potential liabilities before transactions occur, including corporation tax and Section 455 exposure.

                      Through detailed analysis and proactive structuring, companies can reduce unexpected personal tax burdens on shareholders and avoid costly compliance issues. Contact Apex Accountants today to discuss debt assignment strategies and protect your company and shareholders from unintended tax liabilities. 

                      Strategic Steps for Directors

                      Directors should consider guidance and advice in line with UK corporate tax guidance for shareholders: 

                      • Maintaining formal loan agreements and documenting repayment terms.
                      • Consulting tax professionals before forgiving or transferring shareholder debt.
                      • Reviewing corporate governance policies to ensure alignment with HMRC requirements.
                      • Considering the timing and valuation of any debt assignment to optimise tax treatment.

                      FAQs

                      Q1: Is a debt assignment to a shareholder always taxable?
                      Not always. HMRC evaluates whether the assignment constitutes a distribution of value. If it does, it is taxable as dividend income.

                      Q2: How is the value of the assigned debt calculated?
                      The amount of the debt forgiven or transferred generally forms the taxable base, reflecting its fair market value at the time of assignment.

                      Q3: Can a shareholder offset this income against other taxes?
                      Standard dividend allowances and applicable tax reliefs may reduce the effective tax liability, but proper accounting and reporting are essential.

                      Q4: What are the risks if the company does not report the assignment correctly?
                      Incorrect reporting can trigger penalties, interest, and potential scrutiny of other related-party transactions.

                      Q5: Does corporation tax apply to debt assignments to shareholders?
                      Yes. In some cases, the assignment is treated as a deemed distribution, which may impact corporation tax calculations and potentially trigger Section 455 loans to participators’ charges.

                      Q6: How can Apex Accountants help with these scenarios?
                      Apex Accountants provides tailored advisory services to structure transactions correctly, ensuring compliance and minimising both personal and corporate tax exposure.

                      Book a Free Consultation