
-
CALL US 0203 883 4777
2026-27 VAT Fuel Scale Charges: Key Changes and What They Mean for Your Business
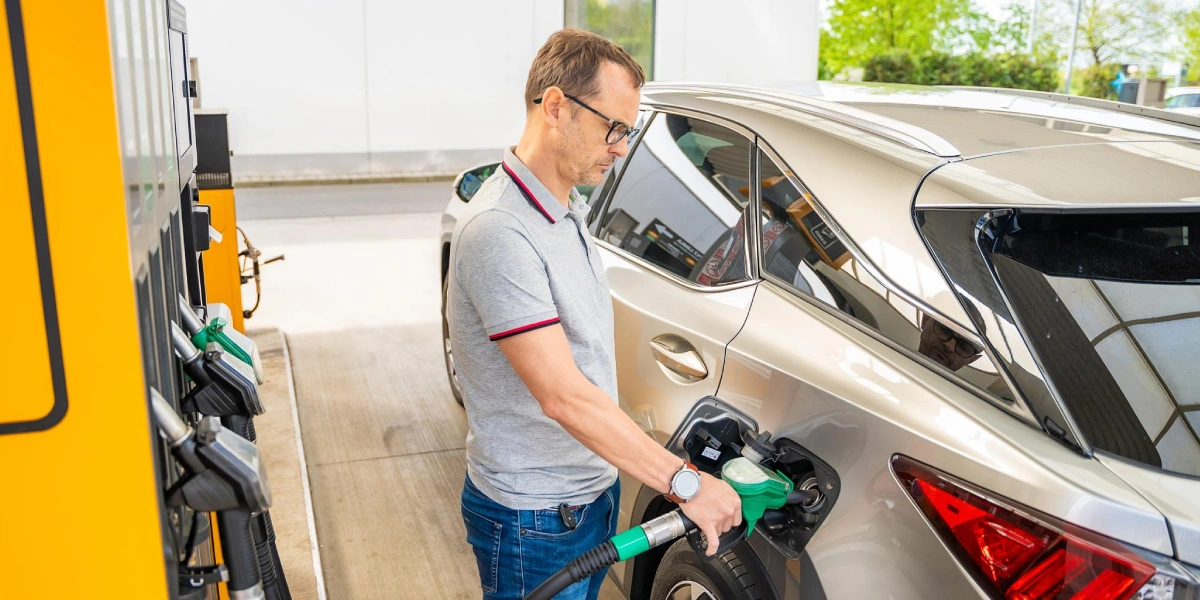
From 1 May 2026, the UK VAT road fuel scale charges change to cover the period to 30 April 2027. These flat-rate charges apply when a business reclaims VAT on vehicle fuel but a car is used for private travel. In practice, instead of keeping detailed mileage logs, a fixed scale charge is added to the VAT return to account for the private fuel usage. The new charges (VAT-inclusive) are set by CO₂ emission band and by the length of the VAT accounting period (1, 3 or 12 months). Businesses must start using the updated scales in the first VAT period beginning on or after 1 May 2026.
What is a fuel scale charge?
A fuel scale charge is a fixed VAT amount a business pays when it reclaims VAT on fuel that is also used for private journeys. The amount is based on the vehicle’s CO₂ emissions and the length of the VAT accounting period.
Typical 2026/27 charges include:
| CO₂ (g/km) | 12-month charge (£) | 3-month charge (£) | 1-month charge (£) |
| 120 or less | 657.00 | 163.00 | 54.00 |
| 140 | 1,182.00 | 294.00 | 98.00 |
| 180 | 1,708.00 | 426.00 | 142.00 |
| 225 or more | 2,297.00 | 574.00 | 190.00 |
Table: Example VAT fuel scale charges for 2026–27 (VAT inclusive).
Read: How Company Car Tax Bands Work and What You Will Pay
Who Must Use Fuel Scale Charges?
VAT-registered businesses may need to use a fuel scale charge where the business pays for fuel, the vehicle is also used privately and the business reclaims all the VAT on that fuel. The scale charge accounts for output VAT on the private-use element without requiring the business to separate every business and private journey.
Businesses can instead reclaim VAT only on fuel used for business journeys, provided they keep detailed mileage records. They can also choose not to reclaim VAT on vehicle fuel, although HMRC rules apply consistently across vehicles where this option is used.
If an employee or director pays for private fuel from personal funds and the business only reimburses or reclaims VAT relating to business mileage, a fuel scale charge will generally not be required.
If you are unsure whether reclaiming all fuel VAT and applying the scale charge is appropriate, our VAT services can help review your fuel arrangements, VAT recovery and reporting position.
Key Changes for 2026–27 VAT Road Fuel Scale Charges
The 2026–27 rates are slightly lower than in 2025–26, following official adjustments. For instance, the top band (225+ g/km) charge fell from £2,314 to £2,297 per year, and the lowest band (≤120 g/km) fell from £661 to £657 per year. All businesses using the fuel scale must switch to these new figures for any VAT period starting 1 May 2026 or later. The published guidance makes clear that “the VAT road fuel scale charges are amended with effect from 1 May 2026” and must be used from that date onwards.
How to Calculate Your Fuel Scale Charge
Identify the car’s CO₂ emission band
Check the official CO₂ figure from the vehicle logbook, the DVLA database, or the manufacturer’s certificate. If the exact figure isn’t a multiple of 5 g, round it down to the nearest 5 (e.g. 143 g becomes 140 g). If the vehicle has more than one CO₂ figure (e.g. separate figures for petrol and hybrid modes), use the lowest or the combined rating as advised.
Special case – older cars:
Cars registered before 1997 may lack a CO₂ figure. In that case, use engine size to pick a band: up to 1,400 cc = 140 g/km band; 1,401–1,999 cc = 175 g/km band; 2,000 cc or more = 225 g/km band.

Choose period and charge:
Determine your VAT accounting period (1, 3 or 12 months). Then look up the corresponding charge for your CO₂ band. For example, a car at 125 g/km is in the 125 band, giving a charge of £246 for 3 months or £81 for 1 month (see table above).
Pro-rate if needed:
If the vehicle was used privately for only part of the VAT period, pro‑rate the charge. Calculate the percentage of the period during which the car was used, and apply that to the scale charge. For example, if the accounting period is 12 months but the car was used only 6 months, a 50% adjustment applies. This approach is confirmed in the guidance: “record [the percentage] of the accounting period. Apply this percentage to each road fuel scale charge to get a total figure”.
Include on the VAT return
The fuel scale charge (which already contains VAT) is added to the VAT return as output tax owing on fuel. In other words, businesses reclaim input VAT on fuel normally, then add the flat scale charge to Box 1 of the VAT return for the period.
Also Read: VAT on Car Hire in the UK – What Businesses Need to Know
Worked Example: Fuel Scale Charge and Net VAT Position
Suppose a VAT-registered business has a petrol company car with CO₂ emissions of 145 g/km and submits VAT returns quarterly. Under the 2026/27 HMRC table, the three-month fuel scale charge is £311, including £51.83 of output VAT.
Assume the business also buys £900 of fuel, including VAT, during the quarter and is entitled to reclaim the full VAT of £150.
| Vehicle | 3-month scale charge | Output VAT | Input VAT reclaimed | Net fuel VAT position |
| Petrol car, 145 g/km CO₂ | £311.00 | £51.83 | £150.00 | £98.17 net input VAT |
The business therefore reclaims £150 of input VAT on the fuel but accounts for £51.83 of output VAT through the fuel scale charge, leaving a £98.17 net VAT recovery in this example.
The fuel scale charge is separate from the Benefit in Kind rules that can apply to company vehicles. Businesses assessing whether a company car remains tax-efficient can use our guide to company car tax bands and what you will pay to compare the wider tax costs before making or reviewing a vehicle decision.
Applying the Scale Charge
- One driver per car:
The scale charge is applied per person-car combination. Each employee or director using a company car privately incurs one charge for that vehicle. If more than one person uses the same car, each must be treated separately.
- Multiple cars:
Where an individual has multiple cars, apply the same steps to each vehicle. If two cars happen to fall in the same CO₂ band for the same person, HMRC notes they “should be treated as if they were one car” when calculating percentages. In practice, this rarely affects the outcome compared to treating them separately.
- Record-keeping:
Keep records of how each charge was calculated (CO₂ figure sources, period length, and any percentage used). This protects you in case of a VAT inspection.
- Electric/hybrid vehicles:
A fully electric car does not use VATable fuel, so the fuel scale does not apply. For plug-in hybrids or conventional hybrids, use the petrol/diesel CO₂ band as above.
How We Can Help You Deal with VAT on Automobiles
- VAT Return Support: We help businesses apply the correct fuel scale charges on each VAT return. Our team will ensure the right CO₂ band and period are used, so the fuel VAT is calculated correctly.
- Company Car and Expenses Advice: Our experts can advise on company car tax and benefit rules. We explain the fuel scale method and alternatives (like mileage logs) so you choose the best option.
- Record-Keeping and Compliance: We can set up simple spreadsheets or software entries to track usage percentages and keep evidence of CO₂ figures. This ensures your accounting is robust for HMRC review.
- Proactive Updates: Tax rules change frequently. We monitor official updates (such as the new 2026/27 rates) and notify our clients promptly. You can rely on Apex Accountants to keep you compliant without surprises.
Our dedicated advisers stay current with all HMRC rules and can guide you through the fuel scale process. If you provide cars or fuel to staff, our firm can take the stress out of calculating and reporting these VAT charges correctly.
For more details or personalised support, get in touch with the Apex Accountants team. We can help you implement the new VAT fuel scale charges smoothly and ensure your VAT returns are accurate.
FAQs About Fuel Scale Charges in UK
What if fuel is paid by personal funds?
The scale charge only applies when the company reclaims fuel VAT. If an employee buys personal fuel with no VAT reclaimed, no output tax is due.
How to find a car’s CO₂ figure?
Check the car’s V5C logbook, or use the DVLA online vehicle checker or the manufacturer’s data. Use certificates if needed.
Q: Where do I find my car’s CO₂ figure for the scale charge table?
A: Use the figure on the car’s V5C registration certificate or the manufacturer’s official combined CO₂ emissions figure. The scale charge band is set by that figure, so an error here means the wrong output tax.
Recent Posts
Business Rates Relief 2026: Could the Threshold Increase?
The current relief thresholds have not changed. Business rates relief 2026 has not adopted a £17,096 exemption threshold. A newspaper...
Taking Money Out of Your Company: 2026 Rule Changes Explained
On 14 September 2026, HMRC closed its consultation on modernising the taxation of distributions and repayments of capital from companies....
Is the UK Tax System Too Complex for Small Businesses in 2026?
For many small businesses, keeping up with tax now means managing several filing cycles, digital reporting requirements and separate payment...
Payrolling Benefits in Kind: What Employers Must Do by 2027
From 6 April 2027, the way UK employers report some benefits in kind will change significantly. Company cars, car fuel,...
UK Wealth Tax: Would Business Owners and High Earners Pay?
Owning a valuable business does not necessarily mean having substantial cash available personally. Equally, earning a high salary does not...

Self Assessment Registration Deadline: What to Do Before 5 October 2026
We’re increasingly asked by clients who started trading during 2025/26: “Do I need to register for Self Assessment?” It’s a...

R&D Tax Relief 2026: New HMRC Rules and How to Claim Successfully
We’re seeing more companies come to us after having their R&D tax relief claims questioned, returned, or rejected by HMRC....
HMRC Auto-Registration for MTD: What Happens If You Don’t Sign Up First
Sole traders and landlords are increasingly asking what happens if they do not respond to Making Tax Digital sign-up letters....
A Complete Guide to UK Airbnb Tax: Rules, Reliefs and Rates for 2026/27
A host can receive regular Airbnb bookings and still be unsure whether HMRC sees the income as a small side...
Inheritance Tax Planning: A Practical UK Guide for 2026
A couple in their late sixties own a home worth £750,000 and have £700,000 in savings and investments. Their combined...