MTD for Income Tax: What Sole Traders and Landlords Should Do After the First Deadline

A client came to Apex Accountants last week, a sole trader with two income streams, unsure whether she had met her first Making Tax Digital obligation correctly. She had filed her quarterly update on time, but when we reviewed her records, several property expenses were miscategorised and one invoice was duplicated. The submission was technically complete, but the figures feeding into her year-end tax return were already drifting.

This is the reality for many sole traders and landlords right now. HMRC says more than 436,000 people submitted their first quarterly update for 2026-27, and over 570,000 have signed up to the service. But submitting on time and getting the records right are two different things. If you are in scope of MTD for Income Tax, the work does not stop after the first deadline.

Key Takeaways

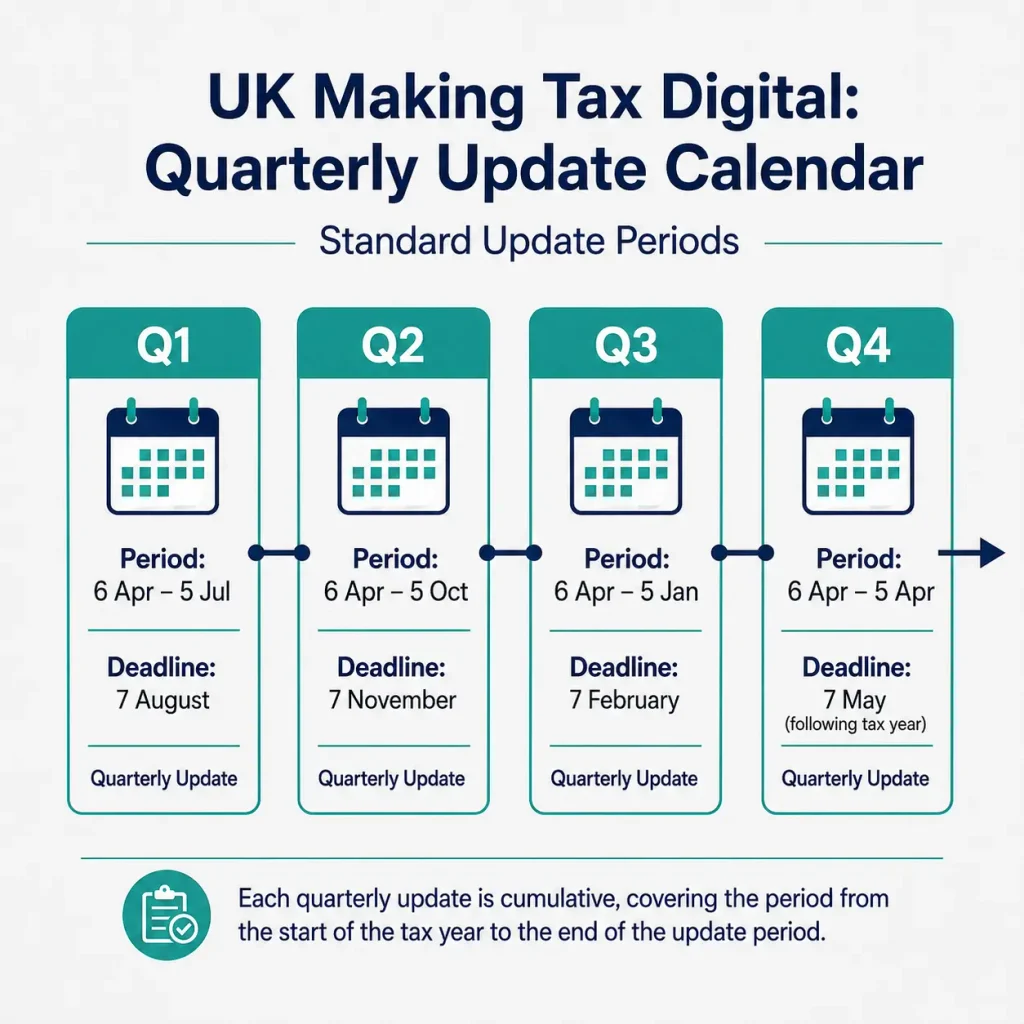
  • First quarterly update deadline was 7 August 2026 – covering 6 April to 5 July 2026 (standard period)
  • No penalty points for late quarterly updates during the 2026-27 tax year, but late Self Assessment returns and late payments still carry penalties
  • Next quarterly update deadline: 7 November 2026 – covering 6 April to 5 October 2026
  • From September 2026, HMRC will start signing up eligible taxpayers automatically if they have not signed up themselves
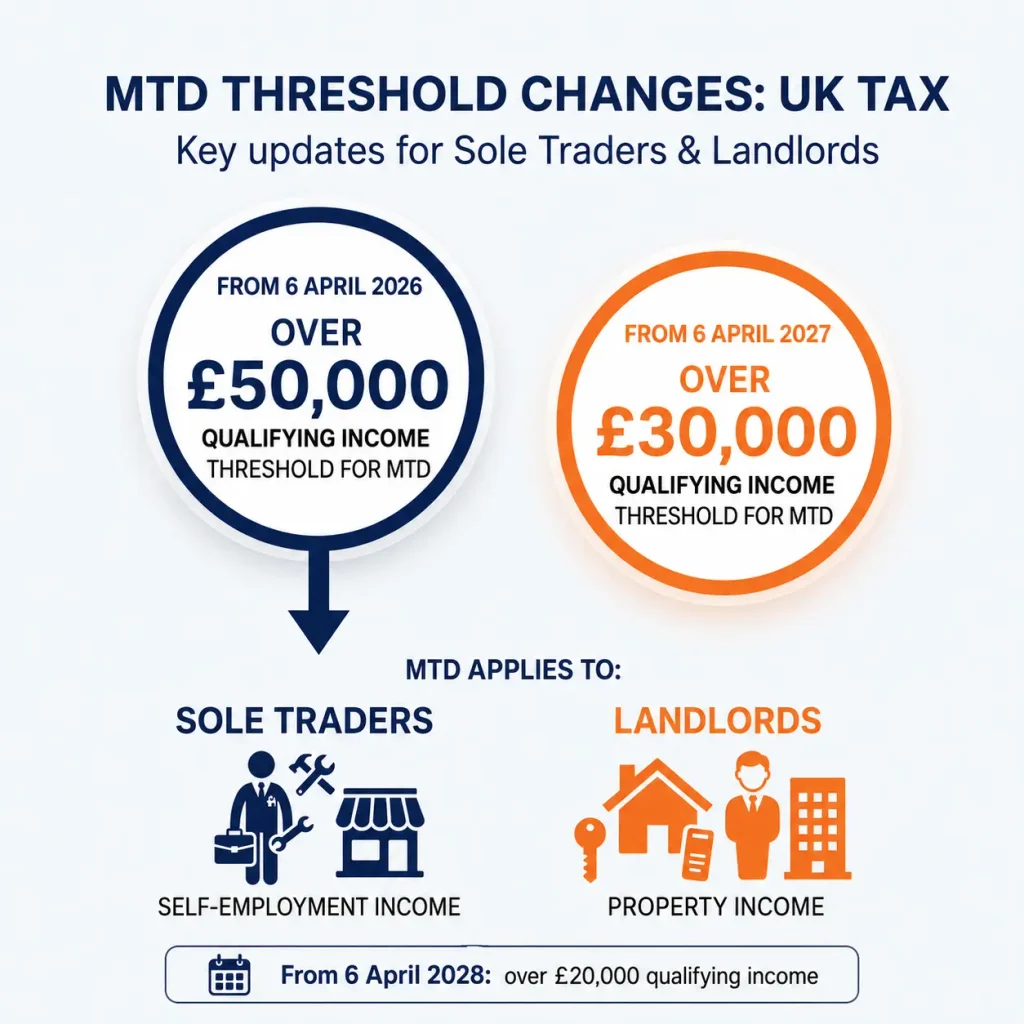
  • From April 2027, MTD will apply to those with qualifying income over £30,000, down from over £50,000 for 2026-27
What happens after you submit your first MTD quarterly update?

After your first quarterly update is submitted through compatible software, HMRC has a summary of your income and expenses for that three-month period. You can view an estimate of your tax position through your software, and the figures you submitted will feed into your annual Self Assessment tax return. Nothing else is due immediately – the next action point is the second quarterly update, due by 7 November 2026.

However, the submission itself does not guarantee your records are accurate. If your digital records contain miscategorised expenses, duplicated entries, or missing income, those errors flow through to every subsequent update and into your final tax return. The best time to check is now, while the first period is fresh and corrections are straightforward. This is where professional bookkeeping services become valuable – ensuring your digital records are accurate from the start prevents compounding errors across all four quarterly updates.

What should you do if you missed the 7 August deadline?

If you missed the first quarterly update deadline, you should submit the outstanding update through your MTD-compatible software as soon as possible. HMRC has confirmed that no penalty points will be issued for late quarterly updates during the 2026-27 tax year, so there is no financial penalty for the delay – but the update is still legally required, and leaving it outstanding creates a larger backlog when the next deadline arrives.

The practical steps are:

  • Open your MTD software and locate the missing quarterly update for the period 6 April to 5 July 2026.
  • Review your digital records for that period – bank transactions, invoices, property income, expense receipts.
  • Check that income and expenses are categorised correctly before submitting. If you use bookkeeping software that feeds into your MTD tool, verify the categories match.
  • Submit the update through your software. HMRC will process it and update your tax position.
  • Set a reminder for 7 November 2026 – the next quarterly update deadline.

If you are unsure whether MTD applies to you at all, check your qualifying income. The threshold for 2026-27 is over £50,000 from self-employment and property income combined. For a full breakdown of how the rules work, our Making Tax Digital services page explains the scope, thresholds, and what Apex Accountants does to keep clients compliant. You can also read our earlier guide on the rules for MTD for Income Tax for a deeper look at how quarterly updates interact with Self Assessment.

How do quarterly updates differ from the annual Self Assessment return?

Quarterly updates are short digital summaries of your income and expenses, sent every three months through MTD-compatible software. They are not tax returns, and no tax is payable because of a quarterly update. The annual Self Assessment tax return remains due by 31 January, and quarterly updates must be submitted to be able to file the final return.

The distinction matters because some taxpayers assume that filing quarterly updates means their tax return is done. It is not. The quarterly updates feed into the annual return, but you still need to review the full year, make any tax adjustments (capital allowances, private use adjustments, pension relief), and submit your tax return by 31 January 2028 for the 2026-27 tax year.

What are the MTD penalty rules for 2026-27 and beyond?

For the 2026-27 tax year, HMRC will not issue penalty points for late quarterly updates. This is a transitional arrangement to help taxpayers adjust to the new system. However, penalties for late Self Assessment returns and late tax payments still apply under the relevant rules – these are separate from the quarterly update penalty rules.

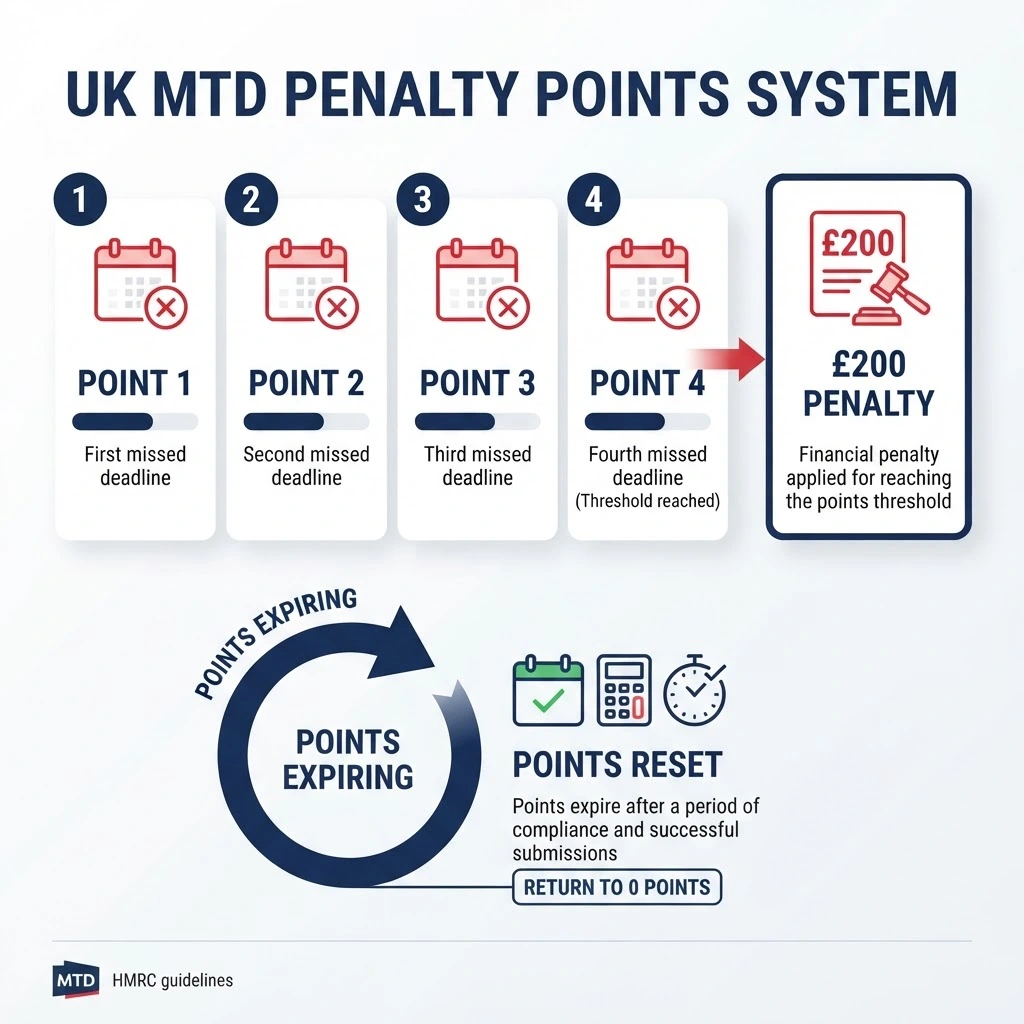
From 6 April 2027, a points-based penalty system will apply to missed quarterly deadlines. Taxpayers receive one penalty point for each missed quarterly deadline. Once four points are accumulated, a fixed £200 penalty is charged, and every further late submission after that triggers another £200 penalty. Points below the threshold expire automatically 24 months after the missed deadline. Once the threshold is reached, points reset to zero after quarterly updates and the tax return are submitted on time for 12 months and any outstanding quarterly updates and tax returns for the previous 24 months have been submitted.
When does HMRC start signing people up automatically?

From September 2026, HMRC will begin signing up customers who should be using MTD for Income Tax for the 2026-27 tax year but have not yet done so. This will happen in stages over the coming months. HMRC published guidance on 24 August 2026 explaining what taxpayers need to do if they receive confirmation that they have been signed up automatically.

Taxpayers who sign up themselves have the advantage of choosing their software, checking their details are correct from the start, and preparing in their own time. Waiting for HMRC to sign you up means you may have less control over the process and less time to prepare.

How can you prepare for the next quarterly update deadline?

The second quarterly update covers the period 6 April to 5 October 2026, with a deadline of 7 November 2026. To prepare, you should review your digital records monthly rather than leaving everything to the deadline. This gives you time to investigate unusual figures, confirm categorisations, and ensure your software is connected to the correct HMRC account.

If you have more than one income stream – for example, self-employment income and property income – you need to send a separate quarterly update for each self-employment and property business. If you are a landlord with rental properties, confirm that your property income and expenses are being recorded separately from any self-employment activity.

Checklist for the next deadline:

  • Confirm your software is still connected to HMRC and recognised for MTD for Income Tax
  • Review your records monthly for the cumulative period 6 April to 5 October 2026
  • Check income categorisation – separate self-employment from property income if you have both
  • Verify expense categories – ensure costs are allocated to the correct income source
  • Submit before 7 November 2026 to stay ahead of the deadline

How Apex Accountants Help with MTD for Income Tax

The client mentioned at the start of this article is not unusual. Many sole traders and landlords have submitted their first quarterly update but are unsure whether their records are accurate, whether their categorisations are correct, or whether they are fully prepared for the next deadline. That is the gap we fill.

Our approach to MTD for Income Tax is practical, not theoretical. We start by reviewing your current software setup and digital records to identify any errors, miscategorisations, or gaps before they compound across quarterly updates. For clients with multiple income streams – particularly those with both self-employment and property income – we ensure each source is tracked separately and correctly allocated.

Specifically, we help with:

  • Software selection and setup – we confirm your MTD-compatible software is correctly connected to HMRC and configured for your income sources
  • Digital record review – we check your categorisations, identify duplicated entries, and correct errors from previous quarters
  • Quarterly update preparation – we prepare and review each quarterly update before submission so your figures are accurate
  • Year-end tax planning – we handle the adjustments (capital allowances, private use apportionments, pension relief) that quarterly updates do not cover
  • Ongoing compliance – we track your deadlines, monitor threshold changes (including the move to qualifying income over £30,000 in April 2027), and keep you ahead of HMRC requirements

If you have submitted your first quarterly update and want to make sure your records are accurate before the next deadline, our Making Tax Digital services page explains exactly what we do. For broader support with digital record keeping and categorisation, our bookkeeping services are built around keeping your MTD submissions accurate throughout the year.

Frequently Asked Questions

Do I need an accountant for MTD quarterly updates?

You are not legally required to use an accountant for MTD, but many sole traders and landlords find professional support valuable – particularly if you have multiple income streams, property income, or complex expenses. An accountant can review your software setup, verify your categorisations, and ensure your quarterly figures are accurate so your year-end tax return is correct.

What happens if I get my quarterly update figures wrong?

If you discover an error after submitting a quarterly update, you can correct it in the next quarterly update. The figures are cumulative – each update builds on the previous one – so corrections made in a subsequent period will flow through to your annual return. However, it is better to get the figures right at source by reviewing your records regularly rather than relying on later corrections.

Will I be fined for submitting my first quarterly update late?

No. HMRC has confirmed that no penalty points will be issued for late quarterly updates during the 2026-27 tax year. This transitional arrangement means you will not face a points-based penalty for missing the 7 August deadline. However, you are still required to submit the update, and penalties for late Self Assessment returns and late tax payments still apply under the relevant rules.

How much does MTD-compatible software cost?

MTD-compatible software costs vary depending on the provider and the features you need. Some providers offer basic MTD-compliant packages for sole traders, while others charge more for features like automated bank feeds, receipt scanning, and multi-property tracking. HMRC publishes a list of compatible software on GOV.UK, which includes both free and paid options.

What if I have both self-employment and property income?

You need to send a separate quarterly update for each self-employment and property business. If you earn above the £50,000 threshold from combined self-employment and property income, you are in scope of MTD for Income Tax. The qualifying income calculation is based on gross income from these sources, not profit, so you need to check carefully whether you meet the threshold.

Does MTD apply if my income is below £50,000?

For the 2026-27 tax year, MTD for Income Tax applies to sole traders and landlords with qualifying income above £50,000. From April 2027, it will apply to those with qualifying income above £30,000. If your income is below the current threshold, you are not required to use MTD yet, but you may choose to sign up voluntarily to get ahead of the change.
HMRC’s 436,000 MTD Milestone: What Sole Traders and Landlords Should Do Before September

We are increasingly asked the same question by clients who have heard about Making Tax Digital but are not sure whether the deadline applies to them or what happens if they do nothing. The answer, as of August 2026, is straightforward: if you are a sole trader or landlord with qualifying income over £50,000 from self-employment or property shown on your 2024-25 tax return and you are not exempt, you are already legally required to use MTD for Income Tax – and from September, HMRC will start signing people up automatically if they have not done so themselves.

HMRC announced on 12 August 2026 that more than 436,000 sole traders and landlords have successfully submitted their first quarterly update under Making Tax Digital for Income Tax, with over 570,000 customers signed up to the service. That is a significant milestone, and HMRC has also confirmed that there are customers who need to use MTD but have not yet signed up – and HMRC is about to take matters into its own hands.

Key Takeaways

  • 436,000+ sole traders and landlords have submitted their first MTD quarterly update
  • 570,000+ customers have signed up to the MTD service
  • From September 2026, HMRC will begin automatic sign-ups in stages for eligible taxpayers who have not signed up themselves
  • Threshold for 2026-27: qualifying income over £50,000 from self-employment and property
  • From April 2027: threshold drops to over £30,000 – more taxpayers will be brought into scope
  • No penalty points for late quarterly updates during 2026-27, but late Self Assessment and late payment penalties still apply

What does the 436,000 figure actually mean?

The figure represents sole traders and landlords who successfully submitted their first quarterly update for 2026-27. HMRC published the figure in its 12 August announcement. The first quarterly update deadline was 7 August 2026. HMRC confirmed that the first quarterly update covered 6 April to 5 July 2026 for standard update periods. For calendar periods, it covered 1 April to 30 June 2026.

Separately, the 570,000 figure includes taxpayers who have registered for MTD. Some may not yet have submitted their first update. The gap between 436,000 submissions and 570,000 sign-ups suggests tens of thousands of people are registered but have not yet completed their first filing.

For more detail on the first reporting period and deadlines, see our guide to the first Making Tax Digital quarterly update deadline.

Who needs to sign up for MTD for Income Tax?

MTD for Income Tax applies to sole traders and landlords with qualifying income over £50,000 for the 2026-27 tax year. ‘Qualifying income’ means the gross income from self-employment and property – not profit. If you have multiple income sources, you need to add them together to check whether you exceed the threshold.

The threshold will change over the next year. It is over £50,000 for 2026-27 and drops to over £30,000 from April 2027. This means many more taxpayers will be brought into scope next year. If you are close to the current threshold, it is worth preparing now rather than waiting.

What happens when HMRC starts signing people up automatically in September?

From September 2026, HMRC will begin enrolling customers who need to use MTD for Income Tax. This applies to eligible taxpayers who have not yet signed up. This will happen in stages over the coming months.

HMRC published new guidance on 24 August 2026 explaining what taxpayers need to do after HMRC signs them up automatically.

The key difference between signing up yourself and being signed up by HMRC is control. If you sign up yourself, you choose your software, verify your details, and prepare on your own timeline. If HMRC signs you up, you may have less time to prepare and catch up on any outstanding requirements. For those who want to get their digital records right from the start, professional bookkeeping services can set up your software, categorise your income sources correctly, and ensure your first quarterly update is accurate.

What is a quarterly update and how is it different from a tax return?

A quarterly update is a short digital summary of your business income and expenses. You send it every three months through MTD-compatible software.It takes minutes to complete once your records are in order. It is not a tax return, and submitting an update does not create a tax payment. Your Self Assessment deadline of 31 January remains unchanged.

The quarterly updates feed into your annual tax return. When you come to file your Self Assessment, the income and expense information from your quarterly updates will feed into the year-end process. You then make any year-end adjustments (capital allowances, private use apportionments, pension relief) and submit the tax return.

Some taxpayers use calendar update periods instead. These are also cumulative: 1 April to 30 June, 1 April to 30 September, 1 April to 31 December, and 1 April to 31 March. The deadline for all customers is the same regardless of which period they use.

For a deeper look at how quarterly updates work alongside Self Assessment, read our earlier guide on the rules for MTD for Income Tax.

What are the penalties for not complying with MTD?

For the 2026-27 tax year, HMRC has confirmed that it will not issue penalty points for late quarterly updates. This is a transitional arrangement to help taxpayers adjust. However, penalties for late Self Assessment tax returns and late tax payments still apply – these are separate systems.

From 6 April 2027, a points-based penalty system will apply to missed quarterly deadlines: one point is given for each missed quarterly update deadline, and four points trigger a fixed £200 penalty. A further £200 penalty can apply for each additional missed submission while you remain at the penalty threshold.

If you are below the four-point threshold, individual penalty points normally expire 24 months after the missed deadline. Once you reach the threshold, the points do not simply expire after a period of compliance. To reset them, you generally need to meet your filing deadlines for 12 months. You must also submit outstanding quarterly updates and tax returns from the previous 24 months.

This means the 2026-27 tax year provides a grace period for quarterly update penalty points – but not for late tax returns or late tax payments. Use this year to get your systems right so you are not accumulating points from April 2027 onwards.

How do you choose the right MTD-compatible software?

Choose MTD-compatible software that HMRC recognises. It must also submit quarterly updates directly to HMRC’s systems.

When choosing software, consider:

  • Number of income sources – if you have both self-employment and property income, confirm the software supports multiple income streams
  • Bank feeds and automation – some packages connect directly to your bank to import transactions
  • Property-specific features – landlords with multiple properties may prefer software that allows individual properties to be tracked separately
  • Agent access – if you use an accountant, check whether the software allows your agent to access and review your records
  • Cost – basic packages may be sufficient for simple sole traders, while complex income structures may need more advanced features

Are there any exemptions from MTD for Income Tax?

Yes. HMRC provides various exemptions from MTD for Income Tax, including for taxpayers who are digitally excluded. Other exemptions may apply based on specific circumstances. If you believe you may be exempt, you should check HMRC’s exemption guidance and, if necessary, seek professional advice rather than assuming you are outside the scope of the rules.

The Apex Accountants View: Why Acting Before September Matters

We have been preparing clients for Making Tax Digital for Income Tax since the rules were first announced. We consistently see better results among clients who prepare early. Those who sign up themselves also have more time to organise their records before HMRC enrols them. The 436,000 figure shows that the system is working. However, there is still a substantial gap between the 436,000 submissions and 570,000 sign-ups. Thousands of people have registered but have not yet filed. HMRC has also confirmed that some eligible customers have not signed up.

Our recommendation is simple: if you think you are in scope, act now. Do not wait for HMRC to send you a letter in September. Signing up yourself gives you more control over the process. You can choose your software, organise your digital records, and check your categorisations before the next deadline. Waiting means you lose some of that preparation time.

Here is what we do for clients who come to us at this stage:

  • Eligibility assessment – we calculate your qualifying income across all sources to confirm whether you are in scope, including the over £50,000 threshold for 2026-27 and the over £30,000 threshold from April 2027
  • Software selection – we help you choose MTD-compatible software that fits your income structure, whether you are a sole trader, landlord, or both
  • Digital record setup – we configure your software with the correct income categories, expense types, and property tracking if applicable
  • First quarterly update support – we prepare and review your first quarterly update to ensure accuracy from the start, preventing compounding errors
  • Ongoing MTD compliance – we track your deadlines, monitor threshold changes, and keep you ahead of HMRC requirements throughout the year

If you have not yet signed up for MTD, or you are unsure whether the threshold applies to you, our Making Tax Digital services page explains what we do in detail. For clients who need help getting their digital records in order before signing up, our bookkeeping services cover everything from software setup to ongoing categorisation.

Frequently Asked Questions

Do I need an accountant to sign up for MTD?

You can sign up for MTD yourself through GOV.UK, without needing an accountant. However, professional support may help if you have multiple income streams or complex expenses. It can also save time if you are unsure whether you meet the qualifying income threshold. An accountant can also help you choose the right software and set up your digital records correctly from the start.

What happens if HMRC signs me up and I was not expecting it?

If HMRC signs you up automatically, you will receive communication explaining what you need to do. HMRC published guidance on 24 August 2026 for taxpayers who are signed up automatically. You will need to get MTD-compatible software, set up or update your digital records, and submit any outstanding quarterly updates. Acting before September gives you more time to prepare on your own terms.

Is qualifying income the same as profit?

No. HMRC calculates your qualifying income using your gross income from self-employment and property. This means your turnover before expenses. Profit is what remains after deducting allowable expenses. You could have a profit below £50,000 but still be in scope of MTD if your gross income exceeds the threshold. This is a common source of confusion, so check the calculation carefully.

What if my income fluctuates above and below £50,000?

HMRC uses your qualifying income from the relevant previous tax return to determine when you enter MTD. If your qualifying income exceeded £50,000 in 2024-25, you must use MTD for 2026-27. An exemption or another relevant rule may exclude you. Your circumstances may change after you start using MTD. If your qualifying income stays below the relevant threshold for three consecutive tax years, you may be able to opt out. You should check HMRC guidance rather than assuming that falling below the threshold for one year automatically takes you out of MTD.

Can I use MTD voluntarily if my income is below £50,000?

Yes. If you are eligible, you can sign up voluntarily for MTD for Income Tax even if your income is below the current mandatory threshold. Voluntary sign-up can help you get used to the system before MTD becomes mandatory for you. This may be useful if your income is close to £50,000. It may also help if the lower threshold from April 2027 is likely to bring you into scope.

How much does it cost to get help with MTD setup?

The cost of professional MTD support depends on your circumstances. Your income structure, number of income sources, and record complexity can all affect the price. A consultation with Apex Accountants will give you a clear assessment of what you need and a fixed quote based on your specific circumstances.

HMRC Late Payment Interest Rate: What 7.75% Costs You

Miss a tax deadline today, and HMRC charges 7.75% a year on the outstanding balance. The Bank of England’s base rate, by contrast, remains at 3.75% following its July 2026 meeting. The HMRC late payment interest rate is now more than double the central bank’s own rate, and for anyone who missed the 31 July second payment on account deadline, interest is already accruing.

How the HMRC Late Payment Interest Rate Is Calculated

HMRC’s rate isn’t set in isolation. It tracks the Bank of England base rate plus a fixed margin, and that margin changed materially from 6 April 2025, rising from base rate plus 2.5% to base rate plus 4%. With the base rate at 3.75%, the formula lands on 7.75%, applied from 9 January 2026 once the December base rate cut fed through.

The margin the other way is far less generous. Repayment interest, what HMRC pays when it owes you money, is the base rate minus 1%, floored at 0.5%, and is currently 2.75%. A taxpayer who owes HMRC pays 7.75%; a taxpayer HMRC owes receives 2.75%.

Worked Examples at the Current 7.75% Rate

HMRC calculates late-payment interest daily using simple interest. At the current rate, approximate costs are:

Unpaid TaxApprox. Average Monthly InterestInterest Over One Year
£1,000£6.46£77.50
£10,000£64.58£775
£50,000£322.92£3,875

The actual amount for an individual month varies with the number of days the tax remains unpaid. Interest starts from the relevant late-payment date and continues until the outstanding amount is paid.

Late Tax Payment Penalties UK Taxpayers Should Understand

For late tax payment penalties UK, taxpayers need to distinguish penalties from the separate interest charge, as both can increase the total cost of an overdue liability.

The most immediate exposure sits with Self Assessment taxpayers who missed the 31 July second payment on account for 2025/26. Interest starts accruing automatically from 1 August, charged daily using simple interest, until the balance clears:

  • A £800 payment left unpaid for a full year at 7.75% attracts roughly £62 in interest alone.
  • Payments on account attract interest only. The standard late-payment penalties apply to qualifying unpaid balancing payments.
  • A balancing payment left unpaid can attract interest and a penalty of 5% of the unpaid tax at 30 days, a further 5% at six months and another 5% at 12 months.

If the underlying debt relates to an individual’s tax position, our personal tax services team can help review the liability and deal with HMRC where necessary.

The rules on HMRC late payment interest for businesses apply across most taxes the department collects, including Corporation Tax and VAT, not just Self Assessment.

HMRC Late Payment Interest for Businesses: Why It Remains High

HMRC has long argued that its rates should discourage taxpayers from treating the department as cheap borrowing compared with commercial lending. The widened margin introduced in April 2025 pushed that further, and with the base rate holding at 3.75%, the 7.75% rate remains in force.

Corporation Tax late-payment interest is deductible when calculating a company’s taxable profits, which can soften the overall cost for companies. Interest on late-paid personal Income Tax and Capital Gains Tax is not deductible.

For companies concerned about missed deadlines or overdue liabilities, our Corporation Tax services can help manage filing and payment obligations before additional interest builds up.

Reducing Payments on Account Comes With Its Own Trap

Taxpayers expecting a lower bill can apply to reduce their payments on account via form SA303 or their online account. Cut them too aggressively, though, and any shortfall attracts interest backdated to the original January and July due dates, an easy way to turn a cash-flow fix into an unexpected bill months later.

How Apex Accountants Can Help

The HMRC late payment interest rate can quickly become expensive, especially on larger tax liabilities. Managing late tax payment penalties UK liabilities can also be difficult because penalties and interest are calculated separately and may apply at different stages.

Understanding HMRC late payment interest for businesses is particularly important where Corporation Tax or VAT liabilities are substantial, as interest continues to build until the outstanding tax is paid.

Apex Accountants & Tax Advisors can review your Self Assessment, Corporation Tax and VAT position, identify payments at risk of becoming overdue and help you approach HMRC before further charges arise.

We can also help negotiate a time-to-pay arrangement where appropriate and assess whether reducing your payments on account is genuinely justified before you submit an SA303.

Contact Apex Accountants today to arrange a free consultation and take control of your outstanding tax payments.

Frequently Asked Questions

What is HMRC’s current late payment interest rate?

7.75% a year, in effect since 9 January 2026. For most relevant taxes, it is calculated using the Bank of England base rate plus 4%.

Why is the rate so much higher than the base rate?

HMRC’s late-payment margin increased from base rate plus 2.5% to base rate plus 4% from 6 April 2025, widening the gap independently of any base-rate change.

Does HMRC pay the same rate on refunds?

No. Repayment interest is currently 2.75%, compared with the 7.75% late-payment rate.

Is interest the same as a penalty?

No. Interest compensates HMRC for receiving tax late and accrues while an amount remains unpaid. Penalties are separate charges that may apply depending on the tax and how long the liability remains outstanding.

Can I avoid the interest if I can’t pay on time?

A Time to Pay arrangement does not normally stop late-payment interest from accruing, but agreeing an arrangement promptly can help manage the debt and reduce the risk of further recovery action.

Is late payment interest tax deductible?

For Corporation Tax, late-payment interest is generally deductible when calculating company profits. Interest on late-paid personal Income Tax and Capital Gains Tax is not deductible.

How much interest does HMRC charge on a £10,000 late tax bill?

At the current 7.75% HMRC late payment interest rate, £10,000 left unpaid for a full year would attract approximately £775 in interest. The average monthly equivalent is around £64.58, although the actual charge depends on how many days the liability remains unpaid.

Can HMRC late payment interest be cancelled?

Late-payment interest is automatic and a reasonable excuse that may support an appeal against a penalty does not normally remove the interest itself. HMRC may consider giving up interest where its own mistake or unreasonable delay caused the interest to build up.

Complete Guide on First Making Tax Digital Quarterly Update Deadline 2026

We are increasingly hearing from sole traders and landlords who know that Making Tax Digital started in April but remain unsure what must be sent to HMRC in August. The first making tax digital quarterly update must be submitted by 7 August 2026 by individuals who entered MTD for income tax on 6 April 2026.

HMRC says more than 864,000 sole traders and landlords are within the first phase of the system. The update is not a completed tax return, and no tax payment is due solely because the quarterly submission has been made.

Quick Answer

  • The first quarterly update is due by 7 August 2026.
  • It normally covers records from 6 April to 5 July 2026.
  • Those using calendar quarters will report from 1 April to 30 June 2026.
  • The update contains cumulative income and expense category totals for each relevant business.
  • HMRC will not issue quarterly-update penalty points during 2026/27, but all four updates must still be submitted before the annual tax return can be filed.

What Is the First Making Tax Digital Quarterly Update?

The first Making Tax Digital quarterly update is a digital summary of income and expense records for the opening part of the 2026/27 tax year. It must be sent to HMRC through compatible software by 7 August 2026.

It is a summary rather than a tax return. Taxpayers do not normally need to make year-end accounting adjustments, capital allowance claims, or other tax adjustments before submitting it.

The software adds together the digital records entered for each income and expense category. HMRC receives category totals, not individual invoices, receipts, or bank transactions.

Who Must Submit an Update by 7 August 2026?

The deadline applies to sole traders and landlords who were required to begin using MTD for income tax on 6 April 2026. This generally means all the following conditions apply:

  • The individual is registered for self-assessment.
  • They receive income from self-employment, property, or both.
  • Their qualifying income was more than £50,000 in the 2024/25 tax year.
  • They do not have an automatic or HMRC-approved exemption.

HMRC should have written to taxpayers it identified as being within scope. However, not receiving a letter does not remove the responsibility to check qualifying income and sign up.

How Is Qualifying Income Calculated for MTD?

Qualifying income is the total gross income from self-employment and property before expenses are deducted. Income from several sole trades and property businesses is combined when testing the threshold.

The phased thresholds are

Income Shown on Tax ReturnQualifying IncomeMTD Start Date
2024/25More than £50,0006 April 2026
2025/26More than £30,0006 April 2027
2026/27More than £20,0006 April 2028

These are gross-income thresholds, not profit thresholds. A business can therefore be within MTD even where deductible expenses leave a comparatively small taxable profit.

Qualifying income does not normally include:

  • Employment income taxed through PAYE
  • Dividends, including dividends from the individual’s own company
  • State or private pension income
  • An individual partner’s share of partnership profits

A person’s share of income from a jointly owned property normally counts. For example, if a jointly owned property generates £50,000 of rent and two owners are entitled to equal shares, each person would generally have £25,000 of qualifying property income.

Worked Example

A sole trader reported £36,000 of gross trading income and £18,000 of gross rental income in 2024/25.

Their combined qualifying income is £54,000. They are therefore within the first MTD phase, even if business and property expenses reduce their total taxable profit below £50,000.

What Must Be Included in Quarterly Updates for Making Tax Digital?

The quarterly updates for making tax digital must include cumulative totals for the income and expense categories recorded in compatible software. A separate update is generally required for each self-employment and property business.

The submission may therefore contain totals for categories such as

  • Sales or business income
  • Rental income
  • Staff costs
  • Travel costs
  • Premises expenses
  • Professional fees
  • Repairs and maintenance
  • Other allowable business expenses

The categories broadly follow those used for self-assessment. The first update does not require every figure to be final or adjusted for tax purposes.

Even where a business has received no income and incurred no expenses during the period, an update must still be submitted to tell HMRC that there was no activity.

For jointly-let properties, HMRC allows taxpayers to include either income and expenses or income only during the quarterly cycle. Expenses omitted from the quarterly updates must be added after the tax year by resending the fourth update before submitting the annual tax return.

Which Period Does the First Update Cover?

The standard first update covers cumulative records from 6 April to 5 July 2026. Taxpayers using calendar update periods report records from 1 April to 30 June 2026 instead.

The deadline is 7 August 2026 under either method.

Reporting MethodFirst Update PeriodSubmission Deadline
Standard tax-year periods6 April to 5 July 20267 August 2026
Calendar periods1 April to 30 June 20267 August 2026

Calendar periods may be more practical where accounts are prepared to 31 March. They must be selected in the software for each income source before the first update is submitted.

Once the first update has been sent, the reporting-period method cannot be changed for that tax year.

Which Making Tax Digital Submission Dates Follow the First Deadline?

The four Making Tax Digital submission dates for the 2026/27 tax year are 7 August 2026, 7 November 2026, 7 February 2027 and 7 May 2027.

Each update is cumulative. This means the second standard update covers 6 April to 5 October, rather than covering only the three months from July to October.

UpdateStandard Cumulative PeriodCalendar Cumulative PeriodDeadline
First6 April to 5 July 20261 April to 30 June 20267 August 2026
Second6 April to 5 October 20261 April to 30 September 20267 November 2026
Third6 April 2026 to 5 January 20271 April to 31 December 20267 February 2027
Fourth6 April 2026 to 5 April 20271 April 2026 to 31 March 20277 May 2027

The 2025/26 self-assessment return must still be submitted through the usual process by 31 January 2027. The first annual return completed through the MTD system, covering 2026/27, will be due by 31 January 2028.

Can Mistakes Be Corrected After an Update Is Sent?

Mistakes can normally be corrected in the digital records and reflected in the next cumulative quarterly update. Taxpayers do not generally need to reopen and resubmit every earlier update.

For example, if an invoice dated in May is entered incorrectly and corrected in September, the cumulative update sent in November should contain the corrected year-to-date figures.

This cumulative method is an important distinction. Some explanations describe each submission as a completely separate three-month return, but HMRC’s guidance confirms that each update runs from the beginning of the tax year or calendar reporting year to the end of the relevant period.

What Happens If the Making Tax Digital First Quarter Deadline Is Missed?

HMRC will not apply quarterly-update penalty points for late submissions during the 2026/27 tax year. However, the updates remain legally required and must all be submitted before the annual MTD tax return can be completed.

The first-year concession does not protect taxpayers from:

  • Penalties for a late annual tax return
  • Late-payment penalties
  • Interest on tax paid after the payment deadline
  • Administrative problems caused by incomplete digital records

From the tax years after 2026/27, missing a quarterly deadline will normally result in one penalty point. The threshold is four points, at which stage a £200 penalty is charged. A further £200 penalty can apply for each later missed deadline while the taxpayer remains at the threshold.

Only one point can be issued for a particular deadline, even where a person has several businesses and submits several quarterly updates late. MTD for Income Tax penalty points are also separate from any penalty points arising under MTD for VAT.

What Should You Do Before Submitting the First Update?

Taxpayers should check their registration, software connection and digital records before pressing submit. The update should be generated from records created since the start of the applicable reporting period.

A practical review should include:

  1. Confirm that you are within MTD. Recheck the gross self-employment and property income shown on the 2024/25 return.
  2. Complete the MTD sign-up process. Being registered for self-assessment does not, by itself, complete MTD registration.
  3. Authorise compatible software. HMRC provides a software finder for MTD for Income Tax.
  4. Check every relevant income source. A separate update may be required for each trade and property business.
  5. Update digital records. Record income and expenses from 6 April, or from 1 April when using calendar periods.
  6. Review the cumulative totals. Look for duplicate bank transactions, omitted invoices, personal costs and incorrect category allocations.
  7. Retain submission confirmation. Keep evidence showing when the update was accepted by HMRC.

Taxpayers can continue to use spreadsheets, provided suitable bridging software creates the required digital connection and submits the information to HMRC. A spreadsheet on its own cannot send an MTD update.

Further guidance is available in Apex Accountants’ article on the £50,000 MTD rule for sole traders and landlords.

Who Can Be Exempt From the First Quarterly Deadline?

Some individuals and entities are automatically exempt, while others must apply to HMRC. An exemption from MTD changes the reporting method but does not normally remove the requirement to report taxable income through self-assessment.

Automatic exemptions include certain trusts, personal representatives, non-resident companies filing an SA700 and individuals without a National Insurance number before the start of the relevant tax year. Partnerships are not currently required to use MTD for income tax, although the government intends to set out their timetable separately.

A person may apply for digital-exclusion exemption where it is not reasonable for them to use software because of factors such as:

  • Age, disability or a health condition
  • Religious beliefs incompatible with digital record-keeping
  • Lack of internet access because of location, with no suitable alternative available

HMRC considers applications individually. Cost, limited experience with software or having only a small number of transactions is not normally enough on its own. A more detailed explanation is available in Apex Accountants’ guide to MTD exemptions.

FAQs About MTD Quarterly Update Deadline

Is Any Tax Payable on 7 August 2026?

No tax payment becomes due simply because the first quarterly update is submitted. The update provides income and expense totals that can generate an estimated tax position, but the normal annual tax-payment deadlines continue to apply.

Can an Accountant Submit the Quarterly Update?

Yes. An authorised accountant or tax agent can sign a client up, manage digital records and submit quarterly updates through compatible software. The taxpayer remains responsible for providing complete and accurate information to the agent.

Do I Need to Submit an Update When There Was No Income?

Yes. HMRC requires a quarterly update even where no income was received and no expenses were incurred during the latest period. The software should submit a nil or no-activity update for the relevant business.

Can I File the Update Through My Personal Tax Account?

No. Quarterly updates must be submitted through software that works with MTD for Income Tax. HMRC does not provide a form within the ordinary online Self Assessment service for manually entering the quarterly figures.

Do Quarterly Updates Replace the Annual Tax Return?

No. Four quarterly updates must be followed by an annual tax return submitted through compatible software. The annual return includes other income, reliefs, claims and final adjustments that may not have appeared in the quarterly summaries.

How Much Does Accountant Support for MTD Cost?

The cost depends on the number of businesses, transaction volume, quality of existing records, software requirements and whether bookkeeping is included. A straightforward sole trade with organised digital records will generally require less work than a taxpayer with several trades and rental properties.

How Can Apex Accountants Help With the First MTD Update?

Where records are incomplete, software has not been connected or several income sources must be reported, the sensible next step is to resolve the position before the figures build into the next cumulative period.

Apex Accountants can check eligibility, arrange software, review digital records and manage quarterly submissions through its Making Tax Digital accountant service. To discuss the 7 August deadline, book a consultation with the team.

HMRC Landlord Tax Crackdown Recovers £100m in Unpaid Tax

A landlord can report rental income for several years and still discover that the figures do not match the rent paid into their bank account. The difference may result from an incorrectly divided jointly owned property, restricted mortgage interest relief, or income from a short-term letting platform.

That is why the landlord tax crackdown matters. HMRC can obtain information from letting agents and digital platforms, compare it with tax returns, and ask landlords to explain inconsistencies. Reviewing the position before HMRC makes contact usually gives the landlord more control over how to correct an error.

Quick Answer

  • There is no new tax called a landlord crackdown. The article describes HMRC’s continuing work to identify undeclared or incorrectly reported property income.
  • Landlords paid £104m in unpaid taxes in 2025/26.
  • HMRC can obtain bulk information about rent paid by letting agents and receive seller and property information from qualifying digital platforms.
  • Individual residential landlords can use the Let Property Campaign to disclose earlier undeclared rental income.
  • Once HMRC acknowledges a Let Property campaign notification, the landlord normally has 90 days to submit the disclosure and pay or arrange payment.
  • Depending on the behaviour involved, HMRC may examine records for up to 4, 6 or 20 years.

What Does the Landlord Tax Crackdown Mean in 2026?

The landlord tax crackdown is not a new tax or a single temporary investigation. It is a broad description of HMRC’s ongoing use of data, compliance letters, voluntary disclosure arrangements and formal enquiries to collect tax that should already have been paid.

Landlords have paid £100m in HMRC’s tax crackdown, which is evidence of compliance activity. The reported £104m figure is the tax recovered through landlord disclosures during 2025/26. 

The legal obligations themselves are clear. Individuals must report taxable rental income correctly, retain supporting records and correct earlier failures where necessary. HMRC has also confirmed to Parliament that it uses several data sources to identify property-sector non-compliance and may open formal compliance interventions where landlords do not come forward.

Why Does HMRC Target UK Landlords With Undeclared Rent?

HMRC targets UK landlords because it can check rental income against information held by third parties. A landlord’s tax return is no longer the only source showing that a property has been let or how much rent may have been collected.

Under Schedule 23 of the Finance Act 2011, HMRC has data-gathering powers that can be used to obtain information from relevant data holders. HMRC’s own compliance manual specifically gives rental payments made by letting agents to landlords as an example of bulk third-party information that can be collected.

Digital platform reporting has added another source of information. Qualifying UK platform operators must collect and report information about reportable sellers, including people who rent out immovable property. For property rentals, the information can include the seller’s identity, income and the address of each property offered through the platform.

HMRC can therefore compare information from sources such as:

  • Self-assessment returns
  • Letting agents and property managers
  • Short-term rental and accommodation platforms
  • Previous correspondence and disclosures
  • Information exchanged with overseas tax authorities
  • Records requested during a compliance check

Receiving a letter does not automatically mean HMRC has proved that tax is owed. It normally means the information available to HMRC does not appear to match the return, registration position or other records.

Which Landlords Should Review Their Tax Position?

Any landlord whose gross property income exceeded the relevant reporting limits should check that the income was reported in the correct tax year and by the correct owner.

The property allowance can exempt up to £1,000 of gross property income for qualifying individuals. Where annual gross property income exceeds £1,000, further reporting action is generally required. 

A landlord should contact HMRC when gross rental income is between £1,000 and £2,500 and may need to register for Self Assessment when it exceeds £2,500. Separate self-assessment reporting limits may also apply where gross receipts exceed £10,000 or profit after expenses exceeds £2,500.

Landlords at greater risk of an incorrect return include those who

  • Let a property for the first time without registering for self-assessment
  • Became an accidental landlord after moving home or inheriting a property
  • Received rent through Airbnb or another short-term letting platform
  • Own property jointly but report all income under one owner
  • Claimed mortgage interest as a full deduction rather than a tax reduction
  • Deducted improvements as though they were routine repairs
  • Own UK property while living abroad
  • Have overseas rental income
  • Continued using former furnished holiday letting rules after their abolition
  • Sold a rental property without checking Capital gains tax reporting

The Let Property Campaign covers individual landlords renting residential property in the UK or abroad. It can also cover a single property, several properties, holiday accommodation, inherited property and income above the Rent a Room Scheme limit.

It does not cover disclosures made by companies or trusts, nor does it cover landlords letting only non-residential property, such as shops, garages or lock-ups. Those taxpayers may need to use another disclosure route.

What Rental Tax Errors Does HMRC Commonly Look For?

HMRC is likely to examine whether the landlord reported all rent and applied the property tax rules correctly. An error can arise even where the landlord did not intend to conceal income.

Area CheckedCorrect General TreatmentCommon Risk
Gross rentReport rent and other property receipts belonging to the taxpayer.Reporting only the amount left after an agent deducts fees
Joint ownershipReport the share belonging to each beneficial owner.Putting all rent on the lower earner’s return without supporting ownership
Mortgage interestIndividual residential landlords normally receive a basic-rate tax reduction.Deducting all mortgage interest from rental income
RepairsRevenue repairs may normally be deducted.Treating an improvement or extension as a repair
Property allowanceClaim the allowance or actual expenses where permitted.Claiming both against the same property income
Short-term letsReport taxable receipts from digital platforms.Assuming occasional or platform income is automatically tax-free
Overseas propertyUK residents may need to report foreign property incomeReporting UK rent but omitting an overseas property
Property saleCheck capital gains tax and the UK property reporting deadline.Assuming the annual self-assessment return is the only report required

For married couples and civil partners living together, income from jointly owned property is normally taxed equally. A different division generally requires the income split to follow the couple’s actual beneficial ownership and a valid Form 17 declaration where applicable. Simply paying rent into one person’s account does not, by itself, transfer the taxable income.

Individual residential landlords cannot normally deduct finance costs directly when calculating property profit. Instead, they may receive a tax reduction calculated at the basic rate, subject to the statutory limits.

Worked Example of the Mortgage Interest Error

Assume an individual landlord receives:

  • Rent: £18,000
  • Allowable non-finance expenses: £4,000
  • Mortgage interest: £7,000

The property profit before the finance cost tax reduction is £14,000, not £7,000.

Subject to the landlord having enough property profit, adjusted total income and income tax liability, the £7,000 finance cost may produce a tax reduction of up to £1,400, calculated at 20%. A landlord who deducts the full £7,000 when preparing the rental profit may materially understate taxable income.

Repairs also require care. HMRC distinguishes expenditure that restores an existing asset from expenditure that improves or changes it. Routine repairs may be deductible, while capital improvements are generally not deducted from rental income.

How Can Landlords Make a Voluntary Tax Disclosure?

An individual residential landlord can normally use HMRC’s Let Property Campaign to disclose undeclared rental income before the tax authority starts a formal investigation.

Voluntary tax disclosures by landlords involve two main stages:

  1. The landlord must notify HMRC that they will make a disclosure.
  2. Calculate, disclose and pay the tax, interest and penalties due.

The initial notification does not require the landlord to provide the complete calculation. HMRC issues a disclosure reference and payment reference after receiving it.

The full disclosure must then normally be submitted within 90 days of the date HMRC acknowledges the notification. The landlord must pay the amount due by that deadline or agree payment arrangements with HMRC before submitting the disclosure.

The calculation should normally consider:

  • Gross rental income for each affected tax year
  • The landlord’s legal or beneficial share
  • Allowable running expenses
  • Residential finance cost tax reductions
  • Other undeclared income that must be included
  • Income Tax or Capital Gains Tax due
  • Late payment interest
  • The appropriate penalty
  • Payments already made

Joint owners cannot make one combined disclosure. HMRC requires each taxpayer to notify and disclose their own share separately.

A disclosure that is incomplete or materially inaccurate may not be accepted. HMRC may reopen the position if later information shows that important income or liabilities were omitted.

How Far Back Can HMRC Investigate a Landlord?

HMRC may look back for 4, 6 or 20 years, depending on whether the landlord took reasonable care, acted carelessly, failed to notify the tax authority or deliberately withheld information.

Tax BehaviourMaximum Period Commonly Covered
Reasonable care taken, but too little tax paid4 years
Careless error6 years
Failure to notify HMRC of a liabilityUp to 20 years
Deliberate understatement or omissionUp to 20 years
Certain offshore mattersSeparate extended rules may apply.

HMRC states that most Let Property Campaign disclosures are expected to cover no more than six years. A longer period can apply where the landlord failed to register or deliberately omitted income.

The applicable period should not be selected simply because it produces the lowest bill. It depends on what happened, what the landlord knew and what steps were taken to check the return.

For example, a landlord who registered for self-assessment and relied on incomplete agent statements may have a different position from someone who received rent for ten years and never told HMRC that the property existed.

What Penalties Can Apply to Undeclared Rental Income?

A landlord may have to pay the unpaid tax, late payment interest and a penalty based on the potential tax lost. The percentage depends on whether the error was careless or deliberate, whether it was concealed and whether the disclosure was prompted by HMRC.

Indicative onshore inaccuracy penalty ranges include:

BehaviourGeneral Penalty Range
Careless inaccuracy0% to 30% of potential lost revenue
Deliberate inaccuracy20% to 70%
Deliberate and concealed inaccuracy30% to 100%

Where there has been a non-deliberate failure to notify and HMRC prompts the disclosure more than 12 months after the tax became due, HMRC’s published example gives a penalty range of 20% to 30% of potential lost revenue. Different ranges can apply according to the precise failure, timing and whether offshore income is involved.

Coming forward voluntarily does not cancel the underlying tax or interest. It can, however, affect whether HMRC treats the disclosure as prompted or unprompted, and it can also affect the reduction available for the quality of the disclosure.

The quality assessment considers how fully the taxpayer has:

  • Tells HMRC what went wrong
  • Helps HMRC establish the correct position
  • Gives HMRC access to relevant records

A landlord should not guess the penalty percentage. The calculation should match the tax behaviour, disclosure route and affected years.

Does Making Tax Digital Increase HMRC’s Oversight of Landlords?

Making Tax Digital gives HMRC more frequent information about in-scope property businesses, although quarterly updates are not the same as full tax investigations.

From 6 April 2026, landlords and sole traders must use Making Tax Digital for Income Tax when their combined qualifying gross income from property and self-employment exceeds £50,000 in 2024/25.

The rollout continues as follows:

Start DateRelevant Qualifying Income
6 April 2026More than £50,000 in 2024/25
6 April 2027More than £30,000 in 2025/26
6 April 2028More than £20,000 in 2026/27

Those in scope must keep digital records and use compatible software to submit quarterly updates. They must still complete the year-end tax return process and pay tax by the applicable self-assessment deadline.

MTD does not automatically correct historical rental income errors. A landlord who has already omitted earlier income may need a separate disclosure even after entering MTD.

Our guide on MTD for Income Tax for landlords and sole traders explains the reporting process in more detail. 

What Should a Landlord Do After Receiving an HMRC Letter?

A landlord should first identify exactly what HMRC is asking and avoid sending an estimated or incomplete response.

The following steps can help:

  1. Check the deadline. HMRC letters normally specify when a response is required.
  2. Identify the tax years involved. Do not assume the enquiry concerns only the latest return.
  3. Reconcile gross rent. Compare bank statements, letting-agent records, tenancy agreements and platform statements.
  4. Check ownership. Establish who was legally and beneficially entitled to the income.
  5. Review every expense. Separate allowable running expenses, finance costs and capital expenditure.
  6. Check other liabilities. Consider overseas rent, capital gains tax and other undeclared income.
  7. Do not use the wrong disclosure route. The Let Property Campaign is not available for every taxpayer or property type.
  8. Obtain professional advice before making statements about behaviour. Describing an error as careless or deliberate can affect the years and penalties involved.

Landlords should retain their rental records for at least five years after the 31 January filing deadline for the relevant tax year. HMRC may charge penalties where records are incomplete, inaccurate or not retained for the required period.

Professional HMRC tax investigation support can be particularly useful where HMRC has already identified discrepancies or requested several years of records.

FAQs About Landlord Tax Crackdown

Does HMRC Know That I Own a Rental Property?

HMRC may receive information indicating that a person rents out property even where no rental income appears on their tax return. Its statutory data-gathering powers cover information held by relevant third parties, and qualifying digital platforms report seller and property information.

Ownership alone does not prove that taxable income arose, but the landlord may need records showing whether the property was occupied, empty, used privately or let.

Can I Use the Let Property Campaign After HMRC Contacts Me?

You should obtain advice before assuming that the Let Property campaign remains available. If HMRC has identified the issue, it may treat any disclosure made after that as prompted, which can affect the penalty position.

HMRC may also direct the landlord to respond through the existing compliance check rather than submit a separate voluntary disclosure.

Do I Need to Declare Rent When the Property Makes a Cash Loss?

Possibly. Taxable property profit is not necessarily the same as the cash left after paying the mortgage.

Individual residential landlords normally cannot deduct mortgage interest directly from rental profit. They receive a basic-rate tax reduction instead, so a property can produce little cash while still generating taxable profit.

Can Joint Landlords Submit One Disclosure?

No. Each joint owner must normally submit a separate notification and disclosure covering their own share of rental income, expenses and tax.

The income split should reflect the applicable ownership and tax rules. Married couples and civil partners should also check whether the standard equal division or a valid Form 17 treatment applies.

Will a Voluntary Disclosure Prevent an HMRC Investigation?

HMRC may accept a complete and accurate disclosure without opening a wider investigation, but acceptance is not automatic. It can check the calculations, request supporting records and reopen the position if later information shows that the disclosure was incomplete.

A properly prepared disclosure should cover all relevant years, liabilities, interest and penalties.

Do I Need an Accountant for a Let Property Campaign Disclosure?

There is no legal requirement to appoint an accountant, but professional advice can be valuable where several years, joint ownership, mortgage interest, overseas property or missing records are involved.

An adviser can reconstruct the rental accounts, calculate the correct tax and penalty, prepare the disclosure and correspond with HMRC under the appropriate authority.

How Can Apex Accountants Help With a Landlord Tax Disclosure?

The next step is to establish the correct rental income before responding to HMRC or submitting a disclosure.

Apex Accountants can review rental records, reconstruct missing accounts, check allowable expenses, calculate finance cost relief and prepare voluntary disclosures. Where HMRC has already written to you, our HMRC investigation specialists can review the letter and manage the response.

Landlords who need broader return and property income support can book a consultation to discuss the landlord tax crackdown and their individual position.

Changes to Lower Value Tax Debts: HMRC Bank Deduction Plans

A business can fall behind with a relatively modest VAT or PAYE liability after one difficult trading quarter. Because the amount is not substantial enough to trigger immediate court action, some directors assume HMRC will give it less attention.

That assumption may become increasingly dangerous. The government is consulting on a new automated process for recovering lower value tax debts through monthly deductions from UK bank and building society accounts.

The proposals are not yet law. However, they show that HMRC wants a practical enforcement tool for taxpayers who can make payments but repeatedly ignore collection letters, calls and other contact attempts.

Quick Answer

  • The proposals are currently at the consultation stage and are not confirmed law.
  • HMRC does not presently expect the measure to cover total debts above £5,000 for individuals or £10,000 for companies, although the final limits remain undecided.
  • It would apply only after HMRC’s standard collection process had been exhausted and the taxpayer had persistently failed to engage.
  • HMRC is considering a 14-day Pre-Deduction Notice before the first monthly deduction.
  • Taxpayers could object because of an HMRC error, financial hardship, additional support needs or third-party ownership of funds.

What Are Lower Value Tax Debts Under HMRC’s Proposal?

Lower value tax debts would be established HMRC liabilities that fall within proposed upper limits and remain unpaid after repeated collection attempts. The indicative limits are £5,000 for individuals and £10,000 for companies, including accrued penalties and interest at the point HMRC considers taking action.

These figures are not final thresholds. The consultation states that the upper limits have not yet been decided and seeks views on what would be proportionate.

HMRC would consider a taxpayer’s total debt across different tax regimes rather than examining each liability separately. The measure could therefore cover a combination of:

  • Self Assessment Income Tax
  • VAT
  • PAYE and National Insurance
  • Corporation Tax
  • Stamp taxes
  • Tax penalties
  • Accrued interest

For example, a company owing £2,000 in VAT and £1,500 in PAYE would have a combined tax debt of £3,500 for the proposed eligibility test. Splitting liabilities across different taxes would not prevent them from being considered together.

Read: Employing Family Members in a UK Business: Why HMRC Is Asking Tougher Payroll Questions

Why Is HMRC Targeting Smaller Tax Debts?

HMRC is targeting smaller tax debts because many remain unresolved after letters, calls and referrals to debt collection agencies. Traditional enforcement methods can also cost too much to use efficiently against modest liabilities.

Official analysis indicates that approximately 4.8 million individuals and companies hold debts within the indicative limits. These represent around 11.5 million separate debts, with a combined value of about £4 billion.

Each year, more than 750,000 lower-value debts worth over £2 billion are returned to HMRC after debt collection agencies have been unable to secure payment. HMRC believes the absence of a scalable enforcement process may encourage some taxpayers to assume that smaller liabilities will not be pursued.

HMRC already resolves more than 95% of tax debt by value each year. Its concern is the remaining population of older debts where the taxpayer has repeatedly declined to communicate.

How Would HMRC Tackle Lower Value Tax Debts?

HMRC would tackle lower value tax debts by instructing a bank or other deposit-taking institution to make fixed monthly deductions from a taxpayer’s account. The proposed process would begin only after normal collection activity and opportunities to agree a voluntary payment plan had failed.

The likely process would be:

  1. A tax liability becomes final and remains unpaid.
  2. HMRC sends reminders and attempts to contact the taxpayer.
  3. The case may be referred to a debt collection agency.
  4. HMRC confirms that standard collection routes have been exhausted.
  5. HMRC issues a formal Pre-Deduction Notice.
  6. The taxpayer receives a final opportunity to pay, arrange Time to Pay or object.
  7. If no action is taken, HMRC instructs the bank to begin monthly deductions.

The Pre-Deduction Notice would state the debt amount, penalties and interest, proposed monthly payment, deduction date and planned payment period. HMRC is considering allowing 14 days between issuing the notice and making the first deduction.

The 14-day period is only a consultation proposal. It is not yet a statutory deadline.

Which Debts and Taxpayers Would Be Within Scope?

The proposed power would cover individuals and companies with final, legally enforceable HMRC debts who have persistently failed to engage. It would not be a first response to a recently missed payment.

The following cases would be expected to fall outside the proposed process:

  • Debts subject to an active appeal
  • Liabilities under an ongoing enquiry or compliance review
  • Recent debts still within HMRC’s standard collection cycle
  • Debts covered by an agreed Time to Pay arrangement
  • Cases already subject to another enforcement arrangement
  • Taxpayers without an identifiable UK bank or building society account
  • Overseas bank accounts

A disputed liability should not qualify merely because HMRC has issued an assessment. The amount would need to be final and legally enforceable, with the normal appeal process completed or expired.

This distinction matters. A taxpayer who disagrees with an assessment must challenge the underlying liability through the correct appeal route. Ignoring collection correspondence is not an effective way to preserve appeal rights.

What Safeguards Would Apply Before Bank Deductions?

HMRC proposes safeguards covering notice, affordability, additional support needs, objections, independent review and possible tribunal oversight. Automation would be paused where the available information suggests that human judgement is required.

The proposed safeguards include:

  • More than 10 attempts to contact the taxpayer before using the power
  • A formal notice before deductions begin
  • Opportunities to disclose financial hardship or support needs
  • Manual review by trained HMRC staff
  • The right to object before or during the payment schedule
  • An independent HMRC review of an objection
  • A possible external appeal to a tribunal or court
  • Refunds and compensation for charges caused by HMRC errors

HMRC proposes allowing objections where:

  • HMRC has made a factual or procedural error
  • The deductions would cause financial hardship
  • The taxpayer requires additional support
  • Funds in the account belong to another person
  • A joint account holder has a beneficial interest in the money

An objection would pause deductions while HMRC reviewed the case. The proposed appeal route has not been finalised, although HMRC is considering a timeframe similar to the usual 30-day tax appeal deadline.

A complaint would be different from an objection. Complaining about HMRC’s service would not automatically stop deductions, although HMRC could intervene where its investigation identified an error or serious procedural failure.

Also Read: HMRC Automatic Bank Deductions: What Beneficiaries Must Know Now

How Would HMRC Decide Whether Monthly Deductions Are Affordable?

HMRC is considering using tax records, business information and credit reference data to estimate affordable monthly payments. The final methodology has not been decided and forms a significant part of the consultation.

For individuals, HMRC might consider PAYE information, Self Assessment returns and other income records. For businesses, it could consider VAT turnover figures or recently filed accounts.

The consultation also considers applying HMRC’s existing Time to Pay affordability principle. This generally means that debt repayments should not exceed 50% of the taxpayer’s disposable income.

However, an automated assessment may not reflect current circumstances. Historical profits, turnover or PAYE data may give an inaccurate picture after redundancy, illness, loss of a customer or a sudden decline in trading.

Taxpayers would therefore need to contact HMRC promptly where the suggested payment creates hardship. Financial difficulty would not automatically exclude someone from the process if they continued to ignore HMRC.

Under the current proposal:

  • There would be no standard payment-plan length.
  • Payment periods could vary according to debt and affordability.
  • Penalties associated with the debt would stop accruing once deductions began.
  • Interest could continue until the balance was cleared.
  • HMRC is not currently proposing a fixed minimum balance that must remain in the account.

These details remain subject to consultation and could change before legislation is drafted.

How Is the Proposal Different From Existing Direct Recovery of Debts?

The proposed system would collect smaller liabilities through recurring instalments, while existing Direct Recovery of Debts normally involves holding and removing a lump sum. Existing DRD also has different thresholds and safeguards.

Under current DRD rules, HMRC can use bank information to recover established debts of more than £1,000. It must leave at least £5,000 available across the taxpayer’s accounts after placing the hold.

Existing DRD is largely manual. It involves obtaining bank information, placing money on hold and allowing the taxpayer 30 calendar days to object before funds are transferred.

The proposed lower-value system would instead:

  • Operate through regular monthly deductions
  • Be designed for high-volume use
  • Use automated eligibility and affordability checks
  • Potentially have a 14-day initial notice period
  • Apply without the existing £5,000 protected account balance, provided the instalments pass affordability checks

HMRC restarted existing DRD through a controlled test phase in September 2025 and began a wider rollout from April 2026. The new monthly instalment proposal is separate and would require legislation before HMRC could use it.

What Should You Do If You Owe Smaller Tax Debts Now?

You should contact HMRC as soon as you know that a tax payment cannot be made in full. Early engagement provides more options than waiting for the debt to move into enforcement.

HMRC may agree to a Time to Pay arrangement where the proposed payments are realistic and affordable. Taxpayers setting up a plan should prepare details of their income, regular spending, assets, savings and other tax liabilities.

Companies may also be asked how they can reduce the debt by releasing assets, obtaining finance or introducing funds. HMRC will expect a company’s proposal to address both the overdue balance and its ability to meet future tax payments.

As at 16 July 2026, the main HMRC late-payment interest rate is 7.75%, applying from 9 January 2026. The rate is linked to the Bank of England base rate and can change, so it should be checked again before publication.

Ignoring the debt can lead to:

  • Referral to a debt collection agency
  • Recovery through PAYE or pension income
  • Taking Control of Goods
  • Direct recovery from bank accounts
  • Court proceedings
  • Bankruptcy or company winding-up action in serious cases

HMRC should provide notice before taking enforcement action, but continued non-engagement substantially reduces the opportunity to agree a voluntary solution.

Where an HMRC letter appears incorrect, retain the correspondence and supporting records. Consider obtaining advice before making admissions or agreeing to a payment schedule. 

FAQs About Lower Value Tax Debts

Can HMRC Take Money From My Bank Account Now?

Yes, HMRC already has Direct Recovery of Debts powers in limited circumstances. Existing DRD normally applies where more than £1,000 is owed and at least £5,000 would remain available across the taxpayer’s accounts. The proposed automated monthly deductions for lower-value debts are separate and are not yet law.

Could HMRC Use a Joint Bank Account?

Under the proposal, HMRC would consider a joint account only where no suitable sole account existed or a sole account held insufficient funds. A non-debtor joint account holder would be able to object where the money belonged to them. The final joint-account rules have not yet been legislated.

Would a Time to Pay Agreement Prevent Automatic Deductions?

An active and agreed Time to Pay arrangement would be outside the proposed automated deduction process. Taxpayers must maintain the agreed payments and keep up with new tax liabilities. A failed arrangement could lead HMRC to reconsider enforcement options.

Would Interest Stop Once Monthly Deductions Begin?

The consultation proposes stopping further penalties associated with the debt when instalment deductions begin. It does not propose stopping late-payment interest, which may continue until the balance is cleared. The precise interest treatment should be confirmed in any final legislation.

Can I Object Because I Cannot Afford the Proposed Payment?

Yes. Financial hardship is one of the proposed grounds for objection, and an objection would pause deductions while HMRC reviewed the case. You should provide current evidence of income, essential expenditure, cash flow and other debts rather than relying on a general statement that the payment is unaffordable.

Do I Need an Accountant to Deal With an HMRC Tax Debt?

An accountant is not legally required, but professional support can help verify the liability, correct returns, prepare affordability evidence and negotiate a realistic payment proposal. Advice is particularly valuable where the debt covers several taxes, the amount is disputed or HMRC is considering enforcement action.

How Can Apex Accountants Help With HMRC Tax Debt?

Apex Accountants can review how the liability arose, reconcile HMRC’s figures, identify errors and prepare a practical proposal for payment. Where the matter involves disputed assessments or formal enforcement, our HMRC tax investigation services can support communication and representation.

The sensible next step is to address the debt before HMRC exhausts its standard collection process. Book a consultation to discuss the liability, available payment options and any urgent HMRC correspondence.

Changes to Capital Goods Scheme for VAT: What UK Businesses Need to Know

A client came to APEX last year partway through refurbishing a mixed-use building — offices upstairs, a partly exempt letting downstairs. The spend sat just above the old £250,000 capital goods scheme threshold, which meant ten years of annual VAT adjustments to track and defend. Under the rules that now apply, that same refurbishment would fall outside the scheme entirely. From 29 July 2026, HMRC will raise the Capital Goods Scheme threshold for land, buildings and civil engineering work from £250,000 to £600,000 and will remove computers from the scheme altogether. This is the biggest change to CGS since it was introduced in 1990, and it will pull thousands of smaller property transactions out of a notoriously complex compliance regime.

Quick answer:

  • The Capital Goods Scheme (CGS) threshold for land, buildings and civil engineering works rises from £250,000 to £600,000 (excluding VAT) from 29 July 2026.
  • Computers and computer equipment are removed from the CGS entirely from the same date — the old £50,000 threshold no longer applies to them.
  • The change only affects capital expenditure incurred on or after 29 July 2026; anything already committed under contract before that date follows the old rules.
  • It’s made via secondary legislation amending regulations 113 and 114 of the VAT Regulations 1995 (SI 1995/2518) — this is a confirmed HMRC measure, not a consultation proposal.
  • HMRC estimates the change will save affected businesses roughly £0.6 million a year in administrative costs, with negligible Exchequer impact.

What is the Capital Goods Scheme for VAT?

The Capital Goods Scheme for VAT is an adjustment mechanism that spreads the recovery of input tax on certain high-value assets over several years, rather than allowing a single claim at the point of purchase. It exists to stop businesses over- or under-claiming VAT when the taxable use of an asset changes after acquisition.

Under current law, two categories of asset fall within CGS:

  • Land, buildings and civil engineering works, where capital expenditure is £250,000 or more (excluding VAT) — adjusted over 10 successive intervals.
  • Computers and computer equipment, where capital expenditure is £50,000 or more — adjusted over 5 successive intervals.

Once an asset is inside the scheme, the business must revisit the VAT recovery percentage every year for the length of the adjustment period, comparing the asset’s actual taxable use against the baseline set in year one. 

If taxable use rises, HMRC repays more VAT; if it falls, the business repays VAT already claimed. A change of use on disposal within the adjustment period can trigger a single, larger reconciliation covering all the remaining years at once.

 Businesses that are fully taxable are not automatically exempt from this – a change from taxable to exempt use, such as an office building later let on an exempt basis, can still trigger a clawback even where the business recovers all its VAT elsewhere.

Read: VAT on Online Marketplace Sales: What UK Sellers Need to Know About the New HMRC Consultation

What’s changing under the Capital Goods Scheme simplification?

HMRC is making two specific changes to CGS from 29 July 2026, confirmed in its policy paper on the simplification of the scheme. The threshold for land, buildings and civil engineering works increases, and computers leave the scheme completely.

  • Higher property threshold: the £250,000 trigger for land, buildings and civil engineering works rises to £600,000 (excluding VAT). Expenditure below that level will no longer create a CGS item at all.
  • Computers removed entirely: computers and items of computer equipment are taken out of the scheme’s scope. The old £50,000 threshold and 5-interval adjustment period for computer equipment cease to apply.

The legal mechanism is an amendment to Part XV of the VAT Regulations 1995 (SI 1995/2518). Regulation 113(2) is amended to remove the reference to computers and computer equipment, and regulation 113(4) is amended to raise the property threshold, with consequential changes to regulations 113A and 114.

When do the new CGS rules take effect?

The changes take effect on 29 July 2026 and are not retrospective. Capital expenditure incurred before that date — meaning goods or services already received, or goods already imported or acquired — continues to be governed by the old £250,000 and £50,000 thresholds, even if the asset’s adjustment period runs on for years afterwards.

In practice, this means:

  • A property purchase or refurbishment where the tax point falls before 29 July 2026 is tested against the old £250,000 threshold, regardless of when the deal completes on paper.
  • A property purchase or refurbishment where the tax point falls on or after 29 July 2026 is tested against the new £600,000 threshold.
  • Assets already inside CGS under the old rules stay inside CGS and continue their existing adjustment period — the threshold change does not remove them from the scheme retroactively.

Businesses part-way through a phased development that straddles the date should take advice before assuming which threshold applies, since the transitional rule is based on when expenditure is incurred, not when the wider project is signed off.

How does the higher £600,000 threshold work in practice?

A capital project only falls within CGS if its VAT-exclusive cost meets or exceeds the relevant threshold — everything below that line is recovered under normal partial exemption rules with no ongoing adjustment obligation. Here’s how that plays out for a typical partly exempt business.

Example

A dental practice buys and fits out a new clinic building for £400,000 (excluding VAT), incurring £80,000 of VAT. Under the current £250,000 threshold, that expenditure falls within CGS, committing the practice to ten years of annual adjustment calculations as its mix of NHS and private (exempt/taxable) work shifts. 

Under the new £600,000 threshold, the same £400,000 spend falls outside the scheme entirely. The practice recovers VAT once, under its normal partial exemption method, with no ten-year tail of adjustments to monitor or defend at inspection.

The same logic applies to refurbishments. A £900,000 refurbishment of an existing building still crosses the new threshold and remains a CGS item in its own right, tracked separately from the underlying property. Businesses working close to £600,000 should model the VAT position before committing to a build contract, since structuring the spend (or timing it either side of 29 July 2026) can determine whether ten years of adjustment obligations apply.

Why is HMRC removing computers from the Capital Goods Scheme?

HMRC says the computer category has become redundant because the cost of qualifying equipment has fallen well below the £50,000 threshold since the scheme was introduced in 1990, so it is very rarely triggered in practice. Removing it eliminates a compliance obligation that HMRC itself acknowledges delivers little practical benefit for the Exchequer.

The wider reform follows a long consultation history. The government launched a Call for Evidence in July 2019, after the 2017 Office of Tax Simplification VAT review flagged CGS as unnecessarily burdensome for smaller businesses. A summary of responses was published in March 2021, and the specific threshold and computer changes were formally announced on 28 April 2025 as part of the government’s Tax Update: Simplification, Administration and Reform work. HMRC’s own impact assessment projects negligible Exchequer cost and estimates ongoing administrative savings for businesses of around £0.6 million a year, concentrated among smaller property owners who previously fell within scope simply because of rising property values.

Who is affected by these changes to VAT on capital expenditure?

The changes affect any VAT-registered business incurring capital expenditure on land, buildings, civil engineering works, or computer equipment. In practice, the businesses most affected fall into a few groups.

  • Partly exempt businesses — including care providers, financial services firms, education providers and charities — who mix taxable and exempt income and have historically had to track CGS adjustments on modest property purchases.
  • Property investors and developers carrying out refurbishments or fit-outs in the £250,000–£600,000 band, who will now fall outside the scheme altogether.
  • SMEs buying or improving commercial premises, for whom the old threshold had become disproportionate as property values rose since 1990.
  • Any business holding computer equipment previously caught by the £50,000 threshold, which will simply stop being a CGS consideration from 29 July 2026.

Wholly taxable businesses are not exempt from the practical effects either — even a fully taxable business can find a change of use (for example, letting out surplus space on an exempt basis) crystallising a CGS liability, so the higher property threshold is a genuine simplification for that group too.

Also Read: Getting Your Business Ready for the Summer’s Temporary VAT Cut

What should businesses do to prepare?

Businesses with capital projects planned for mid-to-late 2026 should establish now whether their expenditure will fall inside or outside CGS once the new threshold applies. Three practical steps matter most.

  • Identify the tax point for any pending land, building or civil engineering spend, since that — not the completion date of the wider project — determines which threshold applies.
  • Review existing CGS records for assets already inside the scheme under the old £250,000 or £50,000 thresholds; these continue on their original adjustment period regardless of the reform.
  • Reassess partial exemption methods where CGS previously drove the choice of method, since removing an asset from CGS can change what special method (if any) is still worthwhile.

FAQs About HMRCs Changes To Capital Goods Scheme

Does the Capital Goods Scheme only affect partly exempt businesses?

No. While partly exempt businesses are most exposed, a fully taxable business can still be caught if the use of an asset later changes — for example, letting out space that was originally used for taxable trading. The scheme is triggered by a change in use, not by a business’s overall VAT status at the time of purchase.

What happens if I sell a capital item during the adjustment period?

Selling a capital item during its adjustment period crystallises all the remaining years’ adjustments in a single calculation, made in the VAT return covering the sale. If the sale itself is a taxable supply, the remaining intervals are treated as 100% taxable use; if it’s exempt, they’re treated as 0% taxable use, which can produce a significant one-off VAT repayment or claim.

Do the new thresholds apply retrospectively to buildings I already own?

No. The higher threshold only applies to capital expenditure incurred on or after 29 July 2026. Assets that were already inside the Capital Goods Scheme under the £250,000 or £50,000 thresholds remain inside the scheme and continue their existing adjustment period unaffected.

Is this confirmed law or still a proposal?

This is confirmed government policy, implemented through secondary legislation amending the VAT Regulations 1995, with an operative date of 29 July 2026 set out in HMRC’s published policy paper. It is not a consultation or draft proposal at this stage, though businesses should always check GOV.UK for the final statutory instrument reference nearer the commencement date.

Do I need an accountant for Capital Goods Scheme calculations?

Most businesses benefit from professional support, particularly where a project sits close to the £600,000 threshold or where partial exemption percentages fluctuate year to year. Getting the baseline interval wrong, or missing a change-of-use trigger, can lead to VAT assessments and penalties several years after the original purchase.

What if my capital expenditure is close to the £600,000 threshold?

Where spend is close to the threshold, timing and contract structuring can determine whether the Capital Goods Scheme applies at all. It’s worth taking advice before committing to a build contract, since expenditure incurred just before 29 July 2026 is tested against the old £250,000 limit even if the wider project completes later.

Next steps

If you’re planning capital expenditure on property, refurbishment or equipment in the run-up to this change, it’s worth reviewing the VAT treatment before contracts are signed rather than after. Apex Accountants & Tax Advisors works with property owners, developers and partly exempt businesses across the UK to assess Capital Goods Scheme exposure, structure capital projects efficiently and manage existing CGS adjustment schedules. Book a consultation with our VAT team to review your position ahead of the 29 July 2026 change.

Inheritance Tax Calculation UK: How It Works in 2026

A client came to Apex Accountants earlier this year after inheriting her late father’s house and modest savings. She was convinced the estate was far too small to attract any tax. It turned out her father had also gifted a large sum to her brother four years before he died, something she knew nothing about until the executors began pulling the paperwork together. That gift changed the whole calculation. It is a scenario we see often, and it is why inheritance tax calculation UK guidance matters before families assume an estate is too small to attract tax. 

With thresholds frozen for years and property values still climbing, the inheritance tax has quietly become one of the most talked about taxes in the country. Below, we answer the questions clients ask us most, in the order the calculation actually follows.

What is the basic tax-free allowance?

Every individual has a nil rate band of £325,000. The nil rate band has been fixed at that level since 2009 and, following Budget 2025, will remain frozen until 5 April 2031. Anything left within this threshold passes free of tax.

Is there anything else?

Yes. Where a main home is left to children, grandchildren or other direct descendants, an additional residence nil rate band of £175,000 can apply, taking a single person’s threshold to £500,000. This allowance is not automatic. It only applies to the value of a qualifying home passing to direct descendants and does not extend to lifetime gifts.

What about married couples?

Any part of the nil rate band or residence nil rate band that is left unused on the first death can be transferred to the surviving spouse or civil partner. In practice, this means a couple can often pass on up to £1 million between them before tax becomes due, provided the family home goes to children or grandchildren.

Does the residence allowance taper away for larger estates?

It does. For estates worth more than £2 million, the residence nil rate band is reduced by £1 for every £2 above that threshold. Once an estate reaches £2.35 million, the residence allowance disappears completely, leaving only the standard £325,000 threshold.

What rate do inheritance tax accountants UK apply above the thresholds? 

The standard rate is 40%, charged only on the portion of the estate above the available allowances. If at least 10% of the net estate is left to charity, the rate on the taxable remainder drops to 36%, which is worth factoring in at the will drafting stage rather than after the event.

How did the gift affect the inheritance tax calculation UK families had to make? 

This is the part people underestimate most. Gifts made in the seven years before death are generally pulled back into the estate for tax purposes. This is often called the seven-year rule. If a person survives seven years after making a gift, it falls outside the estate entirely. If they do not, the gift is added back, using up the nil rate band before the rest of the estate is assessed.

Where gifts made in that seven-year window exceed the nil rate band, taper relief can reduce the rate charged, but only on the portion of tax due, not on the value of the gift itself. The reduction runs on a sliding scale: full tax applies to gifts made within three years of death, then the effective rate steps down the longer the person survived afterwards, reaching its lowest point for gifts made between six and seven years before death.

Are any gifts exempt from the start?

Several are, and they sit outside the seven-year rule altogether, as set out in GOV.UK’s guidance on gifts:

  • An annual exemption of £3,000 per tax year, which can be carried forward one year if unused
  • Small gifts of up to £250 per person, provided no other exemption was used on that person in the same year
  • Wedding gifts, with limits depending on the relationship to the giver
  • Regular gifts made from surplus income, provided the giver’s standard of living is unaffected
  • Gifts between spouses or civil partners, and gifts to UK-registered charities

Is there anything on the horizon that could change these calculations?

Yes, and it is significant. From 6 April 2027, most unused pension funds and pension death benefits will be brought within the value of a person’s estate for inheritance tax purposes, following legislation confirmed in the Finance Act 2026. Pensions have historically sat outside the estate altogether, so this change will bring a meaningful number of estates into scope for the first time and increase the liability for others. Anyone relying on their pension as a tax-efficient way to pass on wealth should review that plan with accountants for inheritance tax planning well before the change takes effect. 

Where do we come in? 

For a reliable inheritance tax calculation UK families can act on, work out the full picture before assuming an estate is too small to matter. Add together the value of the home, savings, investments, and any gifts made in the past seven years, then apply the allowances in the right order. Getting the sequence wrong, or missing a lifetime gift, is one of the most common reasons families are caught out, and it is exactly the kind of detail inheritance tax accountants UK are asked to unpick once HMRC has already raised a question. 

The better approach is to work through the calculation properly before that happens. If you are unsure how your estate would be assessed, get in touch with Apex Accountants, accountants for inheritance tax planning, for a clear, professional review. It is a straightforward conversation now, rather than a complicated one later.

UK VAT Group Advice After Barclays Ruling Raises Concerns

A recent Upper Tribunal ruling has increased demand for UK VAT group advice by casting doubt over the terms on which international businesses can access UK VAT grouping, raising concerns that a structural advantage the UK has long promoted to attract overseas investment may be quietly eroding. 

The decision, handed down on 8 June 2026 in Barclays Services Corporation & Anor v HMRC [2026] UKUT 211 (TCC), dismissed an appeal by a US-incorporated company that sought to join its UK affiliate’s existing VAT group. The judgement turned primarily on whether the company’s UK branch qualified as a “fixed establishment” at the time of the application. The tribunal concluded it did not.

Tax advisers say the implications reach well beyond one bank’s corporate structure.

Why UK VAT group advice matters after Barclays 

Before examining the ruling, it is important to understand the implications.

Under section 43 of the Value Added Tax Act 1994, two or more commonly controlled corporate bodies can apply to be treated as a single taxable entity for VAT purposes. The immediate benefit is straightforward: supplies between members of the group are disregarded for VAT. No VAT is charged on intra-group transactions, and no compliance is required on those supplies.

For businesses that make largely exempt supplies, such as financial services and insurance firms, this matters significantly. Because they cannot recover the VAT they incur on services they receive, any VAT charged on intra-group services becomes a permanent, irrecoverable cost. VAT grouping eliminates this.

The UK’s approach has historically been described as relatively permissive compared to EU member states. For overseas companies wishing to join a UK VAT group, the key condition is that the company must have a “fixed establishment” in the UK — meaning a genuine operational presence with sufficient human and technical resources available to it.

What the Barclays Case Was About

Barclays Services Corporation (BSC) is a Delaware-incorporated company that provides shared services to other Barclays entities worldwide, including Barclays Execution Services Limited (BESL) in the UK. BESL is the representative member of the Barclays UK VAT group.

As part of a broader regulatory restructuring, BSC registered a UK branch in July 2017. VAT planning was openly identified as a key driver. BESL applied for BSC to join the VAT group on 1 December 2017, with internal documentation indicating a one-off benefit of £21 million was available if the branch was operational before year-end.

HMRC refused the application on two grounds. First, it said BSC had no fixed establishment in the UK at the date of the application. Second, and in the alternative, it argued that refusing admission was “necessary for the protection of the revenue”, a power HMRC holds under the legislation.

The First-tier Tribunal upheld HMRC’s refusal in August 2024. The Upper Tribunal, after hearing the case in March 2026, issued its judgement on 8 June 2026 and dismissed the appeal. The full decision is published on GOV.UK.

Why BSC failed the VAT group fixed establishment test 

The Upper Tribunal found that BSC’s UK branch was, in the tribunal’s own word, “skeletal” at the time of the application.

The key findings were the following:

  • UK-based staff were not employed by BSC directly
  • The branch lacked ownership or comparable control over those employees
  • The branch did not control the premises or technical systems it used
  • The resources associated with the branch had initially been attributed to BESL, not to BSC

A fixed establishment, the tribunal confirmed, requires more than a registered address or a Companies House filing. It requires the permanent presence of both human and technical resources that are genuinely controlled by and available to the overseas entity. Having costs attributed to a UK affiliate while the branch itself is being set up does not satisfy that test.

The Upper Tribunal added obiter comments — observations that were not strictly necessary for the outcome — that the bar for what qualifies as a fixed establishment may have been set too low in earlier cases. These remarks are not binding, but they are significant.

The ‘Protection of the Revenue’ Question

The second ground raises a broader concern.

HMRC can refuse a VAT grouping application where it considers the refusal “necessary for the protection of the revenue”. The Upper Tribunal, while not required to decide the point given its conclusion on fixed establishment, indicated that HMRC could reasonably have refused the application on this ground as well.

The reasoning was that the anticipated VAT savings were very considerable, the branch’s substance on the application date was minimal, and the timing of the application had been expressly driven by the opportunity to capture a one-off pre-year-end tax saving that was described internally as a “financial imperative”.

This is the part of the judgement that has attracted most concern from advisers. Abigail McGregor, a tax lawyer at Pinsent Masons, said the obiter comments on the protection of revenue would concern businesses. “The suggestion that there might be a test weighing substance against the amount of savings is especially concerning, as it introduces a level of uncertainty that will no doubt impact the entire industry,” she said.

What This Means in Practice

The immediate effect is clear. Overseas companies looking to join a UK VAT group must demonstrate real, controlled presence in the UK. A branch registration alone is insufficient. The substance must exist at the time of the application — not merely be anticipated.

The wider concern is different. If HMRC can refuse a grouping application on the basis that the VAT savings are large relative to the branch’s substance, even where a fixed establishment technically exists, the protection of the revenue power becomes a more significant constraint on VAT group planning than many businesses had previously assumed.

Several other cases are currently stayed behind the Barclays appeal. Their outcome will depend on their individual facts, but the Barclays decision provides the framework against which they will be assessed.

The potential business impact falls into three categories:

For existing cross-border VAT groups:

 Businesses should review whether their overseas member entities continue to satisfy the fixed establishment test. Circumstances change. A branch that was adequate when the group was formed may not meet the standard today, and HMRC has the power to direct that a company leave a group.

For businesses planning to restructure:

 The Barclays case illustrates the risk of applying for VAT grouping before the operational substance is fully in place. HMRC can scrutinise the timing of an application and the documented rationale for it. Internal communications that describe the purpose of a restructuring will be relevant.

For partially exempt businesses: 

Financial services firms, insurers, and others that cannot fully recover input VAT face the greatest practical exposure. For these businesses, the irrecoverability of VAT on intra-group services is a real cash cost. The ability to form a VAT group is not a planning luxury but a commercial necessity.

Cross-border VAT group advice after Barclays 

The ruling comes against a backdrop of shifting HMRC policy on international VAT grouping.

In November 2025, HMRC reversed its position on cross-border VAT grouping related to EU branches, restoring what is known as the “whole establishment” principle. That change, announced at the 2025 Autumn Budget, meant that services between a UK head office and an overseas branch are once again disregarded for VAT purposes under the intra-entity rules, even if the branch belongs to a VAT group in a different country. The ICAEW confirmed this in its Budget commentary.

That was a positive development for many international groups. The Barclays decision represents a countervailing pressure, tightening the conditions on which foreign subsidiaries and group service entities can be admitted to UK VAT groups in the first place.

How Apex Accountants & Tax Advisors Can Help

The Barclays decision is a practical reminder that VAT grouping, often treated as a one-time administrative matter, requires ongoing review. Eligibility conditions can change. HMRC’s approach to those conditions is evolving. And the consequences of getting it wrong can be significant.

Apex Accountants & Tax Advisors works with businesses, including multinational groups and partially exempt organizations, to:

  • Review the fixed establishment position of overseas entities currently within or seeking to join a UK VAT group
  • Assess the protection of the revenue risk for applications where anticipated savings are substantial relative to the branch’s operational substance
  • Advise on VAT group structuring ahead of corporate restructuring, M&A, or regulatory change
  • Support responses to HMRC enquiries into existing VAT group arrangements
  • Review intra-group service contracts for VAT treatment, including where deferred payments or performance-based fees are involved
  • Provide cross-border VAT group advice on the interaction between the whole establishment rules and domestic VAT grouping 

The VAT grouping rules are among the more complex areas of indirect tax. Early UK VAT group advice, before a restructuring or application proceeds, avoids the difficulties created when operational and tax planning run on different timelines. 

Contact Apex Accountants today to review your VAT group position. Book a free consultation with one of our specialist indirect tax advisers.

Frequently Asked Questions

What is a UK VAT group and who can join one?

 A UK VAT group allows two or more commonly controlled corporate bodies to be treated as a single taxable entity. Supplies between group members are disregarded for VAT. To join, each company must be established or have a fixed establishment in the UK and must be under common control with the other members. The rules are set out in section 43 of the Value Added Tax Act 1994. HMRC guidance is available at GOV.UK: VAT registration groups.

What is the VAT group fixed establishment test? 

A fixed establishment requires a genuine operational presence in the UK, with sufficient human and technical resources that are controlled by and available to the overseas entity. A registered branch, a Companies House filing, or premises used by a related UK company do not in themselves constitute a fixed establishment. The test is highly fact-sensitive. The Barclays ruling confirmed that resources attributed to a UK affiliate, rather than directly to the overseas branch itself, do not satisfy the requirement.

Can HMRC refuse a VAT grouping application even if conditions are met? 

Yes. Under the Value Added Tax Act 1994, HMRC has the power to refuse an application if it considers that refusal is “necessary for the protection of the revenue”. The Upper Tribunal in Barclays indicated this power could be exercised where anticipated VAT savings are large relative to the substance of the entity seeking to join and where the application appears primarily driven by tax savings rather than commercial reorganisation. This power is exercised on a reasonableness standard, meaning HMRC’s decision can be challenged but only where it could not reasonably have been satisfied that the grounds existed.

Does the Barclays ruling affect existing VAT groups? 

Not directly. The case concerned a refusal to admit a new member. However, HMRC also has powers to direct that a body leave a VAT group and can terminate grouping where it considers this necessary. Businesses with overseas entities in their VAT groups should review whether those entities continue to meet the fixed establishment test, particularly if the operational circumstances of the branch have changed since the group was formed.

What is the “protection of the revenue” power, and how far does it extend?

The protection of the revenue power allows HMRC to refuse or terminate VAT grouping where it believes a significant revenue loss would otherwise result. The Upper Tribunal’s comments in Barclays suggest that where the scale of anticipated savings is disproportionate to the substance of the applicant, this power could be exercised even where the fixed establishment test is technically met. These comments were obiter and are not legally binding, but they indicate the direction in which HMRC’s approach may develop.

What should businesses do now?

Businesses with cross-border VAT group arrangements should carry out a structured review of the fixed establishment position of any overseas members, check that operational substance is adequate and documented, and review the rationale for current grouping arrangements in light of the Barclays decision. Where a VAT group application is planned, the substance of the applicant entity should be established before the application is made, not as an anticipated future development.

Book a Free Consultation