Key Changes to VAT on Theatre Tickets in UK in 2026

The UK theatre sector is facing new VAT challenges in 2026. Updated VAT rules now apply to live performances, online streaming, and on-demand access, affecting how tickets are priced, reported, and taxed. These changes matter for both commercial producers and non-profit organisations. At Apex Accountants, we specialise in supporting theatres, venues, and performance companies with tailored tax and accounting advice. Our team helps clients apply the cultural exemptions, manage cross-border VAT on digital events, and maintain compliance with HMRC. This article explains the key VAT updates for 2026. It focuses on VAT on theatre tickets in UK, covering admissions, livestreamed and digital shows, registration thresholds, and practical steps for theatres to remain compliant while protecting revenue.

VAT on Theatre Tickets in UK

Standard VAT applies to most commercial theatre tickets at 20%. Only certain organisations qualify for the VAT cultural exemption for theatres, which applies when an organisation operates on a not-for-profit basis and is run by individuals with no financial interest. Eligible bodies and public organisations can exempt admission to live theatrical, musical, or dance events, while most commercial producers remain outside this exemption.

Charities can apply a separate fundraising exemption when events are genuinely promoted to raise funds. Wording on marketing and tickets must reflect the fundraising purpose. HMRC clarified this exemption in 2025, making compliance checks stricter.

VAT on Digital Performances

Digital performances remain a growth area. Livestreamed and on-demand shows carry distinct VAT treatment.

  • UK B2C sales: Tickets or access sold to UK consumers attract VAT at 20%.
  • EU B2C sales: Since January 2025, virtual events are taxed in the customer’s country. UK theatres must register for the EU One Stop Shop (OSS) to account for EU VAT in 2026.
  • B2B sales: Reverse charge rules apply when selling to overseas businesses. Evidence of business status must be retained.

When theatres sell performances through a digital platform, the platform takes responsibility for VAT collection and payment.

Place of Supply

For in-person shows, the place of supply is where the performance takes place. UK performances therefore attract UK VAT. For digital shows, the consumer’s location dictates the VAT treatment.

Registration and Theatre VAT rules 2026

UK organisations must register for VAT once taxable turnover exceeds £90,000 in a rolling 12 months. Exempt admissions are excluded from this threshold. Non-UK suppliers face no registration threshold and must register immediately if UK VAT is chargeable.

The updated Theatre VAT rules 2026 also highlight the importance of separating exempt income from standard-rated supplies. Proper record-keeping now plays a bigger role in HMRC compliance checks.

Case Study: Apex Accountants Supporting a Theatre Client

In 2025, Apex Accountants worked with a regional theatre that sold both live tickets and livestream access to audiences in the UK and EU. The theatre assumed all livestream sales should carry UK VAT. Our team reviewed the sales and confirmed that EU B2C transactions required VAT declaration in the customer’s country through the EU OSS scheme.

We implemented a VAT mapping system that separated UK and EU sales automatically. The client avoided penalties for incorrect filings and reclaimed input VAT worth £18,500. By restructuring ticket pricing and clarifying exemption eligibility for fundraising events, the theatre improved net margins by 7% within one season.

Practical steps for 2026

  • Review each income stream: ticket sales, livestreams, on-demand access, sponsorship, and fundraising.
  • Assess whether the exemptions apply.
  • Segment audiences by location to apply the correct VAT rate.
  • Review contracts with ticketing and streaming platforms to confirm VAT responsibility.
  • Update invoicing, ticketing, and VAT reporting systems to handle UK and EU rules.

Why Choose Apex Accountants

Choosing the right adviser is vital when dealing with complex VAT rules for theatre tickets and digital performances. Apex Accountants bring sector knowledge, tax expertise, and practical solutions that protect margins while keeping you compliant. We work closely with theatres and performance companies to clarify eligibility for VAT cultural exemption for theatres, manage cross-border VAT, and strengthen financial reporting.

Our approach combines technical accuracy with tailored guidance, giving you confidence that your ticketing and digital sales are fully compliant under the 2026 rules.

Contact us today to discuss your theatre’s VAT needs and let Apex Accountants support your financial performance.

Frequently Asked Questions

Is there VAT on theatre tickets in the UK?

Yes, at the standard 20% rate unless an exemption or reduction applies. Eligible non‑profit cultural bodies can charge admission VAT‑free under the cultural exemption.

Who Qualifies for the Cultural Exemption on VAT for Theatre Tickets?

Non-profit bodies whose activities fall within the cultural exemption rules in VAT Notice 701/47, broadly public bodies or eligible non-profit cultural bodies providing cultural events. Commercial theatres and producers generally cannot use the exemption and charge 20%.

Should a touring theatre company register for VAT?

Not necessarily. VAT registration is compulsory only when taxable turnover exceeds the current threshold. Voluntary registration may be disadvantageous if ticket income is exempt or customers cannot reclaim VAT. Seek specialist advice.

Should theatres charge VAT on tickets they sell?

Usually, commercial theatres must charge VAT on taxable admissions, even when selling another company’s tickets. However, qualifying cultural performances may be exempt when supplied by a public body or eligible non-profit body.

Can the touring company sell tickets without VAT?

The company cannot simply choose ‘no VAT’. Ticket treatment depends on who legally supplies admission and whether that supplier qualifies for exemption. Contracts should identify the promoter, seller, VAT status, and responsibility clearly.

Does theatre hire attract VAT?


Theatre hire is generally a separate commercial supply and normally standard-rated, regardless of whether performance tickets are exempt. Confirm the venue’s VAT invoice and establish whether the agreement is for hire, production services, or admission sharing.

Are ballet performances shown in cinemas VAT-exempt?

A cinema screening of a ballet or theatre recording is not automatically an exempt live performance. Exemption is restricted to qualifying admissions supplied by public or eligible cultural bodies; ordinary commercial cinema admissions are generally taxable.

How should ticket agreements be worded?

State who supplies admission, who collects payment, and whether VAT is included, exempt, or chargeable. Do not describe tickets as VAT-free without evidence. Have the venue or accountant confirm the treatment in writing beforehand.
VAT Return Deadlines in the UK: 2026 Complete Guide 

VAT return deadlines are an important part of VAT compliance for UK businesses. Missing a deadline can lead to penalty points, late payment charges and interest, so businesses need to know when their returns and payments are due. 

Most VAT-registered businesses submit a VAT return every 3 months. This period is known as the VAT accounting period. The usual deadline is one calendar month and 7 days after the end of the VAT period. This date is also usually the deadline for paying VAT owed.

For example, if your VAT period ends on 31 March, your VAT return and payment are usually due by 7 May.

What Is a VAT Return?

A VAT Return shows:

  • how much VAT your business charged on sales
  • how much VAT your business paid on purchases
  • whether you owe VAT
  • whether you can reclaim VAT

Even if there is no VAT to pay or reclaim, a VAT-registered business still needs to submit a return. This is often called a nil VAT Return.

Standard VAT Return Deadline

For most businesses, the VAT deadline follows a simple rule.

VAT period endsVAT Return usually dueVAT payment usually due
31 March7 May7 May
30 June7 August7 August
30 September7 November7 November
31 December7 February7 February

The exact date can vary depending on your VAT accounting period. Your VAT online account shows the deadline for VAT return submission, your other return dates and when payment must clear.

Simple Rule to Remember

SituationDeadline
Standard quarterly VAT Return1 month and 7 days after the period ends
Monthly VAT ReturnUsually 1 month and 7 days after the month ends
Nil VAT ReturnSame deadline as normal
VAT paymentUsually the same date as the return deadline

This means the VAT return filing deadline and payment deadline are normally the same.

VAT Payment Deadline

VAT payments must reach the account by the payment deadline. Therefore, businesses should not delay making payments until the last minute.

Different payment methods can take different amounts of time. Direct debit can help with timing because the payment is normally collected 3 working days after the VAT Return is submitted, but the return must still be filed by the deadline.

What If the Deadline Falls on a Weekend or Bank Holiday?

  • Filing deadline: The same date applies even if it falls on a weekend or bank holiday. You still must file by that date (e.g., if 7 May is a Sunday, the deadline is still 7 May).
  • Payment timing: If you pay by bank transfer, it must be in HMRC’s account by the close of business on the due date. If the payment date is a weekend or bank holiday, aim to pay on the last working day before it to avoid late-payment penalties.

You can file online on the official date, but if the due date is a non-working day, plan for the payment to clear by the last working day before that date. 

Annual Accounting Scheme Deadlines

Some small businesses use the VAT Annual Accounting Scheme. The scheme works differently from standard quarterly VAT returns.

Under this scheme, a business usually submits one VAT return each year. The deadline for VAT return submission depends on the length of the accounting period. If the accounting period is between 4 and 12 months, the return is due 2 months after the end of the accounting period. When the accounting period lasts fewer than 4 months, the return must be submitted 1 month after the period concludes.

Annual Accounting SchemeDeadline
Accounting period of 4 to 12 monthsReturn due 2 months after period end
Accounting period under 4 monthsReturn due 1 month after period end
Monthly advance paymentsDue at the end of months 4 to 12
Quarterly advance paymentsDue at the end of months 4, 7 and 10
Final balancing paymentDue with the annual return

This scheme can help with budgeting, but the payment plan must be followed carefully.

Payments on Account for Large Businesses

Large businesses with high VAT liabilities may need to make VAT payments on account.

These businesses usually make advance payments during the VAT quarter, instead of paying the full amount only at the return deadline. The payment dates are the last working day of the second and third months of the VAT quarter. The 7-day electronic payment extension does not apply to these payments.

Payment typeWhen it is due
First payment on accountLast working day of month 2
Second payment on accountLast working day of month 3
Balancing paymentWith the VAT Return
VAT ReturnBased on the business payment schedule

This mainly affects larger businesses, but it is important to know if your VAT position grows over time.

What Happens if You Miss Your VAT Deadline?

For VAT periods starting on or after 1 January 2023, late submission penalties use a points-based system. A business gets a penalty point each time it submits a VAT Return late. This includes nil returns and repayment returns. Once the penalty point threshold is reached, a £200 penalty can apply.

Filing frequencyPenalty point threshold
Annual2 points
Quarterly4 points
Monthly5 points

After the threshold is reached, further late returns can lead to more £200 penalties.

What Happens If VAT Is Paid Late?

Late payment penalties can apply when VAT is not paid in full by the due date.

The current late payment rules are:

How late the VAT payment isPenalty position
Up to 15 days lateNo first or second late payment penalty
16 to 30 days lateFirst penalty based on VAT owed at day 15
31 days or more lateFurther penalty and daily penalty may apply

Late payment interest can also run from the first day the payment is overdue until it is paid in full.

Tips to Avoid Missing a VAT Deadline

  • Check your VAT online account regularly.
  • Keep digital VAT records up to date.
  • Reconcile sales and purchase records before the period ends.
  • Set reminders at least 2 weeks before the deadline.
  • Allow enough time for payment to clear.
  • Do not ignore nil returns.
  • Review your VAT scheme if cash flow is tight.

How We Help Businesses File VAT Returns

Apex Accountants offers comprehensive support to keep your VAT affairs on track:

  • VAT return preparation: We prepare and file your VAT returns accurately and on time, so you never miss a deadline.
  • Deadline reminders: Our team monitors your VAT periods and sends alerts well before filing and payment dates.
  • Scheme advice: We can advise if annual accounting, flat rate, or other schemes suit your business and handle the filings accordingly.
  • Payment planning: We help you manage cash flow for VAT payments – including setting up direct debit and scheduling instalments, if needed.
  • Penalty help: If you face any HMRC penalties or queries, we’ll liaise with HMRC on your behalf and guide you through appeals.

Always file and pay your VAT on time to avoid fines. Keep the one-month+7-day rule in mind, use your online VAT account for dates, and consider professional help to manage your VAT obligations smoothly.

With Apex Accountants handling your VAT returns, you can focus on running your business while we manage the deadlines. We prepare accurate filings, check the figures carefully and help you meet the correct VAT payment deadline without last-minute stress.

We also support you with payment planning, digital records and timely reminders, so your VAT returns stay compliant and organised throughout the year.

Frequently Asked Questions About VAT Return Deadlines 

When exactly is my VAT return due? 

It’s due 1 calendar month + 7 days after your VAT period ends. For most quarterly filers, that means if your period ended 31 March, the return is due by 7 May.

What if I owe no VAT? 

You still must submit a nil return by the deadline. Failing to file a nil return on time still risks penalties.

Does Direct Debit extend the deadline?

No – it doesn’t change the filing due date. It only means HMRC collects funds 3 days later, reducing the chance of a late payment.

What if the due date is a weekend or holiday? 

Make sure any payment clears on the last working day before the due date. (Filing the return should still be by the official date.)

How can I find my exact deadline? 

Your online VAT account will list all upcoming return and payment deadlines. It’s wise to check there or set up reminders.

When do I have to submit my VAT return and pay HMRC?

Under the standard scheme, both your VAT return and payment are due one month and seven days after the end of your VAT accounting period.

For example:

  • Quarter ends: 31 March 2026
  • VAT return deadline: 7 May 2026
  • VAT payment deadline: 7 May 2026

Businesses using the Annual Accounting Scheme file once a year, with the return due two months after the scheme year ends.

How many points do I get before HMRC charges a VAT penalty?

HMRC uses a points-based penalty system for late VAT returns.

The penalty thresholds are:

  • Quarterly filers: 4 points
  • Monthly filers: 5 points
  • Annual filers: 2 points

Once you reach your threshold, HMRC charges a £200 penalty.

Points expire only after a sustained period of compliance. Once you have been penalised, every further late return while you remain at the threshold triggers another £200 charge.

What interest does HMRC charge on late VAT payments in 2026?

HMRC’s late payment interest rate currently stands at 7.75%, charged from the day after the payment due date.

On top of interest:

  • A 2% penalty applies to VAT still unpaid 30 days after the deadline
  • Further 2% penalties can apply at 6 and 12 months

This means even a relatively small delay can become more expensive if the VAT remains unpaid.

R&D Tax Relief 2026: New HMRC Rules and How to Claim Successfully

We’re seeing more companies come to us after having their R&D tax relief claims questioned, returned, or rejected by HMRC. The landscape has changed significantly since the previous SME and RDEC regimes were replaced for accounting periods beginning on or after 1 April 2024. Compliance requirements have also tightened, meaning businesses need to pay closer attention to eligibility, supporting evidence and filing requirements.

The good news is that genuine innovation can still generate meaningful tax relief. However, companies now need to be more precise when documenting their R&D activities and identifying qualifying expenditure.

Key Takeaways:

  • The merged RDEC scheme offers a 20% taxable expenditure credit on qualifying R&D spend. Loss-making R&D-intensive SMEs may instead qualify for Enhanced R&D Intensive Support (ERIS).
  • HMRC received an estimated 46,950 R&D claims for 2023/24, a 26% decline from the previous year.
  • The Additional Information Form (AIF) is mandatory and must be submitted before, or on the same day as, the Company Tax Return containing the R&D claim.
  • A Claim Notification Form is required only for certain companies, including first-time claimants and some businesses without a sufficiently recent R&D claim.
  • HMRC introduced a targeted Advance Assurance pilot in 2026 to provide eligible SMEs with greater certainty on specific complex or high-risk areas of a proposed claim.

What is R&D tax relief in 2026?

R&D tax relief is a government incentive that allows eligible UK companies to obtain Corporation Tax relief or an expenditure credit for qualifying research and development. For accounting periods beginning on or after 1 April 2024, the merged R&D expenditure credit scheme and Enhanced R&D Intensive Support form the current framework.

To qualify, a project must seek an advance in science or technology by attempting to resolve scientific or technological uncertainty. The advance must not be something that a competent professional in the relevant field could readily work out.

Work in the arts, humanities or social sciences does not qualify simply because it is innovative. However, companies operating in creative industries can still qualify where their projects involve genuine scientific or technological uncertainty. This distinction is particularly important for creative businesses undertaking technical R&D.

SchemeWho can claimRatePotential benefit
Merged RDECCompanies with qualifying R&D expenditure20% taxable expenditure creditApproximately 15% to 16.2% net depending on Corporation Tax treatment
ERISLoss-making R&D-intensive SMEs meeting the intensity condition86% additional deduction, producing 186% enhanced expenditure, with a 14.5% payable credit on surrenderable lossUp to approximately 26.97% of qualifying expenditure where sufficient surrenderable loss is available

The merged RDEC credit is taxable and is dealt with through a series of statutory payment steps. Depending on the company’s tax position, it can offset Corporation Tax and other liabilities, with an amount potentially becoming payable after the relevant restrictions are applied.

How does the merged RDEC scheme work for your company?

The merged RDEC scheme provides a taxable expenditure credit equal to 20% of qualifying R&D expenditure.

For a company spending £100,000 on qualifying R&D, the gross credit would be £20,000. Because the credit is taxable, a company subject to Corporation Tax at 25% would generally retain a net benefit of approximately £15,000. At a 19% Corporation Tax rate, the equivalent net benefit would be approximately £16,200.

There is also a PAYE cap on the amount that can ultimately be paid to a company in an accounting period unless an exemption applies. Broadly, the cap is £20,000 plus 300% of the company’s relevant PAYE and National Insurance contribution liabilities for that period. For shorter accounting periods, the £20,000 element is proportionately reduced.

Qualifying expenditure can include staff costs, consumable materials, software, data and cloud computing costs, externally provided workers and certain payments to contractors, subject to the relevant conditions and restrictions.

These rules can be particularly important in technically complex industries such as M&E engineering, where development projects may involve qualifying design, testing and technical problem-solving.

Restrictions also apply to certain overseas contractor and externally provided worker costs.

Who qualifies for Enhanced R&D Intensive Support (ERIS)?

ERIS is available to loss-making SMEs whose qualifying R&D expenditure meets the R&D intensity condition.

For accounting periods beginning on or after 1 April 2024, qualifying R&D expenditure generally needs to represent at least 30% of the company’s relevant total expenditure, subject to the detailed rules, including the intensity-condition grace period.

A qualifying company can claim an additional deduction equal to 86% of its qualifying R&D expenditure. This means £100,000 of qualifying expenditure can produce enhanced expenditure of £186,000.

The payable credit is then calculated at 14.5% of the amount surrendered. The surrenderable loss is the lower of:

  • the enhanced expenditure; or
  • the company’s relevant trading loss after the additional R&D deduction.

Therefore, a loss-making R&D-intensive SME with £100,000 of qualifying expenditure and sufficient surrenderable losses could receive a maximum payable credit of approximately £26,970.

The actual benefit may be lower where the company’s available surrenderable loss is below £186,000.

A company that qualifies for ERIS can choose to claim under the merged RDEC scheme instead, but it cannot claim under both schemes for the same expenditure.

What is the Additional Information Form and why does it matter?

The Additional Information Form is mandatory for R&D claims and must be submitted before, or on the same day as, the Company Tax Return containing the claim.

Where the AIF and CT600 are filed on the same day, the AIF should be submitted first. Filing the Company Tax Return before completing this requirement can result in the R&D claim being removed.

The AIF requires detailed information including:

  • the company’s UTR, employer PAYE reference and VAT registration details where applicable
  • details of the main senior internal person responsible for the R&D claim
  • details of agents involved in preparing or advising on the claim
  • the relevant accounting period
  • qualifying expenditure details
  • project-by-project information about the R&D activities
  • explanations of the scientific or technological advances and uncertainties involved

Companies should make sure the accounting period information matches the Company Tax Return exactly.

A separate Claim Notification Form may also be required for accounting periods beginning on or after 1 April 2023. However, this requirement does not apply to every company.

It generally applies to first-time R&D claimants and companies whose previous claim falls outside the relevant three-year look-back period. Where notification is required, the claim notification period generally ends six months after the end of the relevant period of account.

Missing a required notification deadline can make the subsequent R&D claim invalid, so businesses should establish whether the requirement applies before filing.

How likely is an HMRC enquiry into my R&D claim?

HMRC has increased compliance activity around R&D tax relief significantly in recent years. This includes additional compliance staff and specialist work aimed at tackling error and abuse.

However, there is no single current published enquiry percentage that can reliably predict whether an individual R&D claim will be investigated.

What the latest figures clearly demonstrate is a substantial decline in claim volumes. The September 2025 R&D tax relief statistics estimate that there were 46,950 claims for 2023/24, down 26% from the previous year.

SME scheme claims declined more sharply, falling by approximately 31%.

Metric2023/24
Total R&D claims46,950
SME scheme claims36,885
RDEC claims10,065
Total relief claimed£7.6bn
Change in total claims-26%
Change in SME claims-31%

The total amount of relief claimed remained substantial at approximately £7.6 billion, only around 2% lower than the previous year’s estimate.

The reduction in smaller-company claims reflects the wider compliance and procedural changes affecting businesses across the country. Similar pressures have been seen among SMEs dealing with falling R&D tax relief claim volumes.

For businesses, the practical lesson is straightforward: prepare every claim on the assumption that HMRC may ask for supporting evidence.

What penalties apply if HMRC rejects my R&D claim?

An HMRC enquiry or rejected claim does not automatically mean that a penalty will apply. Penalties generally depend on whether an inaccuracy caused potential lost revenue and the behaviour that led to it.

For standard onshore inaccuracies, maximum penalties can include:

  • Careless inaccuracies: up to 30% of the potential lost revenue
  • Deliberate but not concealed inaccuracies: up to 70%
  • Deliberate and concealed inaccuracies: up to 100%

The actual percentage can be reduced depending on factors including disclosure and cooperation.

Late payment interest can also apply where additional Corporation Tax becomes payable. The current HMRC late payment interest rate is 7.75% per annum, effective from 9 January 2026.

For example, if an inaccurate R&D claim causes £50,000 of potential lost revenue, a careless inaccuracy could carry a maximum standard penalty of £15,000. A deliberate but not concealed inaccuracy could carry a maximum penalty of £35,000, while a deliberate and concealed inaccuracy could reach £50,000.

Actual penalties may be lower depending on the circumstances and the quality of disclosure.

A further development in 2026 is a proposed criminal offence relating to reckless untrue statements or declarations involving direct tax. The consultation closed on 16 August 2026. The proposal is not currently law, so companies should not treat the potential criminal sanction as an existing penalty.

What is the new R&D Advance Assurance pilot?

HMRC launched a targeted R&D Advance Assurance pilot in May 2026 for eligible SMEs.

Unlike full-claim Advance Assurance, the targeted pilot does not amount to approval of an entire R&D claim. Instead, eligible companies can seek greater certainty on specific complex or high-risk areas before filing.

This can be useful where a company faces uncertainty over issues such as whether particular activity qualifies as R&D, overseas expenditure, contracted-out R&D or the PAYE cap.

A separate full-claim Advance Assurance service also remains available to qualifying SMEs making their first R&D tax relief claim.

Advance Assurance does not replace the actual R&D claim or the other filing requirements. It gives eligible businesses greater clarity before the claim is submitted.

How can UK companies strengthen their R&D claim?

Strengthening an R&D claim begins with documenting the scientific or technological uncertainty the project sought to resolve, rather than simply compiling costs at the end of the accounting period.

A strong technical explanation should make clear:

  • the existing level of science or technology
  • the advance the project sought to achieve
  • the scientific or technological uncertainty encountered
  • why that uncertainty could not readily be resolved by a competent professional
  • how the project attempted to overcome the uncertainty

Practical steps include:

  • Keep contemporaneous technical records such as project plans, experiment logs, design iterations and test results.
  • Complete the AIF using specific project-level explanations rather than generic descriptions.
  • Check whether a Claim Notification Form is required and submit it within the relevant deadline where necessary.
  • Identify the senior internal person responsible for the claim.
  • Disclose the agents involved where required.
  • Separate qualifying R&D expenditure clearly from routine business activity.
  • Review contractor and overseas expenditure carefully before including it.

Strong technical evidence is particularly important in sectors where innovative commercial work and qualifying R&D can overlap. For example, motion graphics studios developing technically challenging production methods need to distinguish ordinary creative work from projects involving genuine technological uncertainty.

The same distinction matters when developing AI security systems that involve genuine technical challenges or undertaking innovation within wearable technology, smart textiles and sensor development.

Good documentation does not guarantee that HMRC will not open an enquiry, but it puts the company in a stronger position to explain and support the basis of its claim.

Frequently Asked Questions

Can I still claim R&D tax relief if my company is profitable?

Yes. Eligible profitable companies can generally claim under the merged RDEC scheme for accounting periods beginning on or after 1 April 2024.

The scheme provides a taxable expenditure credit equal to 20% of qualifying expenditure. The credit passes through statutory payment steps and can offset Corporation Tax or other liabilities, with an amount potentially becoming payable depending on the company’s circumstances.

Loss-making R&D-intensive SMEs may instead qualify for ERIS where they satisfy the relevant conditions.

How much does it cost to use an accountant for an R&D claim?

The cost varies between advisers and depends on the size and complexity of the claim.

Advisers may use fixed fees, hourly rates, contingent fees or a combination of different fee structures. Businesses should understand exactly what the quoted fee covers, including eligibility assessment, technical documentation, preparation of the AIF, tax calculations and support if HMRC later opens an enquiry.

Price should therefore be considered alongside the adviser’s technical expertise, sector experience and approach to compliance.

What happens if I miss the Claim Notification Form deadline?

First establish whether your company was actually required to submit a Claim Notification Form.

Not every claimant needs to complete one. The requirement generally applies to first-time claimants and certain companies without a sufficiently recent qualifying R&D claim.

If notification was required and the deadline has passed, the subsequent R&D claim may be invalid for that accounting period. Businesses should therefore review their previous claim history and obtain advice before assuming either that notification is required or that relief has been lost.

Does software development qualify for R&D tax relief?

Software development can qualify where a project seeks an advance in technology and involves technological uncertainty that a competent professional could not readily resolve.

Examples may include developing new algorithms, overcoming significant performance constraints or creating technically novel systems where existing solutions cannot achieve the required outcome.

Routine website development, standard app configuration or the implementation of off-the-shelf software does not automatically qualify.

What is the difference between the old SME scheme and ERIS?

The previous SME scheme changed over time, so one historic rate should not be applied to every old SME claim.

Before the April 2023 changes, the SME scheme generally provided a 130% additional deduction, producing total enhanced expenditure of 230%, alongside a 14.5% payable credit rate on qualifying surrenderable losses.

The rules changed for expenditure incurred from April 2023, including enhanced support for qualifying R&D-intensive SMEs.

For accounting periods beginning on or after 1 April 2024, ERIS provides qualifying loss-making R&D-intensive SMEs with an 86% additional deduction, producing enhanced expenditure of 186%, and a payable credit equal to 14.5% of the surrenderable loss.

Companies that do not qualify for ERIS generally use the merged RDEC scheme where otherwise eligible.

Can I claim R&D tax relief for work done overseas?

Overseas contractor and externally provided worker expenditure is more restricted under the current merged scheme and ERIS rules.

In general, expenditure relating to R&D activity undertaken outside the UK may be excluded. Limited exceptions can apply where conditions necessary for the R&D are not present in the UK, are present overseas and it would be wholly unreasonable to replicate those conditions in the UK.

Relevant circumstances may include particular geographical, environmental or regulatory requirements. Lower labour costs or greater availability of overseas workers alone are not sufficient.

Special rules may also apply to certain Northern Ireland companies claiming ERIS.

Businesses using overseas developers, engineers or specialist contractors should therefore review the location and contractual arrangements carefully before including the expenditure.

How Apex Accountants Can Help

If your company is investing in innovation, whether through new software, engineering solutions, digital systems or technically challenging products, R&D tax relief can provide valuable support where the eligibility requirements are met.

Apex Accountants supports research and development projects across a wide range of industries, helping businesses identify qualifying activity, prepare technical evidence, calculate eligible expenditure and complete the required documentation.

Our R&D tax team can support you with:

  • assessing whether projects meet the scientific or technological advance test
  • identifying qualifying expenditure
  • preparing the Additional Information Form
  • checking whether Claim Notification is required
  • calculating relief under the merged RDEC scheme or ERIS
  • reviewing contractor and overseas expenditure
  • supporting responses where HMRC opens an enquiry
  • assessing whether Advance Assurance may be appropriate

The rules have become more detailed, but eligible businesses can still access valuable relief where claims are carefully prepared and properly supported.

Book a free consultation to discuss your R&D activities with our team. We can review your projects, explain the relevant relief route and outline the compliance steps needed to prepare a robust claim.

A Complete Guide to UK Airbnb Tax: Rules, Reliefs and Rates for 2026/27

A host can receive regular Airbnb bookings and still be unsure whether HMRC sees the income as a small side activity or a taxable property business. The answer depends on how much you receive, whether you are letting your main home or a separate property, and which expenses or reliefs you claim.

For 2026/27, UK Airbnb tax is not a separate tax regime. Most individual hosts are taxed under the normal property income rules, while qualifying hosts using their main home may benefit from the Rent a Room Scheme. The former Furnished Holiday Lettings tax regime no longer applies.

Quick Answer

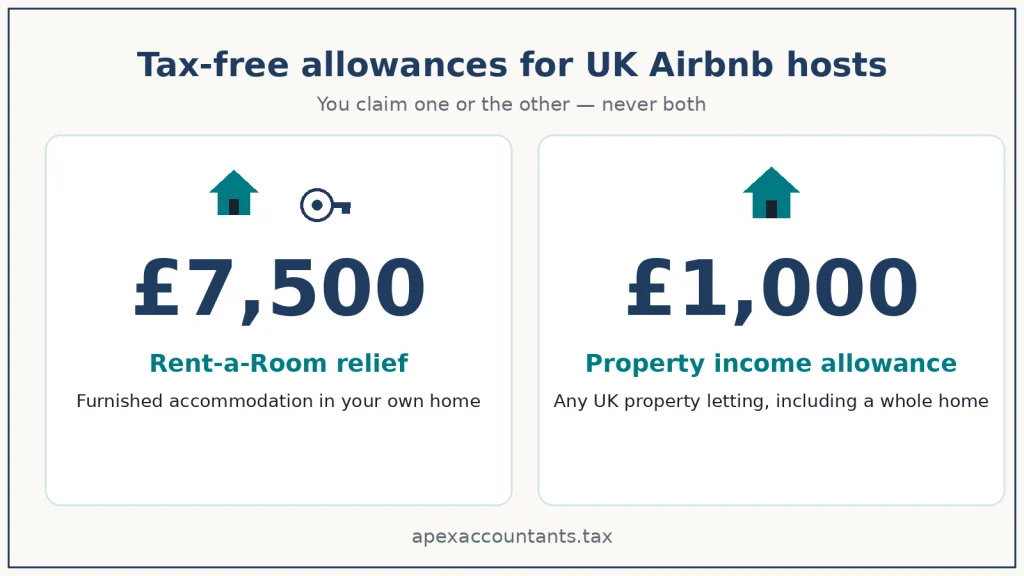
  • Individuals can generally receive up to £1,000 of qualifying gross property income under the property allowance before tax reporting is normally required.
  • The Rent a Room Scheme can provide up to £7,500 tax-free, reduced to £3,750 where the income is shared.
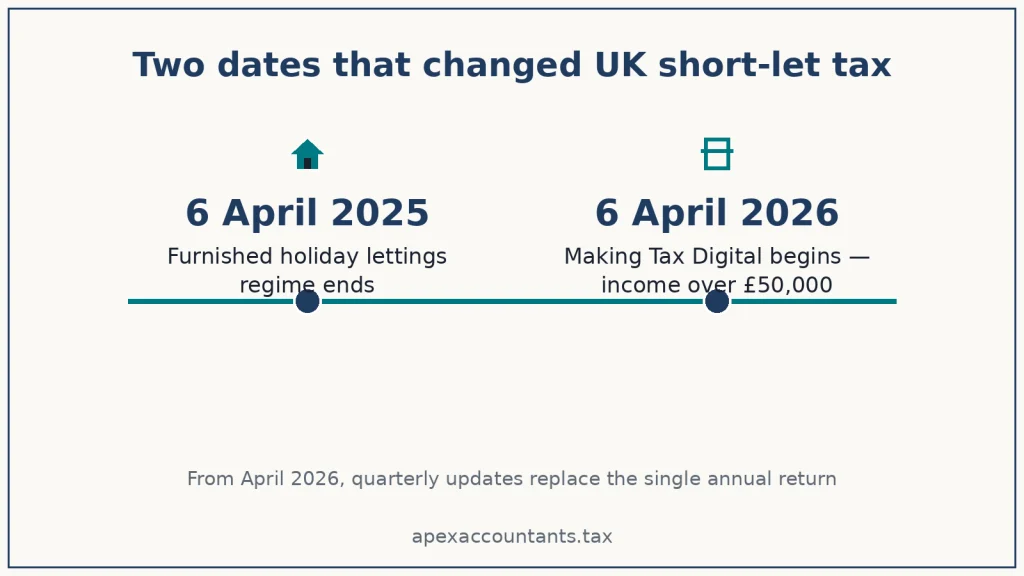
  • The special Furnished Holiday Lettings regime ended on 6 April 2025 for Income Tax and Capital Gains Tax.
  • Airbnb and other qualifying platforms can report host information to HMRC. The widely quoted 30 transactions, or €2,000 threshold relates to sales of goods, not property rentals.
  • Making Tax Digital for Income Tax became mandatory from 6 April 2026 for qualifying sole traders and landlords whose 2024/25 qualifying income exceeded £50,000.

Do You Have to Pay UK Airbnb Tax on Hosting Income?

Airbnb income is generally taxable when your receipts exceed the relief or allowance available to you. For most hosts letting an investment property, the starting point is the normal property income rules rather than a special Airbnb tax rate.

The amount subject to income tax will usually depend on your taxable property profit after allowable deductions. However, an individual with relatively small receipts may instead be able to use the £1,000 property allowance.

The position is different where you provide furnished accommodation in your only or main residence. In that situation, the Rent a Room Scheme may provide a substantially larger exemption.

This distinction matters because the two reliefs cannot simply be stacked together.

How much can you earn from Airbnb before paying tax?

You can earn up to £1,000 of gross property income tax-free each tax year, or up to £7,500 if the letting qualifies for Rent-a-Room relief. These are two different allowances with different conditions, and choosing between them matters — you claim one or the other for the same income, never both.

Property income allowanceRent-a-Room relief
Annual tax-free limit£1,000 of gross income£7,500 of gross income (£3,750 if you share the income with someone else)
Which lettings qualifyAny UK property income, including a whole flat or house let on AirbnbFurnished accommodation in your own home, while you live there — a lodger-style let
What it replacesActual expense deductions, if you claim itActual expense deductions for the letting, if you claim it
Best forHosts with low income and few expensesHosts letting a room (or their whole home occasionally) with income under £7,500

The practical difference is sharp. A host letting an entire second flat has no choice — the £1,000 allowance is the only option. A host letting a spare bedroom in the house they live in, or letting the whole house for a few weeks while on holiday, can usually use Rent-a-Room’s higher £7,500 limit. Above £7,500, you can still claim Rent-a-Room and pay tax only on the excess, which is often better than deducting actual expenses if those are small.

Remember the furnished-room requirement: Rent-a-Room does not apply to unfurnished space, and it only works for lettings in a property that is your home during the tax year.

Which Airbnb Tax UK Exemptions and Allowances Can Hosts Claim?

The main relief depends on what you are actually letting. A host renting furnished accommodation in their main home should consider Rent a Room, while a host letting a separate property may need to compare the £1,000 property allowance with actual deductible costs.

The £1,000 Property Allowance

Individuals can generally receive up to £1,000 of gross qualifying property income each tax year without needing to tell HMRC about that income. Joint owners can each potentially have their own £1,000 allowance against their share of qualifying receipts.

If gross receipts exceed £1,000, you may be able to deduct the £1,000 allowance instead of claiming actual expenses.

That choice requires care. You cannot claim the property allowance while also deducting actual expenses for the same property business, and HMRC prevents use of the allowance where you claim the residential property finance cost tax reduction.

The £7,500 Rent a Room Scheme

If you let furnished accommodation in your only or main home, Rent a Room can exempt gross receipts of up to £7,500 a year. Where another person also receives income from letting accommodation in the same residence, the limit is normally £3,750 each.

If receipts exceed the limit, you can generally choose between:

  • paying tax on your actual rental profit after eligible expenses; or
  • using Rent a Room’s alternative basis, under which the excess above the applicable exemption limit becomes taxable.

HMRC confirms that Rent a Room may apply to furnished accommodation in a person’s main residence and can also apply in relevant guest house or bed-and-breakfast circumstances.

How Is Airbnb Income Tax UK Calculated in 2026/27?

For an individual host in England, Wales or Northern Ireland, taxable Airbnb property profit is generally added to other taxable income and charged at the person’s marginal Income Tax rate. For 2026/27, the main rates remain 20%, 40% and 45%, with a standard Personal Allowance of £12,570 where it is fully available. Scottish taxpayers are subject to separate Scottish Income Tax bands.

2026/27 BandTaxable IncomeMain Rate
Personal AllowanceUp to £12,5700%
Basic rate£12,571 to £50,27020%
Higher rate£50,271 to £125,14040%
Additional rateAbove £125,14045%

A Simplified Airbnb Tax Example

Assume an English higher-rate taxpayer has:

  • Airbnb receipts of £24,000
  • ordinary allowable running costs of £6,000
  • mortgage interest of £8,000

Their taxable property profit before the finance-cost tax reduction is £18,000, because an individual residential landlord cannot deduct mortgage interest directly when calculating rental profit.

If all £18,000 falls within the 40% band, the initial tax is £7,200.

Assuming the entire £8,000 finance cost qualifies for relief and no restriction in HMRC’s calculation applies, the current 20% tax reduction is £1,600, reducing the illustrative income tax to £5,600. HMRC calculates the finance cost reduction by reference to the lowest of qualifying finance costs, property business profits and adjusted total income, so an actual calculation may differ.

This is one reason Airbnb hosts with borrowing costs should not estimate tax simply by deducting mortgage interest from cash profit.

What Expenses Can Airbnb Hosts Deduct?

Hosts using the actual-expenses method can generally deduct revenue costs incurred in running the property business, provided the costs satisfy the normal property-income rules. HMRC lists a range of deductible day-to-day expenses.

These can include:

  • letting or management fees
  • accountancy fees
  • buildings and contents insurance
  • repairs and maintenance, but not improvements
  • gas, electricity, water and other utilities paid by the landlord
  • Council Tax where borne by the landlord
  • cleaning and gardening
  • advertising and other direct letting costs
  • rent, ground rent and service charges where applicable

Costs that improve the property rather than merely repair it are normally capital expenditure rather than an immediate deduction against rental profit.

For furniture and household equipment, Replacement of Domestic Items Relief may be available when an existing qualifying item is replaced. The initial cost of furnishing a property does not automatically qualify under this replacement relief.

Airbnb’s own host service charge is not an additional UK tax. Where a platform fee is incurred directly for the letting business, its tax treatment should be considered under the normal rules for business-related letting costs.

What Changed When the Furnished Holiday Lettings Tax Regime Ended?

The special Furnished Holiday Lettings regime ceased for Income Tax and Capital Gains Tax from 6 April 2025 and from 1 April 2025 for Corporation Tax purposes. Former qualifying FHLs therefore generally fall into the ordinary property tax regime.

For Airbnb and other short-term accommodation owners, the abolition removed several advantages.

AreaFormer FHL TreatmentPosition After Abolition
Mortgage finance costs for individualsFinance-cost restriction did not applyResidential property finance-cost restriction generally applies
Capital allowancesAvailable on qualifying plant and machineryGenerally unavailable for new expenditure on items within the dwelling; replacement relief may apply
CGT business reliefsCertain trading-style CGT reliefs potentially availableSpecial FHL access removed
Pension reliefProfits could count as relevant UK earningsFormer FHL property income no longer receives this special treatment

HMRC confirms these changes in its updated Property Income Manual.

There are transitional rules for matters such as existing capital allowance pools and pre-abolition transactions, so hosts with a property that qualified as an FHL before April 2025 should not assume all historic relief simply disappeared retrospectively.

Does Airbnb Report UK Hosts to HMRC?

Digital platform reporting rules require qualifying platforms to collect and report information about sellers, including people letting short-term accommodation. The UK rules took effect from 1 January 2024, with the first reporting due from January 2025.

This is where one of the biggest pieces of misinformation around HMRC Airbnb tax UK arises.

The often-quoted exclusion for fewer than 30 transactions and no more than €2,000, approximately £1,700, applies to sales of goods. It is not a £1,700 Airbnb rental-income exemption. Property rentals are identified as a reportable platform activity.

Platform reporting also does not create a new tax. Whether tax is actually due still depends on the existing income tax rules, allowances, expenses and reliefs that apply to the host.

Hosts should therefore reconcile:

  • Airbnb booking and payout records
  • platform fees
  • cancellations and refunds
  • property expenses
  • amounts already reported to HMRC

Where HMRC receives platform information that does not match a tax return, the discrepancy can create an obvious compliance risk.

When Does Making Tax Digital Apply to Airbnb Hosts?

Making Tax Digital for Income Tax can apply to individual landlords with Airbnb property income when their combined qualifying self-employment and property income exceeds the relevant threshold.

The first mandatory phase began on 6 April 2026.

Tax Return Used to Test IncomeQualifying IncomeMTD Start Date
2024/25More than £50,0006 April 2026
2025/26More than £30,0006 April 2027
2026/27More than £20,0006 April 2028

Those brought into MTD must maintain qualifying digital records and use compatible software. For the first 2026/27 MTD year, HMRC lists quarterly update deadlines of 7 August 2026, 7 November 2026, 7 February 2027 and 7 May 2027, followed by the 2026/27 tax return deadline of 31 January 2028.

Hosts approaching the thresholds can read Apex’s Making Tax Digital for Income Tax 2026 guide before changing their bookkeeping process.

Do Airbnb Hosts Have to Register for VAT?

Holiday accommodation is generally a standard-rated supply for VAT purposes. However, an individual host does not automatically have to register for VAT simply because they list a property on Airbnb.

The compulsory VAT registration threshold is currently £90,000 of taxable turnover, measured using the relevant rolling 12-month or forward-looking registration tests. The threshold concerns the taxable turnover of the VAT person, so other taxable business activities may also need to be considered rather than looking at the Airbnb listing in isolation.

Hosts close to £90,000 should review their VAT position before crossing the threshold, particularly because adding VAT after prices and bookings have already been set can affect margins.

What Tax Applies When You Sell an Airbnb Property?

An individual selling an Airbnb investment property may face capital gains tax on any taxable gain that is not covered by available reliefs or exemptions.

For disposals from 6 April 2026, the main individual CGT rates are 18% and 24%, depending on the taxpayer’s circumstances. The individual annual exempt amount for 2026/27 is £3,000.

If CGT is due on a UK residential property disposal, it normally has to be reported and paid within 60 days of completion. A taxpayer already within Self Assessment may also need to include the disposal in the relevant tax return.

Private Residence Relief may change the calculation where the property has genuinely been the owner’s home. Former FHL owners should also remember that the special FHL treatment giving access to certain business CGT reliefs ended from 6 April 2025.

Our Capital Gains Tax services can help where a short-term rental property is being sold, transferred or restructured.

How Can You Reduce Airbnb Tax Legally in the UK?

Searches for “how to avoid Airbnb tax UK” often describe what is really a tax-planning question. The lawful objective is to claim the reliefs and deductions Parliament allows while reporting all taxable income correctly.

Depending on the facts, sensible planning can include:

  • comparing the £1,000 property allowance with actual deductible expenditure
  • checking whether Rent a Room relief applies to accommodation in your main home
  • keeping evidence for all allowable expenses
  • claiming Replacement of Domestic Items Relief where the statutory conditions are met
  • carrying forward eligible unused residential finance costs where HMRC’s tax-reducer calculation restricts relief
  • reviewing ownership and profit allocation before, rather than after, income arises
  • forecasting VAT and MTD thresholds before they are crossed

For spouses and civil partners, another post-FHL change deserves attention. Income from jointly held property is generally treated as arising equally between them unless the underlying beneficial ownership is unequal and the conditions for notifying HMRC, including Form 17, are satisfied. HMRC says the declaration must be submitted within 60 days.

Changing ownership purely for tax purposes can have wider tax, mortgage, legal and succession consequences. It should therefore be modelled before any transfer is made.

What Changes to Airbnb Tax From 6 April 2027?

A confirmed change takes effect from 6 April 2027: separate rates of income tax will apply to property income in England, Wales and Northern Ireland.

For 2027/28, the property rates are set at:

  • 22% property basic rate
  • 42% property higher rate
  • 47% property additional rate

The government has also confirmed that the residential property finance cost tax reduction will move to the 22% property basic rate.

This change does not alter the current 2026/27 calculation. It does, however, mean Airbnb hosts planning pricing, borrowing or portfolio decisions for 2027/28 should model the higher property-specific rates rather than assuming today’s 20%, 40% and 45% structure will continue.

FAQs About Airbnb Tax UK

What Is the 15% Host Fee on Airbnb?

The so-called 15% Airbnb host fee is a platform service charge, not a UK tax. Airbnb’s 2026 UK material describes its move to a single host-paid service fee of 15.5%, replacing the previous split-fee model for affected hosts.

Hosts should check their own Airbnb account for the fee applying to their listings. For tax purposes, business-related platform charges should be considered alongside the normal property expense rules.

What Are the New Tax Rules for Airbnb Rent a Room?

There is no separate new Airbnb-specific Rent a Room exemption for 2026/27. The normal scheme continues to provide a £7,500 annual threshold, generally reduced to £3,750 where another person receives income from letting accommodation in the same residence.

The accommodation must form part of the taxpayer’s only or main residence and meet the other Rent a Room conditions.

What Does the 80/20 Rule Mean for Airbnb?

There is no HMRC rule called the 80/20 rule — in hosting circles it is a revenue observation, not a tax provision: roughly 80% of a property’s income typically comes from about 20% of its booking dates, usually peak weekends and holidays. The tax angle is twofold. First, concentrated peak income means your profits arrive in bursts, so set cash aside for the following 31 January. Second, it is a useful record-keeping prompt: a small number of peak bookings determine most of your tax, which makes reconciling your platform statements against your declared income quick work.

Is There a £1,700 Airbnb Tax Exemption?

No. The approximately £1,700 or €2,000 figure associated with digital platform reporting is an exclusion connected with occasional sales of goods, alongside a fewer-than-30-sales condition. It is not an Airbnb property-income tax exemption.

For an individual Airbnb landlord, the relevant tax relief may instead be the £1,000 property allowance or, where the conditions are satisfied, Rent a Room relief.

Can I Use the £1,000 Property Allowance and Claim Mortgage Interest Relief?

Generally, no. HMRC states that the property allowance cannot be used where the taxpayer claims the residential property finance-cost tax reduction.

Hosts with mortgage borrowing should therefore compare the result under actual property expenses and finance-cost relief with the simpler £1,000 allowance before choosing a method.

Do you pay National Insurance on Airbnb income?

Usually not. Letting property is investment income rather than a trade, so Class 2 and Class 4 National Insurance contributions do not apply. That position can change where a host provides substantial hotel-like services — daily servicing, meals, concierge arrangements — to the point the activity is really a business, but ordinary self-catering Airbnb lettings stay outside NIC.

When do you have to pay tax on Airbnb income?

Under Self Assessment, the tax on your letting profit for a tax year is due by 31 January following the tax year end, alongside any payments on account. Two separate deadlines sit outside that cycle: Capital gains tax on a sold let property is due within 60 days of completion, and from April 2026 Making Tax Digital quarterly updates apply once qualifying income exceeds £50,000. Penalties for late filing and late payment apply to each deadline separately.

Do you need an accountant for Airbnb income?

For a single room under Rent-a-Room’s £7,500 limit, almost certainly not. Beyond that, the cases where advice pays for itself are easy to list: choosing between allowances, the post-FHL transition, mortgage interest credit calculations at higher rates, 60-day CGT filings on a sale, and Making Tax Digital registration and software setup from April 2026. A fixed-fee adviser who has seen the platform’s data before HMRC does is considerably cheaper than a penalty.

How Can Apex Accountants Help Airbnb Hosts?

Airbnb tax now sits at the intersection of ordinary property taxation, digital platform reporting, Making Tax Digital and, for larger operators, VAT. The abolition of the Furnished Holiday Lettings regime has also changed the calculation for many established short-term rental owners.

Apex Accountants can help you review rental profits, allowable expenditure, mortgage finance cost relief, MTD, VAT and capital gains tax as one connected tax position rather than addressing each issue separately.

For hosts unsure whether their current reporting or structure is still appropriate, a tax review is the sensible next step.

Accountant for Community Pharmacy UK: VAT and Tax Guide

A pharmacy can look profitable on paper while still facing tight cash flow. NHS income, retail sales, dispensing margins, staff costs, stock movements and VAT liabilities can be recognised at different times and require different accounting treatment.

That is why an accountant for community pharmacy UK businesses rely on should understand how a pharmacy operates, not simply submit a year-end return. The immediate priorities are usually accurate community pharmacy VAT treatment, reliable branch-level reporting, payroll control, stock accounting, pharmacy bookkeeping and tax planning that reflects how the business actually trades.

Key takeaways

  • Community pharmacies can make a mixture of zero-rated, exempt, standard-rated and, in some cases, outside-the-scope supplies. The VAT treatment depends on the underlying goods or services and the relevant conditions.
  • HMRC’s VAT Notice 701/57 and VAT Health manual explain important rules for pharmacists and dispensed medicines.
  • England’s 2026–27 Community Pharmacy Contractual Framework provides total funding of £3.636 billion. This is sector funding, not a guaranteed amount for an individual pharmacy.
  • Good pharmacy bookkeeping should reconcile NHS remittances, dispensing data, retail tills, stock, payroll and supplier statements.
  • A specialist review can be particularly useful before a VAT compliance check, acquisition, restructuring or major funding change.

Why does a community pharmacy need specialist accounting support?

A community pharmacy has several revenue streams and cost patterns that can make generic small-business bookkeeping unreliable. NHS dispensing, private prescriptions, over-the-counter medicines, consultations, vaccinations, delivery charges and retail products do not necessarily share the same VAT treatment.

The accounts also need to explain operational performance. A single sales total can hide weak margins in one branch, stock losses, rising locum costs or a funding payment posted to the wrong accounting period.

A specialist pharmacy tax accountant should connect the bookkeeping to practical decisions, including:

  • branch profitability and cash generation;
  • staffing, locum and overtime costs;
  • stock movements, expiries and gross margins;
  • acquisition funding and deal structure; and
  • owner salary, dividend and pension decisions.

Apex’s healthcare sector accountants can support pharmacy owners who need accounting, payroll, VAT and tax advice to work together rather than sit in separate files.

How does VAT work for a UK community pharmacy?

VAT treatment in a pharmacy is transaction-specific. It is not safe to assume that every medicine is zero-rated, every clinical service is exempt or every NHS-related payment has one automatic VAT outcome.

HMRC’s VAT Notice 701/57 explains the VAT treatment of goods and services provided by registered health professionals, including pharmacists. It also covers VAT recovery for VAT-registered health professionals and the rules applying to pharmaceutical goods.

HMRC’s VAT Health guidance on dispensing by a pharmacist confirms that most dispensing in a traditional community pharmacy is zero-rated where the relevant statutory conditions or NHS prescription concessions are met. The precise facts still need to be checked.

Pharmacy activityWhy the VAT treatment needs checking
Qualifying prescription dispensingZero-rating can apply when the relevant conditions are met.
Over-the-counter medicines and toiletriesMany retail supplies are standard-rated, while some products can have a different treatment.
Vaccination or other clinical servicesExemption can apply to qualifying medical care, but not every service is automatically exempt.
NHS or commissioner-funded servicesThe underlying supply, contractual terms and payment must be considered together.
Management or administration chargesThese can have a different liability from the medicines or care element.
Purchases and overheadsInput VAT recovery can be restricted where costs relate to exempt or non-business activities.

The legislation underpinning zero-rating includes Schedule 8 to the Value Added Tax Act 1994. HMRC guidance should be read alongside the legislation and the facts of each transaction.

A specialist VAT review can test till setup, product coding, invoice wording, NHS remittance entries and partial-exemption calculations. For a pharmacy with mixed activities, a periodic community pharmacy VAT review can also confirm that output VAT and input VAT recovery remain consistent with current trading.

What changed for NHS pharmacy funding in 2026–27?

For England, the Community Pharmacy Contractual Framework for 2026 to 2027 states that total funding will be £3.636 billion, representing a 10.3% increase compared with 2025–26. GOV.UK also confirms an agreement not to recover up to £239 million of historic over-paid funding from the sector.

These are national NHS pharmacy funding figures for England. They do not predict a particular pharmacy’s income, profit or cash receipts. An individual pharmacy’s position depends on its services, dispensing volume, reimbursement, clawbacks, staffing and other costs.

The framework also covers independent prescribing, the Pharmacy Quality Scheme and regulatory changes. These developments can create accounting questions around the timing, classification and evidence for income and expenditure.

A pharmacy should therefore reconcile each service or activity to:

  1. the remittance or payment received;
  2. the accounting period to which it relates; and
  3. any deduction, adjustment, clawback or repayment.

This provides a stronger basis for cash-flow forecasting and for answering questions from HMRC, lenders or a potential buyer. As NHS pharmacy funding arrangements change, the records should distinguish recurring, activity-based, one-off and adjustable income.

Which records should a pharmacy accountant review every month?

Monthly reporting should show what is happening before the annual accounts deadline. At a minimum, the review should cover bank reconciliations, supplier balances, payroll, VAT control accounts, stock and NHS or commissioner remittances.

Useful monthly controls include:

  • comparing dispensing and retail revenue with the till and pharmacy system;
  • reconciling NHS payments to claims or remittance statements;
  • reviewing negative or unusually high gross margins;
  • checking stock purchases, write-offs, expiries and shrinkage;
  • separating owner drawings, wages, dividends and business expenses;
  • checking locum invoices and employment-status treatment where necessary; and
  • reviewing aged creditors before supplier pressure affects cash flow.

For multi-branch operators, management accounts should show branch-level sales, gross margin, payroll, occupancy, locum costs and contribution. Strong pharmacy bookkeeping should create a reliable link between operational activity, cash movements and management reporting.

Apex’s accounting services can be combined with pharmacy-specific controls to produce management information that supports decisions as well as compliance.

How should pharmacy owners approach corporation tax and payroll?

A limited company pharmacy normally needs statutory accounts and a Company Tax Return, with corporation tax calculated from adjusted taxable profits. Taxable profit can differ from management profit because of capital allowances, disallowable expenses, timing rules and other tax adjustments.

For pharmacy corporation tax planning, owners should look beyond the year-end liability. Equipment investment, acquisition costs, remuneration decisions and the timing of significant expenditure can affect both tax and cash flow.

The company should also keep payroll and dividends distinct. Salary and employer costs run through payroll, while dividends must be supported by available profits and appropriate company records. Treating every payment to an owner as a dividend can create tax and accounting problems.

Pharmacy employers should review PAYE, pension duties, holiday pay, overtime, locum arrangements and benefits. Staff costs are often one of the largest controllable expenses, so errors can affect both compliance and profitability.

Where a pharmacy is buying another branch or company, advice should begin before the deal is agreed. The review may cover stock valuation, goodwill, fixtures, property, debt, VAT history, employees and the structure of the purchase.

A specialist corporation tax adviser can model these consequences, especially where pharmacy corporation tax planning overlaps with an acquisition, restructuring or change in ownership.

What is a simple pharmacy VAT error example?

Suppose a pharmacy codes every sale as standard-rated because it sells both retail goods and prescription medicines. This could overstate output VAT on qualifying zero-rated supplies. The opposite error is also possible if zero-rating is applied to goods or services that do not meet the relevant conditions.

The pharmacy would need to identify the affected transactions, inspect the supporting records, check the applicable HMRC guidance and determine whether previously submitted VAT returns need correcting.

Real pharmacies can also have mixed supplies, NHS payments, private work and shared overheads, so the correct treatment may require a broader review of VAT liability and input tax recovery.

Do community pharmacies need a VAT partial-exemption review?

They may. Partial exemption can become relevant when a VAT-registered pharmacy makes both taxable and exempt supplies and incurs VAT on costs relating to those activities.

A pharmacy should not assume that every amount of input VAT is recoverable simply because the business is VAT-registered. It should document the link between costs and supplies, apply the appropriate method and retain evidence supporting the figures reported.

How can a pharmacy prepare for an HMRC VAT compliance check?

Start with a clean audit trail. HMRC should be able to follow a sample transaction from the till, dispensing system or service contract through the ledger, VAT code, VAT return and bank or remittance reconciliation.

Before a compliance check, review:

  • VAT registration details and return periods;
  • product and service VAT codes;
  • NHS and commissioner remittances;
  • private prescription and retail sales;
  • input VAT on stock, rent, equipment and professional costs;
  • partial-exemption calculations, where relevant; and
  • prior corrections, disclosures and correspondence.

If an error is identified, quantify it, preserve the working papers and obtain advice on the correct amendment or disclosure route.

Frequently Asked Questions

Is a pharmacy accountant more expensive than a general accountant?

Fees depend on branch count, transaction volume, payroll, VAT complexity and the level of reporting required. Specialist work can cost more than basic compliance, but it may also identify recurring VAT, stock or payroll errors.

Can a pharmacy accountant help with buying another pharmacy?

Yes. An accountant can assess management accounts, stock, goodwill, VAT history, payroll, funding, cash flow and the tax effects of different deal structures. Advice is most useful before heads of terms or a purchase agreement is finalised.

Does NHS pharmacy income automatically have no VAT?

No. The VAT treatment depends on the underlying supply, the relevant conditions and how the payment relates to the goods or service. NHS dispensing income and other service funding should be analysed rather than placed into one automatic VAT category.

What happens if a pharmacy has used the wrong VAT code?

The business should identify the affected transactions, calculate the net error and check whether previously submitted VAT returns need correcting. The underlying coding should also be fixed so the problem does not continue.

What does a pharmacy accountant need from the owner?

Usually, the accountant needs sales and dispensing reports, NHS remittances, bank feeds, supplier statements, stock information, payroll data, VAT returns and details of unusual transactions.

Can Apex support a pharmacy outside England?

Apex can provide UK accounting, tax, payroll and VAT support, but the England-specific funding reference in this article should not be assumed to apply in the same way across Scotland, Wales or Northern Ireland. The relevant devolved arrangements and contracts should be checked for the pharmacy’s location.

Apex Accountants’ View

Community pharmacy owners need financial information that reflects how the business actually operates. A year-end profit figure cannot show whether a branch is losing margin through stock expiry, whether locum spending is rising or whether an NHS payment has been posted to the wrong period.

At Apex, we advise UK businesses on bookkeeping, VAT, payroll, corporation tax and management reporting. For pharmacies, that means connecting the ledger to dispensing activity, retail sales, remittances, stock and staff costs. A specialist pharmacy tax accountant should help maintain defensible records while making cash flow, margins and profitability easier to understand.

Apex Accountants has supported UK businesses since 2006. The sensible starting point is a review of current records, VAT treatment and reporting needs so the accounting process reflects the pharmacy’s services, funding arrangements and growth plans.

Are Inter-Company Loans Putting Your Family Business at Risk with HMRC

Inter-company lending has long been a practical solution for family-run businesses and owner-managed groups. These arrangements often support short-term funding, manage group cash flow, and facilitate internal investment. However, recent inter-company loans HMRC UK reviews have placed such transactions under increased scrutiny. HMRC is increasingly questioning whether such loans represent genuine commercial activity—or are being used to shift profits or obtain unintended tax advantages. With recent tax tribunal decisions and due to tightening legislation, companies can no longer afford to take a casual approach. At Apex Accountants, we recommend a thorough review of how inter-company loans are structured, recorded, and taxed within the framework of group company tax legislation.

Why Is HMRC Challenging Intercompany Loans?

Family-controlled companies frequently transfer funds between group entities to support trading operations or balance liquidity. But HMRC is questioning whether businesses are using these loans for genuine commercial purposes or to artificially generate tax benefits.

The issue lies in how these loans are treated for tax purposes—particularly when it comes to impairments, write-offs, and whether interest is deductible. These concerns are especially relevant for companies under common ownership, where one entity funds another within a closely held group. Inter-company loans tax implications UK guidance stresses that all such transactions must follow commercial logic to withstand review.

What Counts as “Connected” Under the Rules?

For corporation tax, “connected” companies have a defined meaning. CTA 2009 defines two entities as connected if:

  • One company controls the other directly or through a chain of ownership, or
  • Both companies are under the control of the same individual or individuals.

Unlike other tax definitions, this form of control does not include family attribution. For example, if a parent owns one company and their adult child owns another, HMRC may not treat them as connected under intercompany loan rules—unless both share control or make joint decisions.

This distinction is critical in deciding whether connected companies tax rules apply.

Tax-Neutral Write-Offs: Not Always So Simple

There’s a common assumption that loans between connected entities are automatically tax-neutral when forgiven. In simple terms, this would mean:

  • The lender cannot claim a tax deduction for writing off the loan.
  • The borrower is not taxed on the release of the debt.

However, this treatment only applies when the loan meets specific conditions:

  1. The loan must qualify as a “money debt”—you must expect repayment in cash.
  2. You must create the loan by actually lending funds, not by accumulating unpaid charges, goods, or services.

If either of these isn’t true, tax neutrality breaks down. The borrower may be taxed on the waived amount, and the lender might be denied relief. These consequences are a direct result of inter-company loans HMRC rules designed to prevent abuse.

The Risk of “Unallowable Purpose”

The unallowable purpose rule (CTA 2009, sections 441–442) enables HMRC to block tax deductions on interest or related expenses if the loan arrangement was motivated—even in part—by the intention of obtaining a tax advantage.

This test doesn’t just focus on individual transactions. Tribunals now consider the broader group context and commercial reasoning. Even if a loan had an operational use, if tax saving was a significant reason for the setup, deductions may be disallowed.

In the BlackRock and Kwik-Fit cases, HMRC successfully challenged intragroup lending where interest deductions were claimed while the underlying purpose appeared to be tax-driven rather than operational.

If you are relying on loans between HMRC connected companies, ensure they are not vulnerable under the unallowable purpose rule.

Loan Write-Offs in Family-Owned Structures

Where a company writes off a loan to another under the same individual’s control but not within a formal corporate group, tax consequences can arise. In such cases:

  • If the companies are part of a 100% UK group, a loan write-off is typically treated as tax-neutral and ignored for corporation tax.
  • If not grouped, the waived loan may be considered a distribution to the shareholder in control.

Imagine Mr Ali owns both Company X and Company Y. If X writes off £15,000 lent to Y, and the companies are not in a group, HMRC may treat the deduction as if Mr Ali received a dividend personally. That could result in a personal tax bill at dividend rates—up to 39.35%—depending on his income level.

Where the corporation tax treatment of a write-off or related-company transaction is unclear, our corporation tax advisory services can help assess the position before the balance is released. 

This kind of scenario is increasingly being picked up under connected companies tax rules, especially when the loan wasn’t commercial or supported by proper agreements.

Director Loans: Beware of Sections 455 and 459

Section 455 CTA 2010 can apply where a close company lends money to a participator, typically a shareholder, or an associate of a participator. If the loan remains outstanding more than nine months after the end of the company’s corporation tax accounting period, the company may have to pay a Section 455 tax charge on the outstanding amount.

For loans made or benefits conferred on or after 6 April 2026, the Section 455 tax rate is 35.75%. The charge can generally be reclaimed after the loan is permanently repaid, although specific rules and time limits apply. HMRC’s director’s loans guidance also explains how loans to directors and shareholders are treated for tax and reporting purposes. 

Section 459 can also apply to certain indirect loan arrangements. For example:

  • Company A makes a loan to Company B.
  • As part of the same arrangements, Company B then provides funds or another benefit to a participator in Company A.

Where the statutory conditions are met, the arrangement can be treated as a loan to the participator for Section 455 purposes. This prevents close companies from avoiding the rules simply by routing funds through another person or company.s.

Impairment Losses and Accounting Standards

Under FRS 102 or IAS 39, businesses may recognise a reduction in the value of loans made to group companies. But if the loan is between connected companies, tax relief on the impairment is generally denied.

This restriction exists to stop groups from claiming relief twice—for example, once on a trading loss in the debtor company and again via an impairment in the creditor’s accounts.

Companies using fair value accounting for such loans must also switch to the amortised cost method for taxes. When the borrower and lender have a connection, this prevents volatile accounting valuations from affecting tax positions.

VAT Implications for Intercompany Charges

In the Tower Resources case, HMRC argued that management charges added to inter-company loan balances did not constitute VATable supplies, but the tribunal rejected this view.

Key lessons:

  • Providing services to another company, even within a group, counts as a supply for VAT if consideration exists.
  • Even if payment is deferred and recorded as a loan, output VAT may still be due.
  • Input VAT can be recovered, assuming the services are for a taxable business activity.

For many businesses operating within related company structures, intercompany recharges should be carefully reviewed for VAT compliance.

Before forgiving any inter-company loan:

  • Check distributable reserves. If the lender lacks sufficient reserves to write off the debt, the action could be deemed an unlawful distribution.
  • Document intentions properly. If you never intended to repay the loan, it may not qualify as “money debt,” which removes the tax-neutral treatment.
  • Use formal agreements and security where appropriate. With HMRC scrutiny increasing, well-structured documents can help prove business intent.

Common Pitfalls with Inter-Company Loans HMRC UK

  • Lack of Documentation
    No formal loan agreements, undefined repayment terms, or missing board resolutions. Proper records are particularly important when dealing with inter-company loans HMRC UK scrutiny.
  • Missing Reporting Requirements
    Loans made by a close company to participators may need to be disclosed with the company’s Corporation Tax return under the relevant Corporation Tax reporting for loans to participators requirements, so these balances should be identified and reported correctly.
  • Misunderstanding ‘Control’
    Assuming companies are connected due to family ownership, even when control criteria are not legally met.
  • Incorrect Accounting Treatment
    The application of fair value, rather than amortised cost, is crucial for tax compliance.
  • Unallowable Purpose
    Loans are primarily structured for tax benefits rather than commercial reasons.
  • Ignoring Distribution Rules
    Writing off balances without having sufficient reserves can lead to unlawful distributions and tax charges.

Summary: What You Need to Know About Inter-Company Loans Tax Implications UK

  •  Not all loans between companies are automatically tax-neutral.
  •  The unallowable purpose test can block deductions even when loans look legitimate.
  •  Section 455 can apply even if director loans are routed through other companies.
  • Inter-company recharges may still attract VAT liabilities.
  •  Always follow HMRC rules on intercompany loans to prevent costly penalties.

Expert Support from Apex Accountants

Our team provides hands-on support for family businesses and group structures dealing with complex lending arrangements. Whether you’re looking for help managing tax risks in line with inter-company loans, preparing clear documentation, or reviewing historic balances, we’re here to help. 

From writing off group balances to navigating VAT and corporation tax, our expert advisors and tailored tax planning for family companies help keep your business compliant, tax-efficient, and well-prepared for HMRC scrutiny. If you would like professional advice on your current arrangements, you can contact Apex Accountants to discuss your position. 

Frequently Asked Questions 

What is Section 455 tax, and when does it apply to close company loans?

Under Section 455 of the Corporation Tax Act 2010, if a close company makes a loan to a director or shareholder (participator) that remains unpaid 9 months and 1 day after the accounting period end, the company must pay a 35.75% tax charge to HMRC. This tax is temporary and refundable once the loan is fully repaid, released or written off. 

What are HMRC’s ‘bed and breakfasting’ rules for loan repayments? 

Under Sections 464A–464D CTA 2010, HMRC prevents taxpayers from temporarily repaying a loan just before the 9‑month deadline and immediately reborrowing funds. If £5,000 or more is repaid and reborrowed within 30 days (or where there are arrangements to re‑borrow on larger loans), the repayment is matched against the new borrowing and Section 455 tax remains due. 

How should family companies structure inter-company loans to remain compliant?

Family businesses must execute formal loan agreements specifying commercial terms, repayment schedules, and market‑rate interest. For loans between connected companies, transfer pricing rules under TIOPA 2010 may apply if terms are non‑arm’s length. Maintaining clean director loan account (DLA) ledgers and professional accounting oversight prevents unexpected HMRC enquiries. 

 What happens if a director loan is written off by a family company?

If a family company writes off or releases a loan to a director‑shareholder, the written‑off amount is treated as a dividend distribution for income tax purposes under Section 415 ITTOIA 2005. The individual must report it on their self-assessment tax return and pay dividend tax; Class 1 National Insurance contributions do not normally arise on such distributions.

Understanding the Tax Implications for SPV for Properties in the UK

In the UK property market, many investors now use Special Purpose Vehicles (SPVs) to buy, hold, or develop real estate. These limited companies help separate financial risks, improve transparency, and create a structured way to manage property investments. However, operating through an SPV also introduces specific tax implications for SPV for properties that every investor should understand.

At Apex Accountants, we specialise in advising landlords, developers, and investors on how property SPVs are taxed in the UK. Our experts provide guidance on company formation, ongoing compliance, and profit extraction to help clients make informed and tax-efficient decisions.

This article explains what a property SPV is, how it is taxed, and the key financial and legal implications to consider—from corporation tax and SDLT to profit withdrawals and HMRC anti-avoidance rules.

What Is a Property SPV, and Why Use One?

A property Special Purpose Vehicle (SPV) is a limited company created to own, hold, or develop real estate. It keeps financial and legal risks separate from the owner’s other activities. Many landlords and developers form one SPV per property or project to simplify ownership and improve accountability.

SPVs are common in buy-to-let and development projects because they make it easier to track income and expenses, attract funding, and ring-fence liabilities. Lenders also prefer this structure because it provides a clear picture of project-level performance.

How Property SPVs Are Taxed in the UK

Property SPVs are treated like any other limited company for UK tax purposes. They must pay corporation tax on profits, register for VAT if applicable, and operate PAYE if salaries are paid to directors or employees.

Corporation Tax

Corporate tax for SPV for properties applies to all net profits, including rental income and capital gains from sales. The main rate is 25% for profits over £250,000, with a small profits rate of 19% below £50,000. Companies earning between these limits pay a marginal rate.

Interest and Deductible Expenses

Interest on loans used to purchase or develop property is generally tax-deductible for SPVs. This offers an advantage over personal property ownership, where mortgage interest relief is restricted. Other deductible expenses include maintenance, insurance, letting fees, and professional services.

Capital Gains on Property Sales

When an SPV sells property, the gain is added to company profits and taxed under corporation tax. Unlike individuals, companies cannot use the capital gains tax annual exemption. The gain is calculated by deducting the purchase price and allowable costs from the sale proceeds.

Stamp Duty Land Tax (SDLT)

SPVs must pay SDLT on property purchases at the same rates as individuals. For residential property, the higher 3% surcharge applies if the company owns multiple properties. For commercial property, rates are lower and depend on value thresholds.

Buying shares in an SPV that owns property usually attracts only 0.5% stamp duty on the share transfer rather than SDLT on the property’s value, though the exact amount depends on transaction structure and HMRC rules.

Can You Transfer Existing Property into an SPV?

Yes, but doing so creates a taxable event. Transferring personally owned property into an SPV is treated as a sale. This triggers two taxes: Capital Gains Tax on the increase in value since purchase and Stamp Duty Land Tax on the SPV’s acquisition price.

These costs often outweigh benefits for single properties. However, for landlords planning long-term growth or multiple acquisitions, using an SPV can provide long-term efficiency, especially when borrowing or attracting investors.

How Are Profits Taken Out of a Property SPV?

Company profits can be distributed to shareholders or directors through salaries or dividends.

Salary or bonus payments are deductible for corporation tax but subject to PAYE and National Insurance. Dividends are paid from post-tax profits. Dividend tax rates are 8.75% for basic rate, 33.75% for higher rate, and 39.35% for additional rate taxpayers.

Combining a small salary with dividends is often the most efficient approach, balancing income tax and corporation tax exposure. Apex Accountants advises on the best mix for each situation and provides specialist insight into corporate tax for SPVs for properties to optimise withdrawals.

What Happens When You Sell or Wind Up an SPV?

When a property SPV is sold or wound up, different tax implications arise depending on the transaction.

Selling Property from the SPV

If the SPV sells a property, the gain is taxed at the corporation tax rate. Any retained profit can later be distributed to shareholders as dividends or capital during liquidation.

Selling the SPV Itself

Selling shares in the SPV can be more tax-efficient. The buyer acquires the company rather than the property, potentially saving SDLT. The seller pays capital gains tax on the share sale rather than corporation tax on property disposal.

Winding Up the SPV

Upon winding up the company, shareholders may qualify for capital treatment instead of income tax on any remaining funds. This means gains are taxed under Capital Gains Tax rather than dividend rates.

If the SPV qualifies for Business Asset Disposal Relief (BADR), gains can be taxed at 10% up to a lifetime limit of £1 million. However, BADR applies mainly to trading companies, and most property SPVs are considered investment vehicles. This means BADR may not apply unless the company was actively developing or trading property.

What Are the Anti-Avoidance Rules for SPVs?

HMRC applies strict anti-avoidance legislation to prevent taxpayers from converting income into capital or using repeated liquidations for tax benefits.

Targeted Anti-Avoidance Rule (TAAR)

This rule applies when a company is wound up, and a new company is formed to continue similar business activities. If the main purpose was to gain a tax advantage, HMRC may reclassify capital distributions as dividends.

Transactions in Securities (TiS) Rules

These rules apply when share transactions are structured to avoid income tax. HMRC can reclassify such transactions as income where tax motivation is suspected. Advance clearance can be requested to confirm commercial intent.

What Are the Benefits and Risks of Using a Property SPV?

Benefits

  • Lower corporation tax rates compared with personal income tax
  •  Mortgage interest remains deductible
  •  Easier to separate liabilities between projects
  •  Flexible ownership for joint ventures or investor participation
  •  Retained profits can be reinvested in new properties.

Risks

  • Initial and ongoing administrative costs, including accounting and filing
  • Limited mortgage products and potentially higher interest rates
  • Possible double taxation when extracting profits
  • HMRC scrutiny of liquidation or restructuring for tax avoidance

SPV Tax Planning in the UK Property Market

Effective SPV tax planning helps investors stay compliant and efficient. Best practices include maintaining clear records for each property, documenting commercial reasons for every transaction, and reviewing financing arrangements for deductibility.

Apex Accountants provides detailed advice on property SPV formation, ongoing tax compliance, and exit strategies. Our specialists review corporation tax, VAT, PAYE, and capital treatment to help clients make informed and compliant decisions.

Key Takeaways

  • Property SPVs are limited companies used to hold or develop property.
  • They pay corporation tax on profits and capital gains.
  • SDLT applies to property purchases, but share transfers may offer savings.
  • BADR rarely applies unless the SPV is trading rather than investing.
  • HMRC’s anti-avoidance rules may reclassify capital gains as income in certain cases.

Need Expert Advice on Tax Implications for SPV for Properties?

Managing property investments through an SPV requires strategic tax planning and consistent compliance. At Apex Accountants, our specialists provide end-to-end support for SPV formation, financial management, and exit planning.

We offer practical advice on how SPVs are taxed in the UK, helping you structure profits efficiently, reduce exposure to unnecessary tax, and stay fully compliant with HMRC regulations.

Whether you manage a single property or a large portfolio, our tailored guidance ensures your SPV remains financially secure and tax-efficient throughout its lifecycle.

Book your consultation today to discuss your property SPV with our experts and take the next step towards smarter, compliant, and profitable property investment.

Frequently Asked Questions

What is a Special Purpose Vehicle (SPV) for UK property?

An SPV is a standard UK private limited company formed specifically for holding, letting, or developing real estate assets. Lenders and HMRC treat SPVs as dedicated property vehicles, isolating financial risk from other business activities. Setting up an SPV allows landlords to deduct full mortgage interest as a business expense against rental income.

Does an SPV pay Stamp Duty Land Tax when buying property?

Yes, an SPV pays standard Stamp Duty Land Tax plus applicable higher rate surcharges for additional residential properties when acquiring UK real estate. Transferring existing personally owned property into an SPV also triggers SDLT and potential capital gains tax. A formal tax analysis is recommended before transferring existing portfolios.

How do I extract profits from a property SPV tax-efficiently?

Profits after corporation tax can be extracted as dividends, director salaries, or repayments of director loan accounts. If you funded the initial purchase via a personal loan to the company, loan repayments are returned tax-free. Tax-free pension contributions can also be made directly from the SPV on behalf of directors.

Is an SPV always better than personal landlord ownership?

Not always. SPVs are generally more tax-efficient for higher-rate taxpayers expanding portfolios due to full interest deduction and lower corporation tax rates. However, basic-rate taxpayers or those with small, single-property investments may incur higher administrative, accounting, and mortgage setup fees that outweigh the tax savings.

Expert Tax Services for Etsy Sellers in the UK

Selling on Etsy allows creative entrepreneurs to turn their talent into a thriving business. Yet managing tax obligations can quickly become challenging as your sales increase. From VAT registration to self-assessment returns, the financial side often feels more complex than creating your products. At Apex Accountants, we provide tailored tax services for Etsy sellers across the UK, helping you stay compliant while improving profitability. Our specialists handle bookkeeping, VAT for Etsy sellers UK, and year-end planning so you can focus on running your shop with confidence.

This article outlines the essential tax responsibilities for Etsy sellers, the expenses you can claim, and how professional accountants help keep your business compliant and profitable.

Do Etsy Sellers Need To Pay Tax In The UK?

Yes. Once your Etsy shop moves beyond a hobby and generates regular income, HMRC treats you as self-employed. You must report your profits each year through a self-assessment tax return. If you earn less than £1,000 annually from Etsy, you can use the trading allowance and skip filing. Once you go over that amount, you’ll need to declare and pay tax on your profit after expenses.

What Types Of Tax Affect Etsy Sellers?

Etsy sellers may face several different taxes, depending on how their business is set up.

  • Income Tax – paid on your profits after deducting allowable business expenses.
  • National Insurance (NI) – Class 4 NI applies when profits exceed £12,570, while Class 2 NI was scrapped in 2024.
  • VAT (Value Added Tax) – required when turnover passes £90,000 in any 12-month period.
  • Corporation Tax – applies if you operate through a limited company.
    Each tax has its own rules and deadlines, which can quickly become confusing without the right support.

Each tax has its own rules and deadlines, which can quickly become confusing without the right support from experienced tax accountants for Etsy sellers.

When Should An Etsy Business Register For VAT?

You’ll need to register for VAT once your taxable sales exceed £90,000 within 12 months. Registration means you must charge VAT on eligible sales and submit VAT returns digitally under the Making Tax Digital (MTD) rules. Even smaller Etsy sellers sometimes register voluntarily if their supply costs include significant VAT, as it allows them to reclaim that tax on purchases.

Professional guidance on VAT for Etsy sellers UK helps you understand which sales are taxable, how to record digital transactions, and when to reclaim VAT efficiently.

What Expenses Can Etsy Sellers Claim?

Etsy sellers can deduct many business costs before calculating taxable profit. Common examples include:

  • Etsy listing, transaction and processing fees
  • Raw materials and packaging
  • Tools and equipment for making goods
  • Website, internet and software costs
  • Marketing and photography expenses
  • Postage, delivery and shipping
  • Home-office and energy use (if applicable)
  • Professional and accounting fees

Recording these expenses properly not only reduces your tax bill but also keeps your books accurate for HMRC.

How Can A Tax Advisor Help Etsy Businesses?

Working with specialist tax accountants for Etsy sellers can save time, stress and money. Tax professionals handle more than returns—they advise on business setup, pricing, and compliance strategies. They can help you:

  • Register for Self Assessment or VAT
  • Integrate Etsy data with cloud accounting tools
  • Submit digital VAT returns on time
  • Identify tax reliefs and allowances
  • Plan cash flow and forecast profits

A good tax advisor also ensures your business stays compliant with the latest HMRC updates and filing obligations.

What Accounting Software Suits Etsy Sellers Best?

Cloud accounting has become a must-have for online businesses. Platforms like Xero, paired with tools such as Link My Books, automatically import Etsy transactions and match them with bank records. This automation gives you real-time visibility of sales, VAT, and expenses—so you can focus on creating products instead of reconciling spreadsheets.

What Happens If Etsy Income Isn’t Declared?

Failing to report Etsy income can trigger penalties and backdated tax bills. HMRC cross-checks online marketplaces like Etsy, eBay and Shopify to find undeclared income. Honest and timely reporting protects your business reputation and avoids unnecessary investigations.

When Are Etsy Tax Deadlines In The UK?

  • 31 January – online self-assessment filing deadline
  • 31 October – paper tax return deadline
  • Quarterly VAT returns – depending on your VAT cycle
  • Nine months after year-end – Corporation Tax payment (for companies)

Missing a deadline leads to fines or interest charges, so digital bookkeeping helps you stay organised year-round.

How Can Etsy Sellers Reduce Their Tax Bill?

You can legally lower your tax bill through smart planning.

  • Track and record every business expense
  • Choose the best business structure for your income level
  • Use allowances, such as the trading and personal allowances
  • Plan purchases before the tax year ends to claim relief sooner
  • Get advice from qualified UK tax advisors

A proactive approach to tax planning means you keep more of what you earn without worrying about compliance.

Why Professional Etsy Tax Services Make A Difference

Selling on Etsy is creative work, but running the numbers is a professional task. With dedicated tax services, you get accurate reports, VAT support, and advice on pricing and profitability. Having experts manage your financial side means you can focus on growing your shop with confidence.

HMRC Digital Platform Rules & Etsy VAT Thresholds Explained

HMRC’s digital platform reporting rules mean online marketplaces such as Etsy may collect information about sellers and report qualifying seller income and transaction details to tax authorities. For Etsy businesses, this makes accurate sales records particularly important, as figures reported through the platform should be consistent with the information used in tax returns and business accounts.

It is important to distinguish digital platform reporting rules from VAT registration rules. Having your sales information reported to HMRC does not automatically mean that you owe tax or need to register for VAT. For sellers of goods, platform reporting generally does not apply where both fewer than 30 sales are made during the calendar year and no more than approximately £1,700 is received.

Key Etsy VAT Thresholds

  1. UK VAT Registration Threshold: UK-established Etsy businesses must normally register for VAT when their total taxable turnover exceeds £90,000 in a rolling 12-month period. Registration may also be required where the business expects taxable turnover to exceed £90,000 in the next 30 days alone.
  2. Platform Reporting Is Not a VAT Threshold: The digital platform reporting limits do not determine whether an Etsy seller must register for VAT. VAT liability is assessed separately according to taxable turnover and the applicable UK VAT rules.

Keeping Etsy transaction records reconciled with accounting records can help identify differences before returns are submitted. Working with a specialist accountant can also help businesses assess VAT registration requirements and maintain accurate records where marketplace sales data may be available to HMRC.

Simplify Your Finances with Apex Accountants’ Tax Services for Etsy Sellers

At Apex Accountants, we work with UK-based Etsy sellers who want reliable, compliant, and stress-free financial management. Our team combines accounting expertise with an understanding of eCommerce operations, making us the ideal partner for creative entrepreneurs. From bookkeeping and VAT registration to annual tax planning, we provide practical support that keeps your business profitable and compliant.

Contact Apex Accountants today to book your free consultation and get tailored tax advice for your Etsy shop.

Frequently Asked Questions

Q: What are the UK VAT registration thresholds for Etsy sellers, and how do marketplace rules apply?
A:
UK Etsy sellers must register for VAT if total taxable turnover exceeds £90,000 in any rolling 12-month period. Etsy may collect VAT on certain digital sales and low-value imported goods, but UK sellers remain responsible for VAT on domestic sales from UK stock.

Q: When do UK Etsy sellers need to register for EU One Stop Shop (OSS) VAT?
A:
UK sellers usually use Etsy’s IOSS arrangement for eligible EU imports valued at €150 or less. OSS mainly applies where sellers hold stock in the EU and make cross-border EU sales.

Q: What allowable business expenses can Etsy sellers deduct to lower their tax bill?
A:
Allowable costs can include Etsy fees, materials, packaging, postage, advertising, equipment, payment fees and software. Sellers can generally claim either actual expenses or the £1,000 Trading Allowance, not both.

Q: Do I need to report Etsy income if I already pay tax through a PAYE employment job?
A:
Yes. If gross Etsy and other self-employed income exceeds £1,000 in a tax year, you must normally register for Self Assessment and report your profit to HMRC.

Tax Codes: What Should You Put for Personal Allowances?

For UK employees, pensioners and employers asking, “What should I put for personal allowances?”, the answer depends on the person’s tax position rather than a figure chosen manually. For the 2026-2027 tax year, the standard Personal Allowance is £12,570, and many people with one job or pension will usually have a 1257L tax code. Employers should rely on HMRC information, a P45 or the starter checklist process when setting up PAYE.

A wrong allowance or tax code can affect take-home pay and create later corrections. For businesses, payroll mistakes can lead to employee queries, extra administration and inaccurate deductions.

Key Points

  • The standard Personal Allowance for 2026 to 2027 is £12,570.
  • The common 1257L tax code usually applies to people receiving the standard allowance.
  • Employers should not decide an employee’s allowance without HMRC information.
  • A P45 is normally the starting point when a worker changes jobs.
  • The starter checklist PAYE process applies when a new employee has no P45.
  • Higher earners may lose some or all of their Personal Allowance.

How Does the 1257L Tax Code Work?

The UK Personal Allowance remains fixed at £12,570 for the 2026 to 2027 tax year. The tax year runs from 6 April 2026 to 5 April 2027, and the allowance represents the amount of income an individual can receive before Income Tax becomes payable.

For payroll purposes, employees do not normally enter a cash allowance figure themselves. Instead, HMRC converts their circumstances into a tax code, which employers use through PAYE.

How HMRC Decides the Tax Code:

Personal Allowances are a central part of the PAYE system. They determine how much income is treated as tax-free before Income Tax is deducted from earnings.

The figure shown through payroll is usually reflected through a personal allowance tax code rather than a separate payment adjustment. HMRC considers factors such as employment income, taxable benefits, pension income and unpaid tax when calculating the correct code.

For most employees, the employer’s role is to apply the code provided by HMRC rather than calculate the allowance independently.

When to Use a P45 or Starter Checklist:

If an employee has one job, no taxable benefits, no additional income and no outstanding tax adjustments, the usual position is the standard 1257L tax code.

However, the correct answer depends on the form being completed:

  • When starting a job, provide details from your P45 where available.
  • If there is no P45, complete the starter checklist PAYE questions accurately.
  • Check HMRC records if your income or employment situation has changed.
  • Do not automatically select the highest allowance if you have other income sources.

A 1257L tax code generally means the person receives the standard Personal Allowance. The number represents the tax-free amount divided by ten, while the letter indicates the individual’s circumstances.

Which Situations Change a Tax Code:

For employers, the standard Personal Allowance translates into PAYE payroll thresholds of £242 per week and £1,048 per month during the 2026 to 2027 tax year.

Not every taxpayer receives the full allowance. HMRC can adjust tax codes because of:

  • Company benefits such as private medical insurance or a company car.
  • Untaxed income.
  • Previous underpaid tax.
  • More than one employment.
  • Pension income.

High earners are also affected. A personal allowance is reduced by £1 for every £2 of adjusted net income above £100,000 and can fall to zero once income reaches £125,140 or above.

Who Is Most Likely to Get the Wrong Code?

The issue commonly affects:

  • Employees joining a new employer.
  • Businesses processing payroll for new starters.
  • Directors receiving PAYE salary.
  • Workers with multiple jobs.
  • Pensioners with employment income.
  • Employees receiving taxable benefits.

The correct tax code becomes particularly important when someone’s circumstances change. A new job, second income source or benefit can alter the amount of tax-free income available.

Why Employers Should Not Guess the Allowance:

The main mistake businesses and employees make is treating personal allowance as a fixed choice rather than part of the wider PAYE system.

Someone completing a form may see a question about allowances and assume they should enter £12,570. In reality, payroll depends on the tax code issued for that individual.

A business should avoid manually changing allowances unless supported by HMRC guidance. Applying an incorrect code can result in employees paying the wrong amount of tax throughout the year.

Employees should regularly check their tax code through their HMRC account, especially after changing jobs, receiving benefits or starting pension income.

How to Check and Correct PAYE Details:

Payroll accuracy affects both compliance and employee trust. A wrong tax code can reduce or increase take-home pay incorrectly and may require later adjustments through PAYE.

For small businesses, payroll queries can create unnecessary administration. Directors also need to consider how salary, dividends, benefits and other income affect their overall tax position.

Keeping payroll records accurate and applying HMRC coding notices promptly helps prevent avoidable issues. Employees who change jobs or take on a second income should always confirm their personal allowance tax code is up to date before the next payroll run.

What Businesses Should Do

Employers should:

  • Use P45 details when available.
  • Ask new employees to complete the starter checklist where required.
  • Apply HMRC coding notices promptly.
  • Review unusual codes such as BR, 0T, K and emergency codes.
  • Update payroll records when employee circumstances change.
  • Encourage employees to review their HMRC tax details.

How Can Apex Accountants Help?

Apex Accountants supports businesses with PAYE, payroll and tax code matters by reviewing processes and identifying areas where errors may occur. Our team provides practical guidance to help employers maintain accurate payroll records and apply the correct tax treatment.

We can help with:

  • Reviewing PAYE tax codes and payroll calculations.
  • Checking starter checklist treatment for new employees.
  • Advising directors on salary, benefits and wider tax considerations.
  • Identifying potential payroll errors linked to incorrect tax codes.
  • Supporting businesses with HMRC-related payroll queries.

By combining payroll knowledge with wider tax expertise, Apex Accountants helps businesses manage their obligations with greater confidence and accuracy. Contact us and book your consultation with tax experts today.

Conclusion

For most people asking, “What should I put for personal allowances”, the starting point is the standard £12,570 Personal Allowance and the commonly used 1257L tax code. However, the correct position depends on HMRC information, employment circumstances and other sources of income. To review your PAYE position, contact Apex Accountants today.

FAQs

What should I put for personal allowances on a tax form?

Most people with one job and no adjustments will usually have the standard Personal Allowance of £12,570, but the correct answer depends on HMRC information.

What does a 1257L tax code mean?

A 1257L tax code usually means the taxpayer receives the standard Personal Allowance through PAYE.

Should employers choose an employee’s Personal Allowance?

No. Employers should use the tax code provided by HMRC or information from the starter checklist process.

Can my Personal Allowance be reduced?

Yes. It can be reduced because of high income, taxable benefits, unpaid tax or other income.

How can I check if my tax code is correct?

You can review your tax code through HMRC’s online Income Tax service and update any incorrect details.

Book a Free Consultation