Will IR35 Be Scrapped? The IR35 Changes and Replacement Pledge Explained

IR35 remains fully in force. The off-payroll rules still apply in full, and HMRC still expects a status determination for every engagement with a medium or large client. The IR35 changes in the news this month are a political pledge, not law: on 17 September 2026, Shadow Chancellor Andrew Griffith committed a future Conservative government to replacing IR35 outright. Nothing changes until legislation passes. The change that has already happened is quieter: since April 2026, the widened small-company definition has taken more end clients out of the off-payroll regime, shifting status decisions back to contractors’ own companies.

For a broader explanation of how the rules affect contractors and personal service companies, our off-payroll IR35 guide covers the practical tax, status and compliance considerations businesses should understand alongside the latest developments.

Key takeaways

  • IR35 still applies in full today. The “replace IR35” pledge is a proposal from the opposition, not a change in the law.
  • Shadow Chancellor Andrew Griffith said on 17 September 2026 that a future Conservative government would “replace IR35, not reform it, not review it”.
  • The small‑company thresholds widened to £15 million turnover, £7.5 million balance sheet or 50 employees (meeting two of three). From April 2026, this change has been moving more end‑clients into the “small” exemption, shifting IR35 status responsibility back to contractors’ intermediaries.
  • Inside IR35, you still pay income tax and National Insurance as an employee, without employee rights.
  • What to do now: check every status determination, review your contracts against your working practices, and keep your limited company records clean.

What Is the Latest IR35 News?

On 17 September 2026, Shadow Chancellor Andrew Griffith pledged that a future Conservative government would replace IR35 rather than simply reform or review it. He said the replacement should give genuinely self-employed people greater control over their status while targeting actual abuse. Conservative leader Kemi Badenoch had already included reforming IR35 rules in a wider package of measures to support businesses announced on 11 September 2026.

Advisers who attended a Conservative Party IR35 policy meeting in November 2025, including Charlie Hemsworth of Bauer & Cottrell and Rebecca Seeley Harris of Re Legal Consulting, have called for greater certainty, clarity and fairness for contractors and organisations engaging them. 

Ryan Dawson of Kingsbridge noted that Conservative governments introduced the off-payroll reforms in both the public and private sectors, while Danny Batey of Markel Tax said many clients and contractors would welcome the announcement but cautioned that the detail of any replacement will be important.

The announcement is currently a Conservative opposition policy commitment, not a change in tax law. The existing IR35 and off-payroll working rules remain in force, so contractors and businesses should continue following current HMRC requirements unless the legislation changes. 

Will IR35 Be Scrapped?

For contractors asking will IR35 be scrapped, not until the Conservatives return to government and pass legislation, and there is no timetable for either. Three facts are worth holding onto. First, the pledge has no published design yet: what a replacement would look like, who would define employment status and how a replacement would collect tax, all remain open questions.

Second, Andrew Griffith worked at HM Treasury in autumn 2022, when the then government announced a repeal of the off-payroll reforms in the mini-budget and then quietly dropped it. 

Third, the rules generate significant revenue for HM Treasury, and the same party that now promises wholesale replacement introduced the reforms in April 2017 and April 2021. Advisers and contractors are right to treat this as a signal of intent rather than a settled plan. 

What Rules Apply to Contractors Today?

Today, the same rules apply. Where the end client is medium or large, the client decides whether the engagement falls inside or outside IR35 and must give you a status determination statement. If the role is inside IR35, the fee-payer operates PAYE: you pay income tax and employee National Insurance as an employee would, and the employer National Insurance charge sits on top, which is why blanket inside determinations push day rates down. You keep a 5% allowance for the cost of running your personal service company, but you receive no holiday pay, sick pay or other employment rights. 

Where the end client is small, the off-payroll rules do not apply at all. Your own company keeps the status decision and remains responsible for the tax, exactly as it did before 2017. 

If you are reviewing whether a limited company remains the right structure for your contracting work, our Limited company vs sole trader calculator can help you compare the potential tax position before making a change. HMRC can still open an enquiry into a small-client engagement, so “the client is small” never means “status does not matter”.

What Are the Changes to IR35 From April 2026?

The main changes to IR35 from April 2026 are the widened small-company thresholds. For financial years beginning on or after 6 April 2025, a company qualifies as small if it meets two of three tests: annual turnover of £15 million or less, a balance sheet total of £7.5 million or less, and 50 or fewer employees. 

That is roughly a 50% increase on the previous turnover and balance sheet limits. As companies cross their first accounting date under the new tests through 2026, more of them count as small, and engagements with them leave the off-payroll regime. If you contract for a client that now qualifies as small, your company has taken the status decision back, with both the freedom and the responsibility that brings. Our guide to the latest off-payroll working rules for engineering contractors covers what that means in practice.

What Should Contractors Do Now?

Plan for the rules in force, not the pledge. Four actions cover most contractors:

  • Check every status determination. Ask each medium or large client for the determination statement and check that it reflects your actual working practices rather than relying on a standard template. HMRC’s Check Employment Status for Tax tool can also help assess whether an engagement should be treated as employed or self-employed for tax purposes. HMRC says it will stand by a CEST result where the information supplied is accurate and consistent with its guidance. 
  • Align contract and reality Substitution, control and mutuality of obligation decide your status. A contract that promises substitution you never perform protects no one.
  • Run the numbers before you assume outside is better On an illustrative £60,000 engagement, an inside-IR35 contractor generally takes home somewhere around 60 to 65% of the invoice after PAYE and National Insurance, while an outside-IR35 contractor on a salary-plus-dividends structure commonly lands around 70 to 75% once accounting costs are covered. These are estimates, not advice; our IR35 take-home pay calculator works the comparison on your own figures 
  • Keep clean records Timesheets, contracts, determinations and dividend minutes are what settle an enquiry. Good limited-company record-keeping is cheap insurance.

If you operate outside IR35, the salary-and-dividend split remains the core of the structure. Our guide to the best salary and dividend split for directors in 2026-27 sets out the current thresholds.

How We Can Help

Apex Accountants works with contractors every day on exactly these issues: reviewing status determinations and contracts before you sign, setting the right salary and dividend structure for an outside-IR35 engagement, and keeping your personal service company’s records enquiry-proof. If a client has moved you onto a determination you disagree with, or you want a second opinion on whether a role is genuinely outside, our contractor accounting team can review the position with you. You can also contact us to discuss the specifics of your engagement.

Frequently Asked Questions

Which government brought in IR35?

For anyone asking which government brought in IR35, the original intermediaries legislation was introduced in April 2000 under the Labour government. The later off-payroll reforms shifted status responsibilities to public-sector clients in 2017 and medium and large private-sector clients in 2021. .

What happens if I am inside IR35?

The fee-payer deducts income tax and employee National Insurance through PAYE, plus employer National Insurance on top. You keep a 5% allowance for company running costs, but you get no holiday pay, sick pay or employment rights.

Can I still contract outside IR35?

Yes. Where a role is genuinely self-employed, medium and large clients can still determine it as outside IR35, and small clients are outside the off-payroll rules altogether. Keep evidence of substitution, control and financial risk in case HMRC asks.

Is IR35 being abolished this year?

No. The September 2026 pledge to replace IR35 is an opposition commitment with no published timetable or legislation. The off-payroll rules apply exactly as before until any new law takes effect.

Off-Payroll IR35: What Are the Rules and How Do They Apply?

The off payroll IR35 rules, commonly known as IR35, apply to certain contractors who provide their services through an intermediary, such as a personal service company (PSC). 

What Is IR35?

IR35 is a set of UK tax rules designed to prevent contractors from avoiding employment taxes by working through an intermediary when they would be treated as an employee if they were engaged directly. These off payroll working rules look at the actual working relationship between the contractor and the client, rather than just the wording of the contract. 

The rules look at the actual working relationship between the contractor and the client, rather than just the wording of the contract. If an engagement is inside IR35, income tax and national insurance contributions may need to be deducted from payments made to the contractor.

Which Engagements Do the Off-Payroll Working Rules Apply To?

The off payroll working rules apply to public-sector engagements and to engagements with medium and large clients in the private and voluntary sectors. 

Small private-sector clients are generally exempt from the 2021 off-payroll reforms. In these cases, the contractor’s intermediary is responsible for determining whether IR35 applies and for operating PAYE where required.

From 6 April 2026, the thresholds for determining whether a company is classed as small increased. The thresholds are:

  • Turnover of £15 million or less
  • Balance sheet total of £7.5 million or less
  • 50 employees or fewer

A company will generally be classed as small if it meets at least two of these three conditions.

How Do Off-Payroll Working Arrangements Work? 

Basic Structure

A contractor will usually provide their services through an intermediary, often their own limited company or PSC.

The client may agree to a daily or hourly rate with the contractor or an agency. There may also be one or more agencies involved between the client and the contractor’s PSC.

Who Determines IR35 Status?

For public-sector and medium or large private-sector clients, the client is responsible for determining whether IR35 applies to the engagement.

The client must provide a written Status Determination Statement (SDS) to the contractor and any relevant agency. This should explain the decision and the reasons behind it.

For small private-sector clients, the contractor’s PSC is generally responsible for determining the IR35 status and operating PAYE if the engagement falls inside IR35.

If the Engagement Is Outside IR35

Where an engagement is outside IR35, the PSC will generally receive the agreed payment without PAYE deductions from the fee payer.

The PSC will then deal with its own tax responsibilities, including corporation tax on its profits. The contractor can extract money from the company through salary and/or dividends, subject to the normal tax rules.

If the Engagement Is Inside IR35

Where the off-payroll rules apply, the fee-payer is responsible for making the appropriate PAYE and payroll deductions. 

This will usually involve deducting:

  • Income Tax through PAYE
  • Employee National Insurance contributions

The fee-payer may also need to pay employer National Insurance contributions and the Apprenticeship Levy where applicable.

For small private-sector clients, the contractor’s PSC remains responsible for assessing the engagement and operating PAYE where the engagement is inside IR35.

Risks of IR35 Tax Avoidance Schemes

HMRC has warned about schemes that promise contractors higher take-home pay by converting income into something else, such as a loan or credit.

The guidance points out that:

  • These arrangements may be treated as tax avoidance if they are used to avoid paying the correct Income Tax and National Insurance.
  • Workers using such schemes may later face a bill for unpaid tax and NICs, together with interest and possible penalties.
  • Fees paid to scheme promoters are generally unlikely to be recoverable and may represent a significant proportion of the contractor’s gross pay.

Workers should be careful if an employer, agency or scheme promoter tells them that they must use a particular arrangement. HMRC does not approve tax avoidance schemes.

How Do I Know If IR35 Applies to Me?

IR35 status depends on the nature of your engagement and how you actually work with the client. HMRC and the courts look at the real working relationship, rather than just what is written in the contract. Some of the main factors include:

Control

This looks at how much control the client has over your work, including your working hours, where you work, how closely you are supervised and how you carry out your duties.

If the client has a high level of control over how and when you work, this could be an indication that the engagement falls inside IR35.

Substitution

A genuine right to provide a suitably qualified substitute can support an outside-IR35 position. As a contractor, you should generally be able to arrange for someone else with the right skills to carry out the work where the contract allows this.

If you are personally required to complete the work and cannot provide a substitute, this may indicate an employment relationship.

Mutuality of Obligation

This looks at whether the client is expected to provide regular work and whether you are expected to accept it.

For example, if the client is required to keep providing work and you are expected to continue accepting it, this ongoing obligation can form part of the IR35 assessment.

Financial Risk

The level of financial risk you take on can also be relevant when determining your IR35 status.

For example, if you are responsible for correcting mistakes at your own expense, have business costs that can reduce your profit, or take on the risk of unpaid debts, this may indicate that you are operating as an independent business.

Provision of Equipment

Whether you provide your own equipment or rely on equipment supplied by the client can also be considered.

However, using equipment provided by the client does not automatically mean that your engagement falls inside IR35. The circumstances surrounding the use of that equipment will need to be considered as part of the wider assessment.

Integration

Your position within the client’s organisation can also be relevant. If you are treated in much the same way as permanent employees, this may indicate a greater level of integration.

For example, being subject to line management or appraisals, receiving employee-type benefits, taking on responsibilities normally carried out by permanent staff, or being included in the client’s team structure can all be relevant factors.

Other factors, such as the length of the engagement, whether you work exclusively for one client and the intention of both parties, may also be considered when assessing whether IR35 applies.

What Issues and Risks Do Employers Face Under IR35?

Employers can face significant compliance risks when determining whether contractors fall inside or outside IR35. Many businesses have reviewed their contractor arrangements, but some may still have limited visibility of who their contractors are, how they are engaged and whether overseas contractors or more complex arrangements create additional complications.

Where a business incorrectly determines that a worker is outside IR35 when the rules should apply, the organisation responsible for the determination or the relevant fee-payer may become liable for the tax and National Insurance that should have been deducted.

Additional liabilities, including the Apprenticeship Levy where applicable, may also arise. HMRC may also charge interest and penalties on unpaid amounts.

Good Practice for Employers Under the Off-Payroll Working Rules 

Businesses should regularly review their IR35 processes and contractor arrangements. This may include:

  • Carrying out due diligence across the labour supply chain to identify engagements that could fall within the off-payroll working rules.
  • Providing regular guidance and training to hiring managers and internal teams involved in engaging contractors.
  • Reviewing previously issued Status Determination Statements where working arrangements have changed or relevant case law has developed.
  • Keeping clear records of how IR35 status decisions were reached and ensuring that contractual terms reflect the actual working relationship.
  • Reviewing overseas contractor arrangements where different engagement structures may create additional compliance considerations.
  • Making sure that IR35 determinations are made with reasonable care and that Status Determination Statements are issued with clear reasons.

Workers should also understand how their engagement operates and raise questions where the actual working arrangement differs from the terms of their contract.

FAQs About Off-Payroll Working Rules (IR35)

What are the rules for off-payroll working in the UK?

If you provide services through an intermediary (like a personal service company) and would be an employee if engaged directly, the off‑payroll (IR35) rules apply. For public‑sector and medium/large private‑sector clients, the client must determine status, issue an SDS, and the fee‑payer deducts PAYE tax and NICs if inside IR35. 

What does it mean to be off-payroll?

Being “off‑payroll” means you work via your own company or intermediary instead of being on the client’s payroll. The off‑payroll rules ensure you pay broadly the same Income Tax and National Insurance as an employee would if the engagement is effectively employment (inside IR35). 

Who is exempt from IR35?

Small private‑sector clients are exempt from the 2021 off‑payroll reforms; for those engagements, the contractor’s company decides IR35 and operates PAYE if inside. From 6 April 2026, “small” generally means meeting at least two of: turnover ≤ £15m, balance sheet ≤ £7.5m, and ≤ 50 employees. 

Is it better to be inside IR35 or outside?

For most contractors, outside IR35 is financially better because you can use a limited company, pay a mix of salary and dividends, and keep more take‑home pay. Inside IR35 means being taxed like an employee for that contract, with higher tax/NIC and fewer planning opportunities, though it may suit some preferences. 

Payrolling Benefits in Kind: What Employers Must Do by 2027

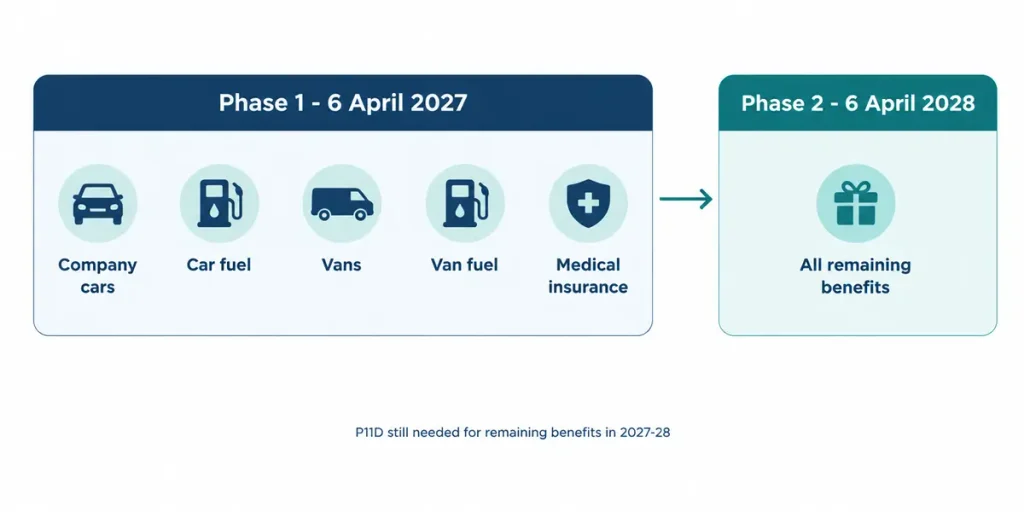
From 6 April 2027, the way UK employers report some benefits in kind will change significantly. Company cars, car fuel, vans, van fuel and employer-provided medical benefits will have to be reported through payroll in real time rather than through the usual year-end P11D process.

Most other benefits will follow from April 2028. However, employment-related loans and accommodation are currently excluded from mandatory payrolling and will remain voluntary until the government confirms otherwise.

For businesses providing taxable benefits to employees, preparation should start well before April 2027.

Key takeaways

  • Mandatory payrolling starts on 6 April 2027 for company cars, car fuel, vans, van fuel and employer-provided medical benefits.
  • Most other benefits in kind become mandatory from April 2028.
  • Employment-related loans and accommodation remain outside mandatory payrolling for now.
  • Both Income Tax and employer Class 1A National Insurance contributions will be reported in real time for mandatorily payrolled benefits.
  • P11Ds will still be required for benefits that remain outside mandatory payrolling.
  • Employers do not need to register for the benefits that become mandatory in April 2027.
  • HMRC plans to remove affected benefits from employees’ tax codes before mandatory payrolling begins.

What is payrolling of benefits in kind?

Payrolling benefits in kind means including the taxable value of an employee’s benefit in each payroll run instead of relying on year-end reporting.

For example, if an employee receives a medical benefit worth £600 for the year, the employer would normally include £50 of taxable benefit in each monthly payroll period. That amount is added for Income Tax purposes rather than being additional cash paid to the employee.

HMRC’s current mandatory payrolling guidance confirms that employers will report affected benefits through payroll software using Real Time Information.

Employers have been able to payroll certain benefits voluntarily for several years. From April 2027, however, payrolling becomes compulsory for the first group of benefits.

What changes from 6 April 2027?

The original mandatory payrolling start date was April 2026, but the government delayed implementation to provide employers, agents and payroll software developers with more time to prepare.

From 6 April 2027, mandatory payrolling applies to:

  1. Company cars
  2. Car fuel
  3. Vans
  4. Van fuel
  5. Employer-provided medical benefits, including relevant private medical cover

These benefits must be reported through the employer’s Full Payment Submission. HMRC’s reporting requirements confirm that the taxable benefit and associated Income Tax and Class 1A National Insurance contributions will be reported in real time.

Employers operating company car schemes should pay particular attention to data quality. The taxable benefit can depend on factors including the car’s list price, CO₂ emissions, fuel type and availability. Our guide to company car tax bands explains how the taxable value is calculated.

What happens from April 2028?

From April 2028, mandatory payrolling is expected to extend to most remaining benefits in kind.

There is an important exception. Employment-related loans and accommodation are not currently scheduled to become mandatory in April 2028. HMRC says these benefits will remain available for voluntary payrolling, with any future mandatory date to be confirmed separately.

Employers should therefore avoid treating April 2028 as the complete abolition of the P11D system.

Timeline of mandatory payrolling: Phase 1 from 6 April 2027 covers company cars, car fuel, vans, van fuel and medical insurance; Phase 2 from 6 April 2028 covers all remaining benefits; P11D still needed for remaining benefits in 2027-28

What happens to P11D forms?

P11Ds will not disappear in April 2027.

For the 2027/28 tax year, benefits outside phase one will generally still need to be reported under the existing year-end arrangements unless they are voluntarily payrolled.

This means a business providing company cars and private medical benefits alongside another non-mandatory benefit could payroll the cars and medical benefits throughout 2027/28 while continuing to report the other benefit after the tax year.

Even after April 2028, P11D and P11D(b) reporting can continue to be relevant for benefits such as loans and accommodation that have not been voluntarily payrolled, as well as certain excluded cases.

Class 1A National Insurance also changes. The employer remains responsible for the contribution, but for mandatorily payrolled benefits it will be calculated, reported and paid through the real-time process rather than solely through the traditional year-end P11D(b) route.

What employers should do now

1. Review and clean benefit data

Benefit records should be checked well before the first mandatory payroll run.

For company cars, make sure information such as list price, registration details, CO₂ emissions, fuel type, employee availability dates and changes during the year is accurate.

For medical benefits, employers need reliable information about the taxable cost attributable to each employee.

Incorrect data can lead directly to incorrect payroll calculations.

2. Do not register for mandatory benefits

Employers do not need to register to payroll company cars, car fuel, vans, van fuel or medical benefits from April 2027.

HMRC’s preparation guidance states that these benefits will enter mandatory payrolling automatically.

A voluntary registration service is instead due to open in November 2026 for employers wishing to payroll benefits that are not mandatory during phase one. The registration deadline for the 2027/28 tax year is 5 April 2027.

3. Check your payroll software

Employers should confirm that their software provider will support the additional benefit-in-kind information required through RTI.

HMRC expects updated technical specifications to be available to software providers in autumn 2026. Businesses using outsourced payroll services should also confirm how their provider will collect benefit information and handle changes during the tax year.

4. Brief employees before April

Employees may notice the tax on benefits more clearly through their regular payslips once payrolling becomes mandatory.

Explaining the change beforehand can reduce queries, particularly for employees receiving company cars or medical benefits.

HMRC has said it will automatically remove mandatorily payrolled benefits from affected employees’ tax codes for the start of the 2027/28 tax year, helping prevent the same benefit being taxed through both the code and payroll.

5. Prepare for changes during the year

Benefits do not always remain unchanged for 12 months.

A company car may be replaced, an employee may join or leave midway through the year, or the taxable cost of a medical benefit may change. HMRC’s real-time approach allows the annual taxable value to be recalculated and the remaining amount spread across the remaining pay periods.

Employers should establish a process for passing these changes to payroll quickly.

6. Plan for the Class 1A NIC cash-flow overlap

There is also a one-off cash-flow consideration in 2027.

Employers may still have Class 1A National Insurance to pay in July 2027 for benefits provided during 2026/27, while simultaneously starting to pay Class 1A NIC in real time on benefits provided during 2027/28.

Businesses should account for this overlap when planning payroll-related cash flow.

A worked example: payrolling a company car

Assume a director has a company car with an annual taxable benefit of £6,000.

Under mandatory payrolling, the employer would normally spread that amount across 12 monthly pay periods:

£6,000 ÷ 12 = £500 taxable benefit per month

If the employee pays Income Tax at 20%, the additional tax attributable to the benefit would be £100 per month. At a 40% Income Tax rate, it would be £200 per month.

The £500 is not additional salary paid to the director. It is included in the payroll calculation so the appropriate tax can be collected as the benefit is provided.

If the car changes during the year and the annual taxable value changes, the employer recalculates the benefit, deducts the amount already payrolled and spreads the remaining taxable amount over the remaining pay periods.

Does this change business expenses?

Ordinary business expenses that are paid or reimbursed and qualify fully for tax relief remain exempt and normally do not need to be reported as benefits in kind.

Different rules can apply where an expense is taxable or does not qualify fully for relief. Employers should therefore distinguish between genuine business expenses and taxable employee benefits rather than treating all expense payments in the same way.

Employees may also be able to claim tax relief on qualifying work-related expenses where the relevant conditions are met.

FAQ

Is the P11D being abolished?

Not completely.

P11Ds will stop being the normal reporting method for benefits brought into mandatory payrolling, but they will continue to have a role for benefits and circumstances that remain outside the mandatory regime.

Loans and accommodation, for example, are currently expected to remain voluntary even after April 2028.

Can I start payrolling before it becomes mandatory?

Existing voluntary arrangements can continue where an employer registered in time for the 2026/27 tax year.

For 2027/28, HMRC plans to reopen voluntary registration in November 2026 for benefits that are not part of the mandatory phase-one group.

There is no need to register company cars, car fuel, vans, van fuel or medical benefits for April 2027 because those categories become mandatory automatically.

What happens if I do nothing before April 2027?

Employers providing benefits covered by phase one will still be required to report them through payroll from 6 April 2027.

HMRC has announced a first-year easement for certain non-deliberate inaccuracies in mandatory RTI reporting during 2027/28. However, deliberate non-compliance is not protected, and normal late-filing, late-payment and statutory interest rules can still apply.

Businesses should therefore use the remaining preparation period to review their records, software and payroll procedures.

Will employees be taxed twice?

HMRC says it intends to remove the mandatorily payrolled benefits from affected employees’ tax codes before 6 April 2027.

Employers should nevertheless make sure benefit information is accurate and encourage employees to check their tax codes and payslips when the new system begins.

How Apex can help

Moving benefits into real-time reporting affects much more than a single payroll field. Employers need accurate benefit records, suitable software, reliable employee data and processes for handling changes throughout the year.

Apex Accountants & Tax Advisors provides payroll services for UK businesses, including PAYE calculations, RTI submissions, payroll records, workplace pension administration and ongoing payroll compliance.

We can also help businesses review their benefit data, prepare payroll processes for the April 2027 transition and coordinate benefit reporting with wider payroll obligations.

With mandatory payrolling approaching, preparing the data and process early can make the first real-time reporting year considerably easier.

Employing Family Members in a UK Business: Why HMRC Is Asking Tougher Payroll Questions

More UK family firms than ever are employing family members, putting spouses, partners, and children on the payroll as they look for tax-efficient ways to run leaner businesses. It is one of the oldest tax planning moves in the book, and when done correctly, it is entirely legal. Yet HMRC continues to open inquiries into exactly this type of arrangement, often years after the salary was first paid. At Apex Accountants, family employment queries now land in our inbox nearly every week, usually starting with some version of the same question: “My accountant said this was fine, so why is HMRC asking questions now?”

We put together this Q&A to explain what proper family employment actually looks like, using the questions our own clients ask us most often.

Yes. There is nothing improper about paying a spouse, civil partner, or child for genuine work. HMRC’s own Employment Status Manual confirms that family employment is treated the same as any other employment relationship, provided the work is real. The trouble starts when the “employment” exists mainly on paper.

What is the “wholly and exclusively” rule everyone mentions?

This is the test HMRC applies to every deduction a business claims, and it matters more with family members than with anyone else. As set out in HMRC’s Business Income Manual, for a salary to reduce your taxable profit, the payment must be incurred wholly and exclusively for the purposes of the business. In simple words, your spouse or child needs to be doing a real job that the business genuinely needs, not simply receiving a wage because they happen to share your surname.

A client who came to Apex Accountants last year had been paying his wife a salary described only as “admin support” for three years, with no timesheet, no job description, and no record of tasks completed. When HMRC opened a check into his accounts, he could not demonstrate what she actually did. The result was a partial disallowance of the deduction and additional tax to pay, entirely avoidable with better record-keeping from day one.

Employing your spouse for tax purposes: does the pay have to match the market? 

Broadly, yes. HMRC’s guidance on wages paid to relatives makes clear that where a family member is paid more than someone unconnected would receive for the same role, skills, and hours, the excess can be disallowed. When employing your spouse for tax purposes, if your spouse manages your books for ten hours a week, the salary should reflect what a bookkeeper would realistically charge for that time, not an amount chosen purely to use up their personal allowance. 

What paperwork should be in place?

At minimum, a family employee should have:

  • A written contract of employment
  • A clear job description and set hours
  • Evidence of work actually carried out, such as invoices raised, emails sent or records maintained
  • Payslips processed through PAYE, exactly as for any other member of staff, after you have registered as an employer with HMRC
  • Pay that meets the National Minimum Wage where it applies, and pension auto-enrolment considered once thresholds are met

Skipping these steps is the single biggest reason family salaries get challenged. It is far easier to keep contemporaneous evidence than to reconstruct it years later during an HMRC enquiry.

Child employment rules UK: Can I employ my children in the business? 

Yes, subject to strict rules that many business owners are unaware of. Under child employment rules UK business owners need to understand, children generally cannot work at all before the age of 13, and even then only light work is permitted, according to GOV.UK’s guidance on the minimum ages children can work. GOV.UK also sets out restrictions on child employment, including limits on hours during term time and school holidays. Local councils can set their own bylaws on top of the national rules, and in most areas a child work permit is required before employment begins.

Once a child reaches school-leaving age, they can work full time, and the National Minimum Wage rates for their age band start to apply. School-aged children are not entitled to the National Minimum Wage, but the work must still be real and properly recorded, exactly as with a spouse.

What happens if HMRC decides the arrangement is not genuine?

If HMRC concludes that a family member is simply a route for shifting income to reduce the household’s overall tax bill, it can apply the settlements legislation. In practice this means the income is taxed as if it had never left the business owner’s hands in the first place, wiping out any saving and often triggering interest and penalties on top.

Our advice to clients

Employing family members can be a smart and legitimate way to run a small UK business, but only when it is handled properly. The role should be genuine, the pay should reflect the work done, and payroll records must be kept up to date. If you employ children, the specific rules around age, working hours, and the type of work they can do must also be followed.

In simple terms, HMRC expects family members to be treated like any other employee. That means clear duties, reasonable wages, proper PAYE reporting where required, and evidence that the work has actually been carried out.

Apex Accountants helps UK business owners review family payroll arrangements, improve compliance, and structure employment in a tax-efficient way. If you are unsure whether your current setup is correct, it is better to review it now than wait for HMRC to ask questions later.

Book a free consultation with Apex Accountants today to make sure your family business is set up properly and confidently.

Payroll Compliance for Event Caterers: Pensions & Seasonal Staff Management

The UK hospitality industry, supporting around 2.6 million jobs in 2025, is a major contributor to the economy. Event catering services often depend on seasonal and temporary workers to meet changing needs. This makes payroll compliance for event caterers more complex than for many other businesses, particularly when managing short-term contracts and peak-season workforces. Clear processes for handling pay, leave, and pensions are essential to remain compliant. Effective seasonal staff payroll management for event catering services allows businesses to meet their legal obligations while maintaining the flexibility needed to operate efficiently during busy periods.

Understanding Payroll Compliance for Event Caterers in 2026

Day‑One Rights for Paternity and Unpaid Parental Leave

From April 2026, the Employment Rights Bill will grant workers day‑one eligibility for paternity and unpaid parental leave. Event caterers hiring new fathers during busy periods will need to allow eligible workers to take leave from their first day of employment. Employers should update contracts and leave policies accordingly. 

Statutory Sick Pay (SSP) Reforms

Two key changes to SSP are expected in April 2026:

  • Removal of the Lower Earnings Limit (LEL): There will be no minimum earnings threshold for SSP, making more staff, including part-time workers, eligible.
  • New rate linked to average earnings: Employees will receive 80% of their average weekly earnings or the flat rate (£118.75), whichever is lower. This ensures better earnings replacement for low-paid staff.

Fair Work Agency and Increased Enforcement

The Fair Work Agency will be established in April 2026 to enforce the National Minimum Wage (NMW), holiday pay, and SSP. Event caterers will face increased scrutiny of pay practices, tip distribution, and record keeping.

Tipping Reforms

The Employment (Allocation of Tips) Act 2023, effective 1 October 2024, requires employers to pass all tips to workers without deductions. The Employment Rights Bill also proposes that, from October 2026, employers must consult workers when creating or changing tipping policies. Event caterers must formalise tipping policies, consult staff, and keep records to avoid tribunal claims.

Dismissal and rehire, anti-harassment, and other changes

Additional changes in October 2026 include:

  • Fire‑and‑rehire restrictions: This practice will become automatically unfair in most cases.
  • Anti‑harassment duties: Employers must show they took reasonable steps to prevent harassment from third-party customers.
  • Longer tribunal time limits: Claims will have six months instead of three to be lodged.
  • Trade-union rights: Employers must inform workers about their right to join a union.

Auto-enrollment and Pensions for Seasonal Staff

Assess each worker during every pay period:

Employers must assess seasonal or temporary workers for auto-enrolment eligibility each time they pay them. This includes staff on irregular hours or casual contracts. If workers meet the age and earnings thresholds, they must be enrolled in a pension scheme.

Use a postponement for very short-term staff:

If workers are with you for less than three months, you can use postponement to delay pension assessments. However, you must apply this postponement on or before the worker’s eligibility date and notify them in writing.

Minimum Contribution Levels and Qualifying Earnings:

Workplace pensions remain at 8% of qualifying earnings, with 5% from the employee and 3% from the employer. Qualifying earnings for 2025/26 are between £6,240 and £50,270. Employers should check for updates when the 2026/27 thresholds are announced. With seasonal fluctuations in staffing, seasonal staff payroll management for event catering services becomes even more important as it ensures that all temporary staff are enrolled correctly in the pension scheme and paid on time.

Future Reforms to Age and Earnings Thresholds:

The Pensions (Extension of Automatic Enrolment) Act 2023 may lower the age threshold from 22 to 18 and remove the lower earnings limit, meaning contributions will begin from the first pound. The government has not yet announced when these changes will take effect.

Holiday Entitlement and Pay for Irregular Hours

Workers Build Up Holiday from Day One

All workers, including those on zero-hours or casual contracts, are entitled to 5.6 weeks of statutory paid holiday per year. Holiday entitlement is accrued from the first day of employment, including during probation, sickness, and parental leave.

New Accrual Method for Irregular Hours and Part-Year Workers

From April 2024, workers with irregular hours or part-year contracts will accrue holiday at 12.07% of hours worked. As part of their event catering pensions and holiday pay responsibilities, employers need to ensure that all temporary workers receive the correct holiday pay, whether it’s accrued or paid out during employment.

Real-Time Information and Payroll Reporting

Employers must use Real-Time Information (RTI) to report payroll data to HMRC every time they pay a worker. Seasonal staff who leave employment must receive a P45, but it will not be submitted to HMRC. RTI-compatible payroll software helps ensure compliance and avoids penalties.

Payroll Best Practices for Event Caterers

To stay compliant, consider the following best practices for managing payroll:

  • Issue written contracts: Ensure all workers receive a statement of employment details, including duties, pay rates, holiday entitlement, and tip distribution.
  • Classify staff correctly: Avoid misclassification of employees, workers, or self-employed staff.
  • Track hours accurately: Use digital time-tracking systems for accurate pay, holiday accrual, and pension assessments.
  • Plan budgets early: Estimate staffing needs and include wages, National Insurance, pension contributions, and holiday pay in your budget.
  • Use postponement strategically: Apply postponement for workers who will leave within three months.
  • Calculate holiday correctly: Use the 12.07% method for irregular hours and part-year workers.
  • Follow RTI rules: Submit an FPS on time, even if paying early (e.g. before Christmas).
  • Develop a tipping policy: Document how tips are collected and distributed, and consult your workforce.
  • Train managers: Provide training on harassment prevention and employment rights.

Case Studies For Payroll Compliance

Case Study  – Festival Catering Company

Situation: A festival catering company approached us when hiring 100 temporary waiting staff for a six-week summer event and needed clarity on managing payroll and compliance for short-term workers. A festival caterer hires 100 temporary waiting staff for a six-week summer event.

Actions Taken:

  • We applied for postponement for workers hired for less than three weeks.
  • Weekly assessments were carried out for workers staying longer than three weeks.
  • Holiday accrual was tracked using a time-tracking app under our guidance.
  • With our assistance, a tipping policy was created and distributed to employees.

Outcome: The company avoided auto-enrolment penalties, ensured fair pay practices, and reduced administrative costs by focusing enrolment on staff staying beyond three months.

Case Study  – Wedding Catering Business

Situation: A small wedding catering business came to us for support in managing payroll for 20 casual servers hired across multiple events throughout the year.

Actions Taken:

  • Contracts were issued up front outlining pay and holiday entitlement following our advice.
  • Digital timesheets were implemented to maintain RTI compliance.
  • Holiday pay was processed in arrears as guided.
  • Anti-harassment training was put in place for staff.

Outcome: The business maintained compliance, improved staff retention, and reduced the risk of tribunal claims, with clients valuing clear and transparent pay practices.

How Apex Accountants Can Help You

Payroll Services 

Expert payroll support for event caterers, including processing wages, HMRC reporting, and handling seasonal staff pay. This helps free up your time and keeps you compliant with HMRC rules.

Pension Auto-Enrolment Support 

Assistance with assessing pension auto-enrolment eligibility, managing postponement, and maintaining pension contributions, so you meet legal duties without confusion.

Holiday Pay & Compliance Advice 

Help with calculating holiday entitlement for irregular hours and zero‑hours staff, and guidance on holiday accrual and payments.

HR and Employment Law Support

Practical help with employment contracts, leave rights, anti-harassment duties, and documentation to match your business needs.

For expert guidance on event catering pensions and holiday pay, and to ensure compliance with all payroll laws for seasonal staff, contact Apex Accountants today.

Payroll and Pensions Compliance for Celebrity Booking Agencies: Auto-Enrolment and Beyond

Celebrity booking agencies work with agents, in-house staff, support teams and short-term performers. Managing pay and pensions is complex, which makes payroll and pensions compliance for celebrity booking agencies an essential operational priority. UK law requires employers to enrol eligible workers in a workplace pension and report pay through Real-Time Information (RTI). With frequent national wage changes, compliance must be part of daily payroll work. This article explains employer duties, auto-enrolment compliance for celebrity booking agencies, and how businesses can maintain reliable payroll processes.

Auto‑Enrolment: who qualifies and how much to pay

Since 2012, automatic enrolment has ensured that eligible workers will receive a workplace pension unless they opt out. Key rules include:

  • Eligibility: workers aged 22 to state pension age earning over £10,000 per year must be automatically enrolled.
  • Contribution bands: contributions apply to earnings between £6,240 and £50,270.
  • Minimum contribution: the total minimum is 8%, made up of at least 3% from the employer and 5% from the employee (including tax relief).
  • Qualifying earnings include salaries, overtime, bonuses, commissions, and statutory payments.

These thresholds apply for the 2025/26 tax year, starting April 6, 2025. For businesses operating seasonal or project-based teams, auto-enrolment compliance for celebrity booking agencies requires careful monitoring of earnings thresholds, opt-outs, and re-enrolment duties throughout the year.

Payroll and Pensions Compliance for Celebrity Booking Agencies: Key Employer Duties

Celebrity booking agencies must follow several payroll rules to stay compliant. These duties apply to all employers in the UK and sit at the core of payroll compliance for celebrity agencies:

  • Full Payment Submission (FPS): report pay, pay‑rolled benefits and deductions to HMRC on or before payday.
  • Employer Payment Summary: please ensure this report is submitted by the 19th of the following tax month to accurately record adjustments and reclaim statutory payments.
  • RTI hours reporting: the government has scrapped plans to require detailed hours data in RTI submissions; employers do not need to provide hours worked from April 2026.
  • Record‑keeping: accurate payroll records remain vital for national minimum wage compliance and potential HMRC audits.

National Minimum Wage updates

The National Living Wage and National Minimum Wage will rise over the next two years. Key rates are:

  • 21 + (National Living Wage): £12.21 per hour from April 2025, increasing to £12.71 per hour from April 2026.
  • 18‑ to 20‑year‑olds: £10.00 per hour rising to £10.85 per hour.
  • Under‑18s and apprentices: £7.55 per hour, increasing to £8.00 per hour.

Agencies must update payroll systems to apply these rates from the effective dates.

Unique challenges for celebrity booking agencies

Celebrity booking agencies face distinctive payroll challenges. Roles vary from permanent staff to short-term performers, and international projects often add extra reporting demands. These shifting conditions mean that payroll compliance for celebrity agencies depends on systems that can adapt to varied workloads and mixed contract types. The main issues agencies address include: As a result, maintaining payroll and pensions compliance for celebrity booking agencies requires systems that can adapt quickly to changing contracts, pay structures, and regulatory obligations

  • Varied workforce: a mix of permanent employees, freelancers and short‑term contractors.
  • Irregular hours: production schedules often involve overtime, night‑shift premiums and changing shift patterns.
  • Cross‑border payments: when international artists perform, payroll must handle multi‑currency payments and comply with foreign tax rules.
  • Different tax regimes: contractors may fall under the Construction Industry Scheme (CIS) or have different tax codes. Systems must handle payroll, CIS deductions, and national insurance accurately.

Because of these complexities, agencies require flexible payroll systems tailored to the entertainment sector.

Case Study: Payroll Solutions for a Film Production

Client: A leading film production company

A film production company approached Apex Accountants to manage the payroll for over 300 cast, crew, and freelancers involved in their latest project. With complex pay structures and a diverse workforce, they faced significant payroll challenges.

Challenge

  • Large Workforce: Over 300 workers with varied pay rates, overtime, and international payments.
  • Payroll Complexity: Managing PAYE, CIS deductions, and multi-currency payments for both domestic and international staff.

Solution

  • Tailored Payroll System: Apex Accountants implemented custom payroll software to track hours, apply the correct pay rates, and automate deductions.
  • Auto-Enrolment & Compliance: We ensured auto-enrolment compliance for eligible workers and processed international payments smoothly.

Results

  • On-time and On-budget: The production was completed as scheduled and within budget.
  • Efficient Operations: Streamlined payroll allowed the production team to focus on creative work.
  • Full Compliance: All payroll and tax obligations were met, with accurate deductions and pension enrolments.

Conclusion

By addressing complex payroll challenges, the production company was able to ensure compliance and allow the creative team to stay focused on the project’s success.

How Apex Accountants helps

Apex Accountants provide end‑to‑end payroll solutions tailored to the entertainment sector. Our services include:

  • Comprehensive payroll management – calculating overtime, holiday pay and shift premiums and managing varied tax codes.
  • HMRC compliance – filing RTI submissions, issuing P60s and P11Ds and adjusting tax codes.
  • CIS compliance for contractors – correctly deducting and remitting taxes.
  • Budget tracking and financial reporting —real-time payroll reports to help you stay on budget.
  • International payroll management – handling currency conversions and cross-border tax filings.

Your next steps

For further support on workplace pensions, explore our Auto‑Enrolment Services. To discuss your specific needs, contact us now.

FAQs

What happens if an employee opts out of auto‑enrolment? 

Employees can opt out within one month of joining the scheme. Contributions made during that period are refunded. Employers must re‑enrol eligible workers every three years.

How do I handle employees on short‑term contracts? 

Use HMRC’s Check Employment Status for Tax tool to decide whether a worker is an employee or contractor. The tool helps determine if the off‑payroll working rules apply, and HMRC will stand by the determination when accurate information is provided.

Can I exceed the minimum pension contribution? 

Yes. Employers and employees can choose to pay higher contributions. Nest explains that employers must pay at least 3% and workers at least 5%, but they can contribute more to build bigger pots.

How to Manage Payroll and Pensions for Renewable Energy Companies

Rising payroll costs and stricter pension duties pose new challenges for UK renewable energy companies. From solar panel installers to offshore wind specialists, employers must manage irregular pay, staff turnover, and auto-enrolment compliance—all while scaling clean energy projects. As regulations tighten, payroll and pensions for renewable energy companies have become key priorities, not just for compliance but also for long-term planning and talent retention. Firms that fail to stay on top of these requirements risk fines from the Pensions Regulator and losing skilled workers to competitors offering better financial infrastructure.

At Apex Accountants, we support payroll compliance for renewable energy businesses through clear systems, digital tools, and sector-specific advice. Our aim is to reduce complexity—so you can focus on delivering sustainable energy projects.

Auto-Enrolment Pension Rules for 2026

All employers must enrol eligible staff into a workplace pension. In 2026, an employee will qualify if they:

  • Are aged 22 or over
  • Are under State Pension age
  • Earn more than £10,000 a year

Minimum contributions in 2026:

  • Employer: 3%
  • Employee (including tax relief): 5%
  • Total minimum: 8%

To meet your legal duties, you must assess staff regularly, issue enrolment letters, and submit your contributions to your pension provider on time. Auto-enrolment for renewable energy staff can become complex when contracts are short-term or earnings fluctuate across projects. Consistency and digital recordkeeping are essential.

Payroll Complexities in the Renewable Sector

Many roles in renewable energy include variable earnings. Engineers, installation teams and technicians often receive:

  • Overtime and performance bonuses
  • Project-based pay
  • Site or travel allowances
  • Weather-dependent pay adjustments

These components affect pension calculations. You must define “pensionable pay” clearly and apply it consistently.

Errors in payroll or pension processing can lead to:

  • Underpaid contributions
  • Non-compliance fines
  • Misreported PAYE data
  • Unexpected project cost overruns

Payroll compliance for renewable energy businesses means using systems that support RTI, track opt-outs, and apply pension rules consistently. Firms that rely on manual payroll risk falling behind as staff and reporting demands grow.

Budgeting for Payroll and Pension Costs

If a technician earns £40,000 annually, your statutory pension contribution is £1,200 per year. Add to that:

  • Employer NICs
  • Holiday pay
  • Payroll software costs
  • Pension scheme admin fees

Project-based firms must build these costs into bids, especially for government-funded or fixed-fee energy contracts.

Delays in pension processing or reporting can disrupt funding schedules and trigger HMRC scrutiny. With multiple project sites and rotating teams, auto-enrolment for renewable energy staff must be part of your cost planning process—not an afterthought.

Offering Better Pension Schemes

To attract and retain skilled staff, many energy firms now offer:

  • Above-minimum employer pension contributions
  • Pension on full salary, not just qualifying earnings
  • Salary sacrifice to cut employer NICs

These benefits reduce staff turnover, boost recruitment, and support long-term workforce planning.

Our Approach to Payroll and Pensions for Renewable Energy Companies

In 2026, renewable energy companies will need to manage complex payroll structures, auto-enrolment duties, and rising pension costs. We provide sector-specific payroll and pension services that reduce admin burden and help protect your business from compliance risks.

We support your operations through:

  • Setting up and managing digital, RTI-compliant payroll systems
  • Monthly processing of PAYE, NICs, and pension contributions
  • Handling auto-enrolment, re-enrolment, and opt-out notifications
  • Implementing salary sacrifice and full-salary pension schemes
  • Forecasting staff costs for project planning and bid proposals

Our team understands the operational pressures of renewable projects. We help you stay compliant, control payroll outgoings, and retain skilled engineers and site staff through competitive pension offerings.

By partnering with Apex Accountants, your business gains the financial confidence to scale sustainably—while staying ahead of 2026 payroll and pension demands.

Get in touch with our team today to discuss how we can support your renewable energy business.

Payroll and Pension Compliance for Training Providers: Managing Freelancers, Contractors and Employed Trainers in 2026

Corporate training providers in the UK are under growing pressure to meet complex payroll and pension requirements. With updated IR35 rules, mandatory digital PAYE submissions from April 2026, and stricter pension obligations, firms that rely on a blended workforce of employees, contractors, and freelance trainers must now operate with increased precision. Failure to assess employment status accurately or fulfil pension duties can result in penalties from HMRC or The Pensions Regulator. Payroll and pension compliance for training providers has become more demanding with the introduction of joint and several liability (JSL) rules and the upcoming pensions dashboards rollout. These changes add administrative strain, especially for providers managing large-scale client projects across multiple regions.

At Apex Accountants, we support corporate training firms in meeting their compliance duties with confidence. Our team handles employment status reviews, PAYE automation, pension assessments, and supply chain audits — giving L&D providers the structure they need to stay compliant and operationally strong in 2026.

Understanding worker status and payroll obligations

Corporate training companies often work with a diverse mix of delivery partners. Accurately classifying each trainer is essential. Employed trainers must be paid via PAYE with National Insurance contributions and RTI filings. Associate consultants or freelance trainers may appear independent, but if they work under your control and on your premises, they could fall within IR35.

From April 2026, if an umbrella company in your supply chain fails to meet its tax obligations, you—the end client—may be held liable under the new JSL rules. Training providers must stay up to date with IR35 rules for freelance trainers, especially where control, substitution, or mutuality of obligation exists.

Compliance changes affecting corporate training providers in 2026

Digital PAYE reporting will become compulsory in 2026, requiring providers to review their payroll systems. Businesses using multiple platforms or fragmented reporting processes should consolidate before the deadline. Firms currently exempt from IR35 rules for freelance trainers may be affected by updated thresholds relating to turnover and balance sheet size. Employment status assessments, accurate RTI submissions, and clear documentation are no longer optional — they’re essential.

Auto-Enrolment and Pension Duties for Training Providers

Employers must automatically enrol eligible trainers into a qualifying workplace pension scheme. While many corporate training providers rely on contractors, some project-based staff may meet the definition of a ‘worker’ under The Pensions Regulator’s criteria. In such cases, auto-enrolment duties apply.

You must also maintain proper records of assessments, enrolments, opt-outs, and contributions, and reassess workers every three years. The pension duties for training providers now carry real enforcement consequences. With pensions dashboards becoming mandatory by October 2026, accurate data will be critical for every business handling long-term engagements.

Checklist for corporate training compliance

  • Assess employment status before assigning trainers to any project
  • Apply PAYE, NI, and RTI rules correctly for all staff and workers
  • Conduct IR35 and JSL reviews for each contractor or umbrella supplier
  • Auto-enrol or formally assess all eligible trainers.
  • Maintain pension communications, contribution records, and re-enrolment dates
  • Use cloud-based payroll software to simplify PAYE, pensions, and trainer tracking
  • Review your internal compliance procedures regularly to reflect new legislation

Case study

A national corporate training provider engaged Apex Accountants after identifying major compliance gaps. Their consultant trainers were operating under unclear contracts, and several PAYE employees had missed enrolment into the workplace pension scheme. Umbrella companies were used inconsistently, without evidence of due diligence.

We began by reviewing each trainer’s status, applying IR35 criteria and checking for pension eligibility. Our team corrected missing auto-enrolment cases and implemented digital payroll software to handle RTI and pensions We also introduced a vetting framework for umbrella suppliers to reduce JSL exposure.

Within a month, the company restored full compliance and avoided over £16,000 in penalties. More importantly, they gained reliable systems and processes that supported future contracts with blue-chip clients — without compliance risk.

How Apex Accountants Supports Payroll and Pension Compliance for Training Providers

At Apex Accountants, we specialise in working with professional services and training providers. We understand the operational realities of corporate L&D delivery — irregular schedules, complex trainer structures, client-led billing cycles, and contractor-heavy teams.

We handle status classification, set up digital payroll and pension systems, and help manage contractor chains with clear risk controls. Our service gives you the visibility and documentation you need to pass audits, protect your margins, and win client trust.

Get in touch with Apex Accountants for expert payroll and pension guidance tailored to your training business.

Payroll and Pension Planning for UX Design Studios: What Employers Need to Know for 2026

As the UX industry evolves, managing payroll and pension obligations is crucial for studios to remain compliant, competitive, and financially stable. With mixed staffing models—including permanent designers, project-based researchers, developers, and long-term contractors—payroll and pension planning for UX design studios is becoming increasingly complex. Regulatory changes in 2026 are expected to bring shifts in payroll costs, National Insurance (NI) rules, and pension obligations. These changes could impact your studio’s financial planning if not managed well.

In this article, we’ll highlight the essential tips for pension and payroll management for UX design studios and provide actionable steps to navigate these upcoming shifts effectively.

Payroll Considerations for UX Studios in 2026

1. Employer National Insurance Contributions (NICs)

Since April 2025, the Employer NIC (Class 1) rate increased to 15% for salaries above the Secondary Threshold, which is set to drop to £5,000 annually.

Why This Matters for UX Studios

  • Variable Salaries Across Roles: UX studios often have varying salaries depending on the role (e.g., junior designers vs senior UX architects).
  • Project-Based Income: With income fluctuating based on the project cycle, this creates payroll unpredictability.
  • Freelancers and Contractors: Freelancers are exempt from employer NICs unless they fall under IR35, in which case NICs apply.

Key Actions for UX Studios

  • Update payroll software to reflect the 15% NIC rate and the £5,000 secondary threshold.
  • Identify contractors operating within IR35, as they will trigger additional NIC costs.
  • Stress-test staffing budgets for junior designers and part-time staff who may now be subject to NICs due to the lower threshold.

2. Employment Allowance

Since April 2025, the Employment Allowance has increased to £10,500, enabling eligible employers to reduce their NIC liability by this amount.

Why This Matters for UX Studios

  • Eligibility: Most small to mid-sized UX studios (fewer than 250 employees) will qualify for this allowance.
  • Excludes Contractors: The Employment Allowance only applies to PAYE employees, not contractors.

Key Actions for UX Studios

  • Confirm your eligibility for the Employment Allowance and apply for it to offset rising NIC costs.
  • Reassess your mix of employees vs. freelancers—consider shifting more roles to PAYE to benefit from the Employment Allowance.

Pension Planning for UX Design Studios in 2026

As part of the UK’s automatic enrolment system, employers must ensure that eligible workers are enrolled in a qualifying pension scheme.

1. Automatic Enrolment Eligibility

Employers are required to automatically enrol employees who:

  • Are aged 22 to State Pension Age.
  • Earn £10,000 or more per year.
  • Work in the UK.

The minimum contribution rate remains at:

  • 5% employee contribution.
  • 3% employer contribution.
  • 8% total (qualifying earnings).

Why This Matters for UX Studios

  • Fluctuating Salaries: Many UX studios rely on part-time specialists or contractors, and their earnings may fluctuate above or below the £10,000 threshold, especially during busy project cycles.
  • IR35 Contractors: Some contractors may be deemed employees under IR35 and therefore eligible for auto-enrolment.

Key Actions for UX Studios

  • Track earnings for part-time employees and contractors whose income may cross the £10,000 threshold mid-year.
  • Make sure your pension scheme covers IR35 contractors treated as workers.
  • Communicate pension contribution structures clearly to staff, particularly around project cycles when earnings may vary.

2. Salary Sacrifice Schemes for UX Studios

Salary sacrifice schemes for UX studios remain a tax-efficient strategy for both employers and employees. By sacrificing part of their salary in exchange for higher pension contributions, employees can reduce both income tax and NICs.

Why This Matters for UX Studios

  • Senior Staff Benefits: UX leads, senior designers, and architects often have higher salaries, making them prime candidates for salary sacrifice schemes.
  • Tax Efficiency: This scheme helps reduce both employee and employer NICs, making it a cost-effective option for both parties.

Key Actions for UX Studios

  • Assess the feasibility of implementing a salary sacrifice scheme for senior employees.
  • Work with your pension provider to create a tax-efficient contribution structure.
  • Include salary sacrifice as part of your employee benefits package to attract and retain top talent.

3. Proposed Pension Reforms (Expected 2026–27)

Government proposals for 2026-27 may impact pension eligibility and contribution structures:

  • Lower Earnings Limit: The £6,240 lower earnings limit for pension eligibility may be removed, making more employees eligible for auto-enrolment.
  • Age Threshold: The auto-enrolment age limit may be reduced from 22 to 18.

Impact on UX Studios

  • Wider Eligibility: More part-time, junior, and younger staff (18–21) may become eligible for pension contributions, increasing the overall cost to the studio.
  • Broader Pool of Eligible Workers: Employees with lower earnings, previously excluded, will now receive pension contributions on all earnings.

Key Actions for UX Studios

  • Plan for higher pension costs as eligibility widens and younger employees become eligible.
  • Review recruitment and onboarding processes to ensure compliance with pension eligibility for junior hires.
  • Update your pension budget to reflect contributions for employees who previously fell below the qualifying earnings band.

Actionable Payroll & Pension Checklist for UX Studios (2026-Ready)

  1. Payroll Updates: Ensure systems reflect the new 15% NIC rate and the £5,000 secondary threshold.
  2. Claim Employment Allowance: Apply for the £10,500 allowance to offset NIC costs.
  3. IR35 Compliance: Review contractor arrangements and ensure any IR35 workers are classified and treated correctly.
  4. Track Pension Eligibility: Monitor earnings for staff nearing the £10,000 threshold or turning 22.
  5. Implement Salary Sacrifice: Introduce salary sacrifice schemes for senior staff.
  6. Prepare for Pension Reforms: Plan for increased pension contributions as auto-enrolment expands.

The Importance of Payroll and Pension Planning for UX Design Studios

In an industry driven by creativity and project cycles, the need for sound payroll and pension planning cannot be overstated. Failing to keep up with changes in regulations can lead to:

  • Unexpected payroll liabilities.
  • Non-compliance with pension regulations.
  • Challenges with talent retention and satisfaction.

Proactive planning not only helps UX studios manage payroll and pension obligations efficiently but also ensures they remain competitive in a rapidly evolving sector.

How Apex Accountants Can Support Your UX Studio

At Apex Accountants, we specialise in providing expert payroll management for UX design studios and pension advice to creative and digital businesses. Our services include:

  • Payroll System Configuration: Ensuring your systems comply with new NIC rates and thresholds.
  • Pension Scheme Advice: Offering insights on automatic enrolment, salary sacrifice, and pension contribution strategies.
  • IR35 Assessment: Helping you navigate the complexities of contractor classifications.
  • Cost Forecasting: Providing financial forecasts for payroll and pension obligations.

Ready to optimise your payroll and pension planning for 2026? Contact Apex Accountants today and let us support your studio’s growth and compliance.

Book a Free Consultation