Payrolling Benefits in Kind: What Employers Must Do by 2027

From 6 April 2027, the way UK employers report some benefits in kind will change significantly. Company cars, car fuel, vans, van fuel and employer-provided medical benefits will have to be reported through payroll in real time rather than through the usual year-end P11D process.

Most other benefits will follow from April 2028. However, employment-related loans and accommodation are currently excluded from mandatory payrolling and will remain voluntary until the government confirms otherwise.

For businesses providing taxable benefits to employees, preparation should start well before April 2027.

Key takeaways

  • Mandatory payrolling starts on 6 April 2027 for company cars, car fuel, vans, van fuel and employer-provided medical benefits.
  • Most other benefits in kind become mandatory from April 2028.
  • Employment-related loans and accommodation remain outside mandatory payrolling for now.
  • Both Income Tax and employer Class 1A National Insurance contributions will be reported in real time for mandatorily payrolled benefits.
  • P11Ds will still be required for benefits that remain outside mandatory payrolling.
  • Employers do not need to register for the benefits that become mandatory in April 2027.
  • HMRC plans to remove affected benefits from employees’ tax codes before mandatory payrolling begins.

What is payrolling of benefits in kind?

Payrolling benefits in kind means including the taxable value of an employee’s benefit in each payroll run instead of relying on year-end reporting.

For example, if an employee receives a medical benefit worth £600 for the year, the employer would normally include £50 of taxable benefit in each monthly payroll period. That amount is added for Income Tax purposes rather than being additional cash paid to the employee.

HMRC’s current mandatory payrolling guidance confirms that employers will report affected benefits through payroll software using Real Time Information.

Employers have been able to payroll certain benefits voluntarily for several years. From April 2027, however, payrolling becomes compulsory for the first group of benefits.

What changes from 6 April 2027?

The original mandatory payrolling start date was April 2026, but the government delayed implementation to provide employers, agents and payroll software developers with more time to prepare.

From 6 April 2027, mandatory payrolling applies to:

  1. Company cars
  2. Car fuel
  3. Vans
  4. Van fuel
  5. Employer-provided medical benefits, including relevant private medical cover

These benefits must be reported through the employer’s Full Payment Submission. HMRC’s reporting requirements confirm that the taxable benefit and associated Income Tax and Class 1A National Insurance contributions will be reported in real time.

Employers operating company car schemes should pay particular attention to data quality. The taxable benefit can depend on factors including the car’s list price, CO₂ emissions, fuel type and availability. Our guide to company car tax bands explains how the taxable value is calculated.

What happens from April 2028?

From April 2028, mandatory payrolling is expected to extend to most remaining benefits in kind.

There is an important exception. Employment-related loans and accommodation are not currently scheduled to become mandatory in April 2028. HMRC says these benefits will remain available for voluntary payrolling, with any future mandatory date to be confirmed separately.

Employers should therefore avoid treating April 2028 as the complete abolition of the P11D system.
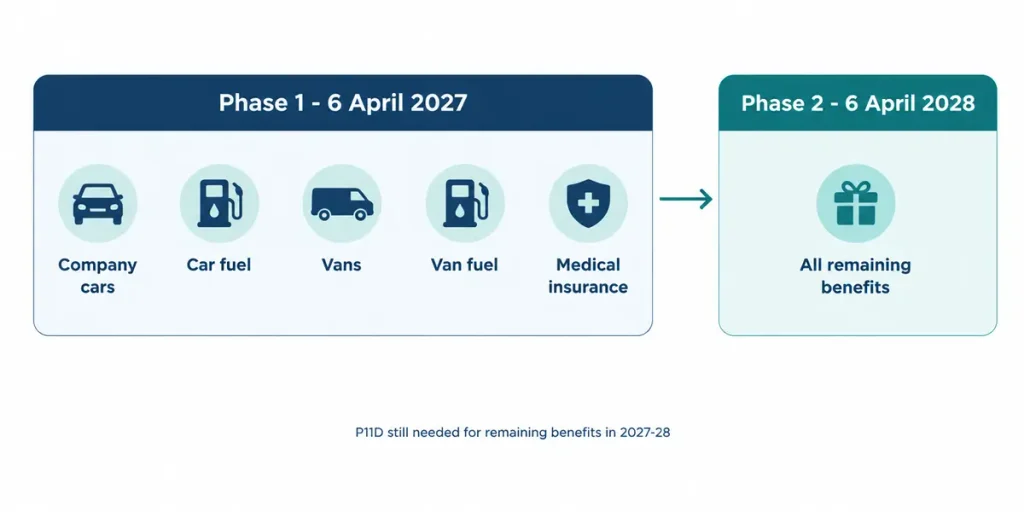
Timeline of mandatory payrolling: Phase 1 from 6 April 2027 covers company cars, car fuel, vans, van fuel and medical insurance; Phase 2 from 6 April 2028 covers all remaining benefits; P11D still needed for remaining benefits in 2027-28

What happens to P11D forms?

P11Ds will not disappear in April 2027.

For the 2027/28 tax year, benefits outside phase one will generally still need to be reported under the existing year-end arrangements unless they are voluntarily payrolled.

This means a business providing company cars and private medical benefits alongside another non-mandatory benefit could payroll the cars and medical benefits throughout 2027/28 while continuing to report the other benefit after the tax year.

Even after April 2028, P11D and P11D(b) reporting can continue to be relevant for benefits such as loans and accommodation that have not been voluntarily payrolled, as well as certain excluded cases.

Class 1A National Insurance also changes. The employer remains responsible for the contribution, but for mandatorily payrolled benefits it will be calculated, reported and paid through the real-time process rather than solely through the traditional year-end P11D(b) route.

What employers should do now

1. Review and clean benefit data

Benefit records should be checked well before the first mandatory payroll run.

For company cars, make sure information such as list price, registration details, CO₂ emissions, fuel type, employee availability dates and changes during the year is accurate.

For medical benefits, employers need reliable information about the taxable cost attributable to each employee.

Incorrect data can lead directly to incorrect payroll calculations.

2. Do not register for mandatory benefits

Employers do not need to register to payroll company cars, car fuel, vans, van fuel or medical benefits from April 2027.

HMRC’s preparation guidance states that these benefits will enter mandatory payrolling automatically.

A voluntary registration service is instead due to open in November 2026 for employers wishing to payroll benefits that are not mandatory during phase one. The registration deadline for the 2027/28 tax year is 5 April 2027.

3. Check your payroll software

Employers should confirm that their software provider will support the additional benefit-in-kind information required through RTI.

HMRC expects updated technical specifications to be available to software providers in autumn 2026. Businesses using outsourced payroll services should also confirm how their provider will collect benefit information and handle changes during the tax year.

4. Brief employees before April

Employees may notice the tax on benefits more clearly through their regular payslips once payrolling becomes mandatory.

Explaining the change beforehand can reduce queries, particularly for employees receiving company cars or medical benefits.

HMRC has said it will automatically remove mandatorily payrolled benefits from affected employees’ tax codes for the start of the 2027/28 tax year, helping prevent the same benefit being taxed through both the code and payroll.

5. Prepare for changes during the year

Benefits do not always remain unchanged for 12 months.

A company car may be replaced, an employee may join or leave midway through the year, or the taxable cost of a medical benefit may change. HMRC’s real-time approach allows the annual taxable value to be recalculated and the remaining amount spread across the remaining pay periods.

Employers should establish a process for passing these changes to payroll quickly.

6. Plan for the Class 1A NIC cash-flow overlap

There is also a one-off cash-flow consideration in 2027.

Employers may still have Class 1A National Insurance to pay in July 2027 for benefits provided during 2026/27, while simultaneously starting to pay Class 1A NIC in real time on benefits provided during 2027/28.

Businesses should account for this overlap when planning payroll-related cash flow.

A worked example: payrolling a company car

Assume a director has a company car with an annual taxable benefit of £6,000.

Under mandatory payrolling, the employer would normally spread that amount across 12 monthly pay periods:

£6,000 ÷ 12 = £500 taxable benefit per month

If the employee pays Income Tax at 20%, the additional tax attributable to the benefit would be £100 per month. At a 40% Income Tax rate, it would be £200 per month.

The £500 is not additional salary paid to the director. It is included in the payroll calculation so the appropriate tax can be collected as the benefit is provided.

If the car changes during the year and the annual taxable value changes, the employer recalculates the benefit, deducts the amount already payrolled and spreads the remaining taxable amount over the remaining pay periods.

Does this change business expenses?

Ordinary business expenses that are paid or reimbursed and qualify fully for tax relief remain exempt and normally do not need to be reported as benefits in kind.

Different rules can apply where an expense is taxable or does not qualify fully for relief. Employers should therefore distinguish between genuine business expenses and taxable employee benefits rather than treating all expense payments in the same way.

Employees may also be able to claim tax relief on qualifying work-related expenses where the relevant conditions are met.

FAQ

Is the P11D being abolished?

Not completely.

P11Ds will stop being the normal reporting method for benefits brought into mandatory payrolling, but they will continue to have a role for benefits and circumstances that remain outside the mandatory regime.

Loans and accommodation, for example, are currently expected to remain voluntary even after April 2028.

Can I start payrolling before it becomes mandatory?

Existing voluntary arrangements can continue where an employer registered in time for the 2026/27 tax year.

For 2027/28, HMRC plans to reopen voluntary registration in November 2026 for benefits that are not part of the mandatory phase-one group.

There is no need to register company cars, car fuel, vans, van fuel or medical benefits for April 2027 because those categories become mandatory automatically.

What happens if I do nothing before April 2027?

Employers providing benefits covered by phase one will still be required to report them through payroll from 6 April 2027.

HMRC has announced a first-year easement for certain non-deliberate inaccuracies in mandatory RTI reporting during 2027/28. However, deliberate non-compliance is not protected, and normal late-filing, late-payment and statutory interest rules can still apply.

Businesses should therefore use the remaining preparation period to review their records, software and payroll procedures.

Will employees be taxed twice?

HMRC says it intends to remove the mandatorily payrolled benefits from affected employees’ tax codes before 6 April 2027.

Employers should nevertheless make sure benefit information is accurate and encourage employees to check their tax codes and payslips when the new system begins.

How Apex can help

Moving benefits into real-time reporting affects much more than a single payroll field. Employers need accurate benefit records, suitable software, reliable employee data and processes for handling changes throughout the year.

Apex Accountants & Tax Advisors provides payroll services for UK businesses, including PAYE calculations, RTI submissions, payroll records, workplace pension administration and ongoing payroll compliance.

We can also help businesses review their benefit data, prepare payroll processes for the April 2027 transition and coordinate benefit reporting with wider payroll obligations.

With mandatory payrolling approaching, preparing the data and process early can make the first real-time reporting year considerably easier.
A UK Guide on Holiday Pay For Employees on Vacation

Managing payroll for employees on vacation can be complex, especially with the recent UK holiday pay reforms. At Apex Accountants, we help businesses handle every aspect of payroll—from salary processing to accurate holiday pay calculations—ensuring full compliance with HMRC regulations. Our payroll experts support companies of all sizes, simplifying processes for both regular and zero-hours employees. Holiday pay for employees is a legal requirement in the UK. Employees are entitled to 5.6 weeks’ paid leave annually, including part-time and irregular workers. Payroll systems must handle vacation periods correctly to stay compliant.

Why Vacation Pay Matters in Payroll

Vacation pay ensures employees don’t lose income when they take leave. It also protects workers’ rights and helps avoid costly disputes or tribunal claims. Employers must integrate holiday pay into the payroll process—so holidays don’t disrupt salary flows.

Who Qualifies for Holiday Pay in UK?

  • Permanent full-time/part-time employees
  • Workers on zero-hours or irregular hours
  • Seasonal or part-year staff

All accrue leave, even if they work only periodically or irregularly.

How to Calculate Holiday Pay for Employees on Vacation

1. Determining the Right Basis

  • For regular pay employees, holiday pay equals the normal weekly or monthly wage.
  • For variable-pay employees, use the 52-week average method (exclude weeks with zero pay).
  • Include regular overtime, commission, or allowances that form part of pay.

2. Rulings from 2024 (for leave years from 1 April 2024)

Recent reforms introduced more flexibility for irregular and part-year workers. Two main options are now permitted:

  • 12.07% accrual: Each hour worked builds up holiday entitlement equivalent to 12.07% of total hours. This approach is ideal for temporary or casual contracts.
  • Rolled-up holiday pay: This method allows employers to include holiday pay within each pay period instead of paying it when leave is taken. Employees receive a small uplift—usually 12.07%—on their normal pay to represent their holiday entitlement. The uplift must be shown separately on the payslip, ensuring full transparency. Rolled-up pay helps businesses maintain simplicity in payroll for irregular or zero-hours staff while staying compliant with UK law.

These methods do not apply to regular salaried workers, who continue to receive paid leave using the traditional entitlement model.

3. Applying the Holiday Pay in Payroll

  • Choose the method: accrual or rolled-up for irregular workers; normal entitlement for regular employees.
  • Configure the payroll system to allocate holiday pay appropriately.
  • Include qualifying earnings (overtime, bonuses) in calculations, especially in the 52-week average.
  • Display holiday pay clearly on payslips if using the rolled-up method.
  • Monitor leave balances and remind staff to take their leave.

Special Cases: Zero-Hours and Irregular Contracts

Since 1 April 2024, employers have been able to use either of two models for these workers:

  • 12.07% accrual: Each hour worked accrues holiday entitlement on a proportional basis.
  • Rolled-up holiday pay: An uplift is applied to each pay period to reflect holiday entitlement.

Employers still have a duty to encourage employees to take leave. They cannot simply pay workers instead of allowing time off, as that would breach health and safety obligations.

Handling Departures: Leaving the Job During Vacation Year

If an employee leaves before taking full entitlement:

  • Pay them for accrued but unused holiday (based on their calculation method).
  • Use the same averaging or uplift methods to compute a fair sum.

Ensuring Compliance: Best Practices for Employers

  • Use clear, simple policies that staff understand.
  • Document calculations and keep audit trails.
  • Ensure your payroll software handles multiple methods (regular vs rolled-up).
  • Train HR/payroll teams on updated rules.
  • Stay updated with changes in law or rulings.

Apex Accountants’ Payroll Services

At Apex Accountants, we deliver end-to-end payroll management tailored to UK regulations. Our services include:

  • Accurate salary and holiday pay calculations
  • Real-time PAYE, NI, and pension submissions
  • Auto-enrolment compliance and re-enrolment monitoring
  • Integration of rolled-up holiday pay for irregular or zero-hours workers
  • Transparent payslips showing holiday pay uplifts
  • Year-end reporting, P60s, and audit-ready documentation

We help employers avoid errors, penalties, and payroll disputes while maintaining accuracy and employee satisfaction.

Conclusion

Getting holiday pay right is essential—not just for compliance, but for staff morale and trust. Use the appropriate method (normal entitlement, 52-week average, 12.07%, rolled-up) depending on worker type. Configure your payroll for employees on vacation to automate the calculations, clearly reflect holiday pay on payslips, and track leave balances. Apex Accountants can assist with setup and reviews to protect your business and ensure peace of mind during vacations.

Book a free consultation today to discuss your payroll needs with Apex Accountants.

Claiming tax relief for working from home

Employees working from home may be able to claim tax relief for certain home-related bills they pay that are related to your work. 

Employers may reimburse employees for the additional household expenses incurred through regularly working at home. The relief covers expenses such as business telephone calls or heating and lighting costs for the room in which you are working. Expenses that are for both for private and business use (such as broadband) cannot be claimed. Employees may also be able to claim tax relief on equipment they have bought, such as a laptop, chair or mobile phone.

Employers can pay up to £6 per week (or £26 a month for employees paid monthly) to cover an employee’s additional costs if they have to work from home. Employees do not need to keep any specific records if they receive this fixed amount. 

If the expenses or allowances are not paid by the employer, then the employee can claim tax relief directly from HMRC. Employees will get tax relief based on their highest tax rate. For example, if they pay the 20% basic rate of tax and claim tax relief on £6 a week, they will get £1.20 per week in tax relief (20% of £6). Employees can claim more than the quoted amount but will need to provide evidence to HMRC. HMRC will accept backdated claims for up to 4 years. 

These tax reliefs are available to anyone who has been asked to work from home on a regular basis, either for all or part of the week including working from home because of coronavirus.

Source: HM Revenue & Customs Tue, 07 Dec 2021 00:00:00 +0100

Reminder for reporting expenses and benefits for 2020-21

The deadline for submitting the 2020-21 forms P11D, P11D(b) and P9D is 6 July 2021. Employees must also be provided with a copy of the information relating to them on these forms by the same date.

P11D forms are used to provide information to HMRC on all Benefits in Kind (BiKs), including those under the Optional Remuneration Arrangements (OpRAs) unless the employer has registered to payroll benefits. This is known as payrolling and removes the requirement to complete a P11D for the selected benefits. However, a P11D(b) is still required for Class 1A National Insurance payments regardless of whether the benefits are being reported via P11D or payrolled.

Where no benefits were provided during 2020-21 and a form P11D(b) or P11D(b) reminder is received, employers can either submit a 'nil' return or notify HMRC online that no return is required. Employers should ensure that they complete their P11D accurately, including all the details of cars and loans provided. There are penalties for late filing of returns.

Employers pay Class 1A National Insurance contributions on most benefits. If you provided taxable benefits to staff or directors your business is likely to have a Class 1A employers’ NIC liability. The deadline for paying class 1A NICs is 22 July 2021 (or 19 July if paying by cheque).

In addition, any tax or National Insurance due for 2020-21 under a PAYE Settlement Agreement (PSA) needs to be paid electronically to clear into HMRC’s bank account by 22 October 2021 (19 October 2021 for payments by cheque).

Source: HM Revenue & Customs Tue, 29 Jun 2021 00:00:00 +0100

Taxable benefit charge – returning office equipment

A taxable benefit charge can apply when employees return office equipment they used to work from home. There was a significant rise in the provision of office equipment to employees working from home due to the COVID-19 pandemic. Qualifying home office equipment is that deemed necessary for an employee to work from home and can, for example, include a laptop, mobile phone, office desk and chair and other necessary computer accessories such as webcams.

Taxable benefit charges are as follows:

  • If you supplied your employees with office equipment so they could work from home, and you did not transfer ownership, there is no tax charge when they return the equipment to you.
  • If you transfer the ownership of home office equipment to an employee at any stage of their employment, a benefit charge generally arises on the market value of the equipment at the time of the transfer, less any amount made good by the employee.
  • If your employee has agreed to purchase home office equipment for use whilst working at home due to COVID-19 and you reimburse the exact expense, unless you have specified that your employee must transfer ownership to you, the ownership of the equipment rests with your employee. There is no benefit charge on the reimbursement.
  • There is also no benefit charge if you allow your employee to keep the equipment as it is something that they already own.
Source: HM Revenue & Customs Tue, 29 Jun 2021 00:00:00 +0100

Employees Tax Relief For Working From Home

These days due to COVI19 most of the employees are working from home. These employees may be able to claim tax relief for any additional costs due to working from home.

No tax relief will be due if employers reimburse employees for the additional household expenses incurred.

What is covered:

The tax relief covers expenses such as business telephone calls or heating and lighting costs. Expenses that are for both for private and business use (such as broadband) cannot be claimed. Employees may also be able to claim tax relief on equipment purchased. For example, a laptop, chair or mobile phone.

Have a look at our Corporation tax page, we are able to advise on which reliefs a business could claim.

Since 6 April 2020, employers can pay up to £6 per week (or £26 a month for employees paid monthly) to cover an employee’s additional costs if they have to work from home. Employees do not need to keep any specific records if they receive this fixed amount.

If the expenses or allowances are not paid by the employer, then the employee can claim tax relief directly from HMRC. Employees will qualify for tax relief based on their highest tax rate. For example, if they pay the 20% basic rate of tax and claim tax relief on £6 a week they would receive £1.20 per week in tax relief (20% of £6).

Employees can claim more than HMRC’s fixed amounts but may need to provide evidence to HMRC of the amount claimed.

This is important to note, that if an employee is working at home voluntarily, they cannot claim tax relief.

However, these tax reliefs are available to anyone who has been asked to work from home due to the COVID-19 outbreak.


If you are looking to know more this new and related laws; feel free to book a free consultation.

Tax Relief For Work Related Expenses

The employees are required to buy equipment to use as part of their employment may be able to claim tax relief based on the cost of the equipment acquired. In most cases you can claim tax relief on the full cost of this type of equipment as it usually qualifies for a type of the Capital Allowance called annual investment allowance. Any tax relief would be reduced if the employer provides a contribution towards buying the item.

The way to claim tax relief depends on the amount you’re claiming. HMRC provides the following information on making a claim:

Claims up to £2,500

You should make your claim:

  • using a Self-Assessment tax return if you already fill one in
  • online or by printing and posting form P87 if you don’t already fill in a tax return 
  • by phone if you’ve had a successful claim in a previous year and your expenses are less than £1,000 (or £2,500 for professional fees and subscriptions)

Claims over £2,500

  • You can only claim using a Self-Assessment tax return. You will need to register if you don’t already complete a return.

There are different rules for employees who use their own uniforms, work clothing, and tools for work. It is possible to claim for the cost of repairing or replacing small tools you need to do your job (for example, scissors or an electric drill), or cleaning, repairing or replacing the specialist clothing (for example, a uniform or safety boots). A claim for valid purchases can be made against receipts or as a ‘flat rate deduction’. However, an employee cannot claim relief on the initial cost of buying small tools or clothing for the work.

‘Tax relief’ means that you either:

  • payless tax to take account of the money you’ve spent on specific things, like business expenses if you’re self-employed
  • get tax back or get it repaid in another way, like into a personal pension

https://www.gov.uk/tax-rel-for-employees/working-at-home

Source: HM Revenue & Customs Wed, 23 Sep 2020 00:00:00 +0100


Tax Relief For Working From Home

Tax Relief For Working From Home

If you have not yet received compensation from your employer you can still claim tax relief for some expenses that result from Working from home. HMRC will usually allow you to claim tax relief if you use your own money for things that you must buy for your job and you only use these items for work. You must make a claim within 4 years of the end of the tax year that you spent the money.

For example, if you use your own uniforms, work clothing, and tools for work. It is possible to claim for the cost of repairing or replacing small tools you need to do your job as an employee (for example, scissors or an electric drill), or cleaning, repairing or replacing specialist clothing (for example, a uniform or safety boots). A claim for valid purchases can be made against receipts or as a ‘flat rate deduction’. However, you cannot make a claim for relief for the initial cost of buying small tools or work clothing.

You may also be able to claim tax relief for using your own vehicle, be it a car, van, motorcycle or bike. As a general rule, there is no tax relief for ordinary commuting to and from your work. The rules are different for temporary workplaces where the expense is usually allowable and if you use your own vehicle to do other business-related mileage.

Note, that if you have agreed with your employer to work at home voluntarily, or you choose to work at home, you cannot claim tax relief on the bills you have to pay. https://www.gov.uk/tax-relie-for-employees/work-at-home


Source: HM Revenue & Customs Sun, 13 Sep 2020 00:00:00 +0100


Kickstart Scheme Officially Launched

The new £2 billion Kickstart scheme that was announced as part of the Summer Economic update by the Chancellor, Rishi Sunak was officially launched by the government on 2 September 2020. The scheme is intended to create hundreds of thousands of high-quality 6-month work placements aimed at those aged 16 to 24.

It is hoped the scheme will help young people into work and spur Britain’s economic revival. The scheme will cover the wages (plus associated costs) of new jobs created for any 16 to 24-year-olds – who are at risk of long-term unemployment and claiming Universal Credit – for a six month work placement.

The government will fully fund each “Kickstart” job by paying 100% of the age-relevant National Minimum Wage, National Insurance and pension contributions for 25 hours a week. Employers will be able to top up this wage and offer kickstarters’ training and support to find a permanent job. The government will also help by paying employers £1,500 to set up support and training for people on a Kickstart scheme placement. Any employers, regardless of size, can apply for funding. However, there are conditions that must be met including that the job placements created with Kickstart funding must be new jobs.

Young people will be referred into the new roles through their Jobcentre Plus work coach with the first Kickstarts expected to begin at the start of November. The scheme, which will be delivered by the Department for Work and Pensions will initially be open until December 2021, with the option of being extended.

Source: HM Treasury Wed, 02 Sep 2020 05:00:00 +0100
Book a Free Consultation