
-
CALL US 0203 883 4777
R&D Tax Relief for Agricultural Equipment Manufacturers in UK – 2025–26 Updates, Eligibility & Risks
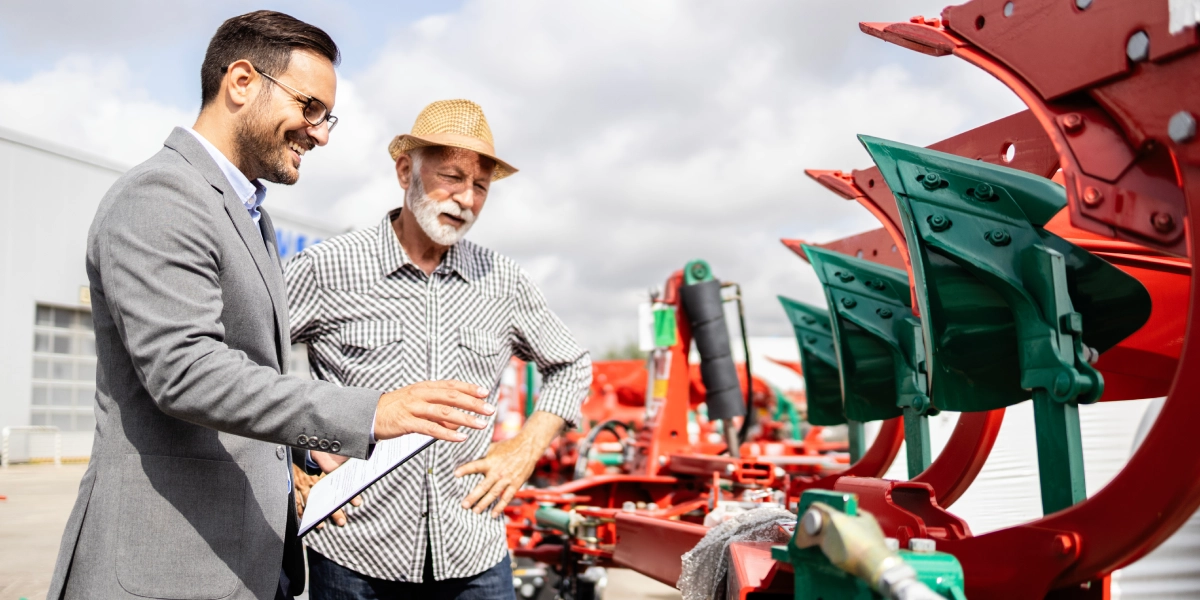
At Apex Accountants, we support UK manufacturers of agricultural equipment and precision farming systems in navigating the evolving R&D tax regime. Below is a clear guide on R&D tax relief for agricultural equipment manufacturers in the UK, covering key 2025–26 changes, what qualifies, how to document claims, and where HMRC may probe.
Key Changes & Overseas Restrictions
- Since 1 April 2024, the SME and RDEC schemes have been merged into a single “merged scheme”.
- Under this regime, subcontracted R&D costs and externally provided worker (EPW) costs incurred overseas will generally not qualify, subject to narrow exceptions.
- Only in limited cases—where carrying out the work in the UK is wholly unreasonable or legally impossible—might overseas R&D pass a three-step test to qualify.
- Also, EPWs must be UK workers, paid via PAYE, and their work physically done in the UK.
These new restrictions particularly affect precision farming projects that rely on foreign subcontractors (for example, overseas sensor calibration or algorithm development). Where possible, key work should be kept within the UK.
What Qualifies in Agri-Equipment & Precision Farming
To benefit from R&D relief for agri-tech innovators, the work must target a scientific or technological advance and solve technical uncertainty.
In the agricultural equipment sector, typical qualifying areas include:
- Sensor design & firmware: developing new sensors or improving accuracy (soil moisture, chemical levels, crop health) under challenging field conditions.
- IoT communications & edge computing: building robust, low-latency connectivity for fleets of machines in remote fields.
- Autonomous robotics: combining perception, actuator control, and navigation in unpredictable terrain (weeding robots, harvesting drones).
- Machine learning / AI models: creating or improving models for yield prediction, pest detection, path planning, and weed recognition under variable conditions.
- Emissions and sustainability systems: innovations for precision dosing, variable-rate application, hybrid/EV control, and telemetry to reduce chemical use or carbon emissions.
Importantly, generic or off-the-shelf software does not count. The work must push boundaries, not merely adapt existing code.
Best Practices For Documenting an R&D Claim For Agri-Equipment
Strong documentation is essential. HMRC now requires an Additional Information Form submitted with the CT600, with project details and narratives.
Your documentation should include:
- Project narratives: the technical challenge, why the solution is uncertain, what you attempted, what failed, and what succeeded.
- Work packages: modular breakdowns (electronic design, algorithm development, field trials, calibration).
- Time tracking and cost allocation: assign staff hours, consumables, testing costs, and software licences.
- Design logs, version control: maintain version history, test results, failure reports, and calibration records.
- Third-party contracts & IP rights: if subcontracted, agreements should assign IP to you and describe exactly which tasks were subcontracted.
- Testing & validation evidence: lab trials, field trials, control vs experiment data.
- Sign-off by competent professionals: engineers or scientists who can vouch for the technical advance.
A well-structured R&D claim for agri-equipment reduces ambiguity and helps withstand HMRC scrutiny.
Risks & HMRC Challenge (Especially on Software / Algorithm Claims)
HMRC has increased scrutiny, particularly on software, algorithm, and AI claims, despite the R&D regime’s intended support for innovation.
Key risk factors:
- Boundary issues: HMRC may argue that some work is routine engineering or customisation rather than qualifying R&D. Be clear where the uncertain innovation lies, not just routine implementation.
- Algorithm / software claims: HMRC expects you to show that the software work resolves technological uncertainty, not mere business logic or data manipulation.
- Insufficient documentation: vague narratives, lack of version history or test evidence, and unclear cost allocation — these invite enquiry.
- Overclaiming subcontractor work or overseas costs: given the new restrictions, claims that include overseas subcontractor or EPW costs are red flags.
- Cap and PAYE/NIC limits: even valid claims may be capped by the PAYE/NIC cap (in the merged scheme) for loss-making firms.
In some recent reporting, HMRC has been challenged over the use of AI tools internally when assessing claims, raising concerns about opaque decision-making.
How Apex Accountants’ R&D Services For Agriculture Equipment Manufacturers Can Help
At Apex Accountants, we specialise in supporting agriculture equipment and precision farming innovators. We help you:
- Classify and map your R&D portfolio to the merged scheme and Enhanced R&D Intensive Support (ERIS) where appropriate
- Design your workstreams to minimise exposure to overseas restrictions
- Prepare clear, audit-ready narratives and evidence packages
- Ensure compliant cost allocation under the new rules
- Defend or support through HMRC enquiries
Conclusion
The 2025–26 R&D reforms mark a decisive shift for UK agricultural equipment manufacturers. Precision farming projects involving robotics, IoT, sensors, or AI remain eligible, but compliance is now tighter—especially for overseas costs and software-heavy claims. Meticulous record-keeping, credible project documentation, and technical clarity are more vital than ever.
At Apex Accountants, we help claim R&D relief for agri-tech innovators confidently and compliantly. Our specialists handle eligibility reviews, evidence preparation, and claim submission to HMRC under the merged scheme. Book your free initial consultation today to review your upcoming R&D projects and secure the relief your business deserves.
Recent Posts

Taking Money Out of a Limited Company: Salary, Dividends and Director’s Loans Explained (2026/27)
Director reviewing salary and dividend figures for taking money out of a limited company on a laptop and desk documents

Autumn Budget 2026 Date Confirmed for 28 October
The Chancellor, John Healey, will deliver the Autumn Budget 2026 on Wednesday, 28 October, HM Treasury has confirmed. The confirmed...

Director Tax Return 2025/26: New Self Assessment Rules for Close Company Directors
If you run an owner-managed or family company, your director tax return 2025/26 asks for more information than ever before....
Van Tax Changes and How they Affect Employer Vehicle Costs
Many UK businesses use double cab pick-ups for work, with some private use allowed. Until recently, these vehicles often sat...

What Happens to Your Personal Allowance over £100,000 Income?
For UK taxpayers asking “What happens to my Personal Allowance if I earn over £100,000?”, the answer depends on HMRC’s...

Can You Reclaim VAT on Transaction Fees in the UK
Most businesses ask this as a yes-or-no question, but UK VAT does not work that neatly. Whether a business can...

Business Rates Relief 2026: Could the Threshold Increase?
The current relief thresholds have not changed. Business rates relief 2026 has not adopted a £17,096 exemption threshold. A newspaper...

What the HMRC Distributions Consultation 2026 Means for Company Owners
Company directors considering a share buyback, capital reduction or restructuring now have another factor to consider. HMRC’s consultation, “Modernising the...
Balancing the Best Salary and Dividend Split for Directors 2026/27
A rise in dividend tax rates for the 2026/27 tax year and the continued freeze on personal allowances have narrowed...

Is the UK Tax System Too Complex for Small Businesses in 2026?
For many small businesses, keeping up with tax now means managing several filing cycles, digital reporting requirements and separate payment...