
-
CALL US 0203 883 4777
Business Rates Relief 2026: Could the Threshold Increase?
The current relief thresholds have not changed. Business rates relief 2026 has not adopted a £17,096 exemption threshold. A newspaper report on 18 September says the Treasury is considering raising the Small Business Rate Relief threshold ahead of the autumn budget.
Its £17,096 figure illustrates an increase in line with inflation, not a precise government plan. GOV.UK still gives the current £12,000 and £15,000 limits. For now, a qualifying business using one property pays no business rates when its property’s rateable value is £12,000 or less; relief tapers to zero by £15,000. Check your current bill under today’s rules rather than budget for an unconfirmed cut.
Key takeaways
- In England, the current full-relief threshold is £12,000 of rateable value for a qualifying single-property business.
- Relief reduces gradually between £12,001 and £15,000; owning or using more than one property can change eligibility.
- The £17,096 figure is a newspaper illustration of possible changes to business rates relief, not an announced threshold or a promised saving.
- If the 2026 revaluation increased your bill, ask your council whether other existing relief protects you.
What Is the Reported £17,096 Business Rates Proposal?
The Telegraph reported on 18 September that officials were considering raising the £12,000 full-relief threshold. It calculated that an increase in line with inflation would put that limit at £17,096 and discussed relief tapering to about £20,000. Those figures illustrate possibilities in one original report, not a Treasury commitment to either amount. The report does not establish whether, when or in what form any change might arrive.
There is no £17,096 threshold in the current published England rules. The practical question for a shop, cafe or small office is whether its current rateable value and property holdings qualify for relief today. Do not assume a budget announcement, start date or backdated refund.
Business rates are an important cost for hotels and other accommodation businesses to monitor. Our guide explains the impact of business rates hikes on UK hotels and accommodation providers.
What Does Business Rates Relief 2026 Cover Now?
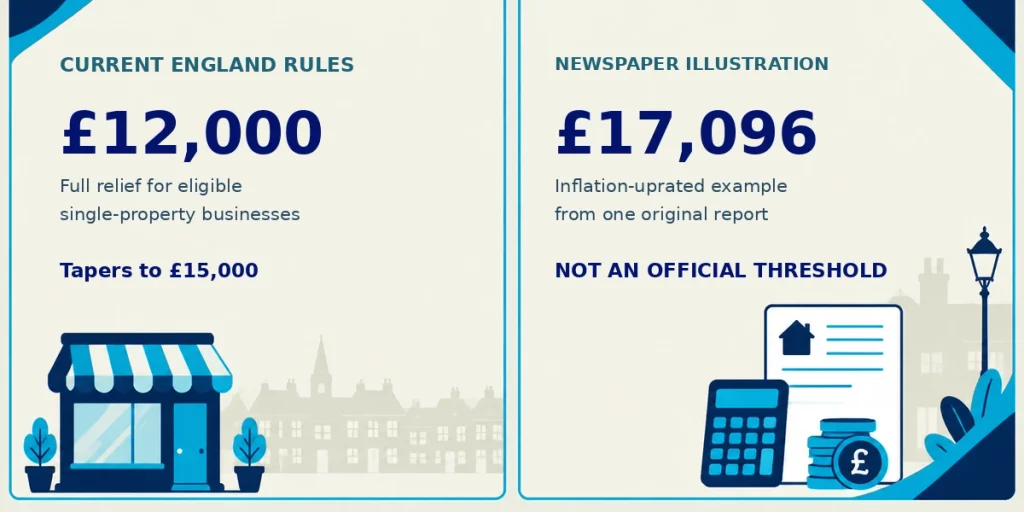
Current small business rate relief can cut the bill for an eligible property with a rateable value below £15,000. If it is the only property your business uses, a value of £12,000 or less normally attracts 100% relief; from £12,001 to £15,000 the percentage falls to zero. For example, GOV.UK gives a property valued at £13,500 a 50% discount. Local businesses can check their eligibility before relying on the current relief thresholds.
Using more than one property does not always rule you out. If you took a second property on or after 27 November 2025, you can keep relief on your main property for 36 months; an earlier second property has a 12-month grace period.
After that, each other property must have a rateable value no higher than £2,899, and the total across your properties must be below £20,000 (£28,000 in London). That existing multi-property limit is not the reported possible £20,000 taper. Your council decides eligibility. England’s rules are the focus here; Scotland, Wales and Northern Ireland operate different schemes.
| England rateable value | Current Small Business Rate Relief position | If the reported illustration became policy |
| £12,000 or less | Normally 100% if this is your only business property | No enacted change |
| £12,001 to £15,000 | Tapers from 100% to 0% | An inflation-uprated full-relief limit could change the discount, but no figure has official status |
| £15,001 to £17,096 | No Small Business Rate Relief under the current threshold | Some eligible properties might qualify if a higher limit were enacted |
A lower retail, hospitality and leisure multiplier can also lead to affecting a qualifying property’s bill. It is not the same thing as changing the Small Business Rate Relief threshold. Hence, keep those two measures separate when comparing bills.
How Could the Proposal Change a Small Shop’s Bill?
Consider a qualifying single-property retail shop in England with a £13,500 rateable value and no other adjustment. Using the 2026/27 small retail, hospitality and leisure multiplier of 38.2p, its starting calculation is £13,500 × 0.382 = £5,157. The current 50% Small Business Rate Relief would reduce that illustrative annual bill to £2,578.50.
If a future change, such as raising the small business rate relief threshold, were made, the same property would be eligible for full relief under the increased threshold, assuming every other input remained the same. The illustrative reduction would be £2,578.50. This is a scenario, not a forecast or an entitlement.
The final rules, timing, property valuation, multiplier and any other relief would determine a real bill. A non-retail office would use a different multiplier, while some premises have further adjustments, so this example is not a universal saving.
For independent high-street shops, our expert accounting support can also help with reviewing business costs and planning around changes to these expenses.

What Should You Check Before the Budget?
First, read your council’s latest business rates bill and check the property’s 2026 rateable value. Then confirm whether the bill already includes Small Business Rate Relief and whether your other premises affect eligibility. If your relief fell after the 1 April 2026 revaluation, ask the council about existing supporting relief rather than waiting for an unannounced reform.
Keep the current bill in your cash-flow forecast. If the government announces a threshold change, compare the published legislation and implementation date with your property’s circumstances before adjusting your expected savings.
To review the impact of Autumn Budget 2025, read: Key Takeaways From Autumn Budget 2025 For UK Business Owners
FAQs About Raising Small Business Rate Relief Threshold Proposal
How Can I Calculate My Business Rates for 2026?
Find the property’s rateable value and the applicable England multiplier, then account for reliefs shown on your council bill. The 2026/27 small-business multiplier is 43.2p; a qualifying retail, hospitality or leisure property below £51,000 uses a 38.2p multiplier. The City of London may use different multipliers. Your council can confirm the final calculation.
What Is the Threshold for Not Paying Business Rates?
For a qualifying business using only one property in England, the current 100% Small Business Rate Relief threshold is a rateable value of £12,000 or less. The £17,096 figure is a newspaper illustration, not an announced threshold. Other reliefs or exemptions have their own conditions.
What Qualifies for Business Relief?
For Small Business Rate Relief, start with the property’s rateable value, how many properties your business uses and the applicable multi-property rules. Other schemes have different tests, so ask your local council to check the specific relief on your bill. A business cannot claim relief under a £17,096 threshold today because no such rule has taken effect.
How Apex Accountants Can Help
Apex can review your rateable value and council bill with you, model your current business-rates cost and update your cash-flow forecast if there are changes to business rates relief. We can also help a shop or hospitality business separate the effect of its multiplier from the relief it receives. Contact Apex Accountants to review your present bill before making a budget-based spending decision.
Recent Posts
Business Rates Relief 2026: Could the Threshold Increase?
The current relief thresholds have not changed. Business rates relief 2026 has not adopted a £17,096 exemption threshold. A newspaper...
Taking Money Out of Your Company: 2026 Rule Changes Explained
On 14 September 2026, HMRC closed its consultation on modernising the taxation of distributions and repayments of capital from companies....
Is the UK Tax System Too Complex for Small Businesses in 2026?
For many small businesses, keeping up with tax now means managing several filing cycles, digital reporting requirements and separate payment...
Payrolling Benefits in Kind: What Employers Must Do by 2027
From 6 April 2027, the way UK employers report some benefits in kind will change significantly. Company cars, car fuel,...
UK Wealth Tax: Would Business Owners and High Earners Pay?
Owning a valuable business does not necessarily mean having substantial cash available personally. Equally, earning a high salary does not...

Self Assessment Registration Deadline: What to Do Before 5 October 2026
We’re increasingly asked by clients who started trading during 2025/26: “Do I need to register for Self Assessment?” It’s a...

R&D Tax Relief 2026: New HMRC Rules and How to Claim Successfully
We’re seeing more companies come to us after having their R&D tax relief claims questioned, returned, or rejected by HMRC....
HMRC Auto-Registration for MTD: What Happens If You Don’t Sign Up First
Sole traders and landlords are increasingly asking what happens if they do not respond to Making Tax Digital sign-up letters....
A Complete Guide to UK Airbnb Tax: Rules, Reliefs and Rates for 2026/27
A host can receive regular Airbnb bookings and still be unsure whether HMRC sees the income as a small side...
Inheritance Tax Planning: A Practical UK Guide for 2026
A couple in their late sixties own a home worth £750,000 and have £700,000 in savings and investments. Their combined...